



PW Consulting: Particle Size Analyzers Market — USD 512M (2025), 6.5% CAGR to 2032

Particle Size Analyzers Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As organizations finalize budgets and strategic roadmaps for 2026, particle size analysis is shifting from a specialist laboratory function to a strategic capability that underpins R&D productivity, regulatory compliance and process optimisation across pharmaceuticals, advanced materials, and industrial manufacturing. Our PW Consulting Particle Size Analyzers Market study — anchored on a 2025 base year with historical coverage 2020–2025 and forward-looking projections through 2032 — quantifies this transition and translates it into actionable decision levers for executive teams.
Particle Size Analyzers Market
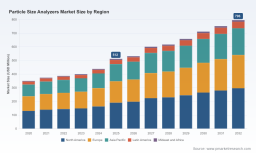
Key macro trajectory: the global market expanded from approximately USD 350 million in 2020 to USD 512 million in 2025, and is projected to continue growing to roughly USD 796 million by 2032, corresponding to a compound annual growth rate (CAGR) of 6.5% over the forecast period. Concentration metrics show a market with influential leaders but substantial niche and regional competitors (CR3 ≈ 38%, CR5 ≈ 42%), a dynamic that has important implications for procurement, partnership and M&A strategies.
Particle Size Analyzers Market
Why this report matters for 2026 strategy
- CapEx prioritisation: Our analysis translates market growth and technology adoption curves into prioritized capital investment timelines. For organisations balancing hospital or laboratory capital budgets under constrained reimbursement environments, this helps pinpoint when to replace, upgrade, or decentralise instrumentation without sacrificing compliance or throughput.
- Product development and formulation: Particle sizing decisions materially affect drug dissolution, bioavailability and excipient performance. We map instrument capabilities to formulation risk profiles so R&D leaders can select measurement approaches that de-risk scale-up and regulatory submissions.
- Procurement & vendor selection: Given the mixed landscape of global incumbents and cost-effective regional suppliers, the study provides a pragmatic framework for vendor shortlists based on technical fit, lifecycle cost and service footprint — critical in environments where instrument uptime and certification matter.
- M&A and partnership scouting: The market’s mid-level concentration and a long tail of specialised players create fertile ground for bolt-on acquisitions and strategic alliances. The report identifies capability gaps and adjacency plays that most acquirers target when building portfolios for laboratory and process analytics.
- Regulatory & compliance planning: We translate standards and certification dynamics into procurement checklists so that organisations using particle size analyzers in regulated workflows satisfy traceability, repeatability and audit requirements efficiently.
What the study delivers — practical, executable assets
This is not a high-level forecast alone. PW Consulting’s deliverables are designed for immediate operational use across functions:
Particle Size Analyzers Market
- Customisable financial model (USD Million base) with scenario toggles for adoption rate, instrument lifetime, service revenue and replacement cycles across our 2026–2032 forecast horizon.
- Vendor scorecards and an RFP template tuned to regulated workflows (pharmaceutical and clinical laboratory requirements), including certifications, warranty, service SLAs and validation support.
- CapEx decision tree and ROI calculators that convert instrument performance attributes into net present value and payback periods under multiple utilisation and reimbursement constraints.
- Regulatory & validation checklist mapped to ISO and CE expectations — enabling compliance-ready procurement for clinical and pharma customers.
- Go-to-market playbooks for instrument manufacturers and distributors, covering segmentation, channel strategy, aftermarket service design and bundling tactics to capture recurring revenue.
- Supply-chain risk heatmaps and mitigation playbooks addressing sourcing of precision optics, medical-grade electronics and other critical components required for high-end laser diffraction systems.
- Scenario analysis and stress-testing: alternative demand paths (conservative, base, and accelerated adoption) with triggers for strategic pivots such as price, innovation or consolidation events.
Market dynamics shaping strategic choices
- Standards and methodological rigor: ISO 13320 remains the established benchmark for laser diffraction particle size analysis, ensuring traceability and repeatability for pharmaceutical and clinical applications. Our report explains how adherence to the standard affects instrument selection, contract wording and validation timelines.
- Regulatory footprint and certification: Manufacturers and buyers alike must navigate CE marking and ISO systems for instruments used in regulated workflows. We outline the certification ladder and downstream implications for procurement cycles and service requirements.
- Capital constraints in clinical settings: Particle size analyzers are classified as laboratory capital equipment and lack dedicated billing codes; acquisition decisions are therefore subject to hospital CapEx cycles and competing priorities. Our analysis converts these constraints into practical procurement windows and financing alternatives for suppliers and institutional buyers.
- Component and supply risk: Precision optics and medical-grade electronics are critical inputs for top-tier laser diffraction instruments. We assess supplier concentration in these upstream markets and offer mitigation strategies — from dual-sourcing to component redesign — that preserve instrument performance while reducing single-source exposure.
Competitive landscape — who matters and why
The ecosystem comprises established instrument manufacturers, platform integrators and regional value players. The leading global manufacturers combine strong instrument portfolios with validated pharma-facing products; regional and cost-driven vendors compete on price and speed-to-deploy for industrial and academic customers. Our competitive profiles include strategic positioning and capability assessments for the key industry players:
- Malvern Panalytical (United Kingdom) — A world-leading supplier of laser diffraction systems with a recognized presence in pharmaceutical particle characterization and instruments tailored for dissolution and bioavailability workflows.
- Danaher Corporation / Beckman Coulter (United States) — Offers a mix of Coulter principle and laser diffraction instruments focused on clinical and pharmaceutical lab environments, leveraging broad life sciences channel reach.
- HORIBA Scientific (Japan) — Delivers laser diffraction solutions spanning sub-micron to larger particle ranges for laboratory research and industrial R&D.
- Anton Paar GmbH (Austria) — Known for precision instrumentation and automation features that appeal to high-throughput labs and process monitoring use cases.
- Bettersize Instruments Ltd. (China) — Competes on cost-effectiveness and entry-level adoption for both lab and industrial applications.
- Microtrac (United States) — Provides a diversified portfolio including laser diffraction, DLS and imaging, useful for organisations needing hybrid measurement capabilities.
- Sympatec GmbH (Germany) — Focused on process monitoring and powder/granule analysis with established systems for continuous measurement.
- Shimadzu, Fritsch, Mettler Toledo and Scitek Global — Each brings complementary strengths in lab instrumentation, sample preparation and market reach; their strategic moves often influence distribution and aftermarket models.
For procurement teams, the competitive implication is straightforward: negotiate beyond instrument price to include validation support, spare parts, training and uptime guarantees. For corporate strategy, opportunities lie in service differentiation and software-enabled analytics that convert single-sale instruments into recurring revenue platforms.
Strategic implications and recommended actions for 2026
- Adopt a phased capital plan: Use the report’s adoption curves and lifecycle models to phase purchases, matching validation timelines and budget cycles while minimising stranded asset risk.
- Design procurement for total cost of ownership: Prioritise suppliers that demonstrate strong service networks, local calibration capabilities and spare-part availability; include performance-based warranty clauses tied to uptime and measurement reproducibility.
- Invest in measurement interoperability: Standardise data outputs and analytical workflows to enable cross-site comparability and faster regulatory filings.
- Explore partnerships and bolt-ons: For manufacturers and investors, pursue acquisitions that extend software analytics, aftermarket service capability or regional distribution to capture higher-margin recurring revenue.
- Mitigate supply-side vulnerabilities: Build supplier scorecards for critical components and integrate alternative sourcing into procurement contracts to avoid disruptions in instrument availability.
How PW Consulting’s study supports your 2026 decisions
Our study is calibrated to the decision cycles that matter in 2026: capital planning, product roadmap prioritisation, vendor contracting and M&A screening. It delivers quantitative forecasts grounded in a 2025 base year, practical tools (financial models, RFPs, checklists) and qualitative insights — enabling cross-functional teams to move from vendor selection to deployment and validation with confidence.
We intentionally keep this preview at a strategic level — the detailed segmentation, vendor scorecards, regional deployment curves and financial-line items are available in the full report and interactive data pack on our website. For teams that need to convert the market trajectory and supplier dynamics into procurement specifications, investment memoranda or M&A targets, the full PW Consulting dataset is designed to be plug-and-play into your 2026 planning processes.
Next steps
Contact PW Consulting to access the complete report and the accompanying Excel model. With the market poised for steady growth at a 6.5% CAGR and clear competitive dynamics, the time to translate measurement strategy into commercial advantage is now.
For detailed analysis of this topic, please visit the official page: Particle Size Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


