



PW Consulting: Oligosaccharide Market to Expand at 6.5% CAGR Through 2032

Oligosaccharide Market 2026: Strategic Preview for Executive Decision-Making
Introduction — Why this study matters in 2026
As PW Consulting’s lead industry analyst, I present a strategic preview of our latest Oligosaccharide Market study designed to guide executives making resource allocation, M&A, and go-to-market decisions in 2026. The global oligosaccharide market is transitioning from niche functional-ingredient status to a broader, multi-channel growth engine driven by advances in precision fermentation, regulatory alignment in major markets, and rising demand across infant nutrition, functional foods, and specialty animal nutrition. Our macro view shows an industry that expanded from approximately USD 122 million in 2020 to USD 170 million in 2025 and is projected to reach roughly USD 261 million by 2032, representing a compound annual growth rate of about 6.5% across the forecast horizon.
Oligosaccharide Market
What this preview delivers — the strategic value for 2026
- Rapid situational awareness for executives who must prioritize investment and commercial initiatives in a competitive, partially consolidated market (CR3 ≈ 34.2%; CR5 ≈ 45.8%).
- A synthesis of demand-side shifts (infant nutrition, functional foods, dietary supplements and beyond) and supply-side dynamics (feedstock volatility, synthesis routes, capacity expansions) that materially affect margin and time-to-market.
- Actionable decision frameworks — scenarios, supplier scorecards, and regulatory playbooks — that allow leaders to test strategic choices under realistic cost and demand assumptions without wading through every granular data table in the full report.
Market trajectory and what it implies for 2026 choices
The market’s steady trajectory to 2032 is not homogeneous: growth pockets are concentrated in segments benefiting from regulatory acceptance of oligosaccharides as functional ingredients and from technology-driven unit‑cost reductions. For 2026 planning, implications are clear:
Oligosaccharide Market
- Scale matters: mid-sized producers with flexible production technologies will retain optionality to serve both high-margin infant nutrition applications and high-volume food and beverage customers.
- Technology mix will be a differentiator: enzymatic synthesis and precision fermentation are no longer experimental—precision fermentation in particular is being commercialized at scale, reducing time-to-spec HMO production and enabling entrants to access infant formula value pools more rapidly.
- Regulatory alignment accelerates commercialization: harmonization around Codex-based standards and explicit national updates to infant formula guidance shorten market entry timelines for fortified formulas, but nuanced safety and claim approvals remain a gating factor.
Key demand and regulatory drivers to factor into 2026 strategies
- Infant nutrition is a strategic lever. Recent regulatory moves—EU rules that permit specific GOS–FOS blends in infant formula formulations, and national-level standard updates aligning with Codex in large markets—have lowered policy uncertainty and expanded addressable formulations. Companies must build regulatory dossiers and clinical evidence plans now to capture formulation shelf-space later in the decade.
- Functional foods and supplements continue to grow as consumers seek microbiome-directed health benefits. This creates parallel channels where product claims and substantiation requirements differ; firms should tailor evidence generation (clinical vs mechanistic) to channel economics.
- Feedstock and energy cost exposure is non-trivial. Sucrose feedstock price swings, coupled with industrial electricity differentials (notably in regions where costs exceed USD 0.15 per kWh), materially influence enzymatic synthesis unit economics. Procurement and location strategy must integrate realistic energy- and feedstock-price scenarios.
- Regulatory gating remains: agencies such as EFSA maintain stringent safety verification and health-claim endorsement processes. Building robust safety dossiers and engaging regulators early will shorten approval timelines and protect commercial claims.
Competitive landscape — who matters and why
The market’s competitive topology is a mix of ingredient majors with deep technical capabilities, specialized enzyme and fermentation players, and regional producers focused on cost-competitive prebiotics. The leading firms we profile in the full study demonstrate three distinct strategic postures:
Oligosaccharide Market
- Global ingredient integrators that combine R&D, clinical evidence, and global supply chains to target infant nutrition and high-value clinical segments (examples include producers commercializing HMOs such as 2'-fucosyllactose via fermentation routes).
- Specialized prebiotic manufacturers that leverage feedstock-anchored supply advantages and scale in FOS/GOS to serve food and supplement customers, often offering both powder and syrup forms to address formulation needs.
- Emergent precision-fermentation entrants and partnerships that compress time-to-market for HMOs and bespoke oligosaccharide structures, creating new competitive pressure on incumbent enzymatic-synthesis producers.
Understanding these archetypes allows companies to select a realistic strategic posture: integrate forward into formulation partnerships, double down on low-cost feedstock production, or partner with precision-fermentation specialists to capture premium infant-nutrition premiums.
Selected company implications (strategic takeaways)
- BASF SE and large ingredient houses: Their capacity to produce HMOs and branded 2'-FL via fermentation positions them to serve infant formula customers who demand secure, traceable supply and regulatory support. For competitors, this raises the bar for evidence generation and supply assurance commitments.
- DSM‑Firmenich and similar integrators: Portfolio breadth in HMOs and formula partnerships means acquisition or co-development moves will remain likely; buyers should model defensive and offensive M&A scenarios around complementary enzyme or fermentation capabilities.
- Specialists like Galam Ltd., BENEO, FrieslandCampina Ingredients and regional manufacturers: They will continue to capitalize on prebiotic demand through capacity expansions, product variants (short-chain FOS, GOS) and flexible supply formats. Their agility creates tactical advantages for fast-moving CPG partners.
- Regional Chinese and other low-cost producers: Domestic regulatory harmonization and scale investments mean these suppliers will remain central to cost-sensitive categories; international buyers should weigh tolling, JV, and procurement contingency options.
Recent developments that will shape 2026 dynamics
- Commercialization moves: Partnerships and launches expanding global HMO supply chains signal the start of a new, larger revenue pool accessible via fermentation-produced HMOs.
- Capacity builds: Announcements of additional FOS production lines and facility expansions reflect producers’ confidence in sustained prebiotic demand and create near-term supply-side pressure on prices for commodity prebiotics.
- Facility upgrades in adjacent ingredient groups (e.g., whey protein and membrane ingredient expansions) matter because co-location and integrated supply capabilities can alter procurement and collaboration economics for infant-nutrition formulators.
What the full PW Consulting report contains — practical, executable content
Our full study is structured to move beyond observation to enable execution. It includes:
- Segment-level forecasts and demand-scenarios (2026–2032) with sensitivity to feedstock and energy prices — provided as interactive models so teams can stress-test their P&L and capital plans.
- Supplier and technology scorecards that evaluate scale, regulatory readiness, cost position, and partnership fit for both enzymatic and precision-fermentation routes.
- Regulatory playbook and timelines for major markets, including evidence requirements for infant-formula claims and pathways for health-claim endorsements.
- Commercial playbooks tailored to three strategic options: scale (cost leadership), premium (HMO and clinically substantiated products), and partnership (co-development with fermentation specialists).
- M&A and partnership target shortlists, with deal rationale, valuation benchmarks, and integration risk matrices.
- Supply-chain resilience checklists and procurement strategies to mitigate sucrose/energy exposure, including tolling, hedging, and alternative feedstock scenarios.
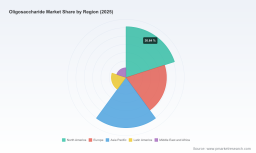
Note: in this preview we intentionally withhold the granular subsegment allocations, regional shares, and detailed price curves that underpin the models — these are available in the full report and are essential for transaction-grade diligence.
Strategic recommendations for 2026
- Prioritize regulatory and clinical evidence investments now. For firms targeting infant nutrition or clinical supplements, the cost of delayed evidence generation materially exceeds near-term CAPEX savings.
- Diversify feedstock and technology exposure. Combine short-term enzymatic supply agreements with a staged commitment to precision fermentation to balance cost risk and access to premium HMOs.
- Reassess procurement and location strategy with energy-price scenarios. Production footprint decisions should be stress-tested against scenarios where industrial electricity and sugar prices fluctuate meaningfully.
- Use capacity announcements as tactical signals. Recent line expansions indicate where near-term sourcing pressure may appear; buyers should secure multi-source contracts or consider strategic equity stakes where supply is tight.
- Prepare measured M&A and partnership plays. Given partial consolidation (CR3 and CR5 levels that indicate room for scale consolidation), opportunistic bolt-ons and co-development agreements can accelerate market entry without full-scale greenfield investments.
Final note — how to use this preview
This executive preview is designed to accelerate decision cycles in 2026. It synthesizes macro growth, competitive dynamics, and regulatory inflection points to help you prioritize options and allocate scarce resources. For teams preparing investment-grade business cases, M&A diligence, or product-launch roadmaps, the full PW Consulting Oligosaccharide Market report provides the necessary granular forecasts, supplier-level benchmarking, and scenario models. Access to those tables and interactive models will convert the strategic directions above into executable budgets and timelines.
For immediate next steps, assemble a cross-functional steering group (R&D, regulatory, procurement, commercial) to use the scenarios above as inputs to a 90-day action plan: secure regulatory advisors for targeted dossiers, open option conversations with fermentation-capable partners, and field-test procurement hedges for feedstock exposure.
For detailed analysis of this topic, please visit the official page: Oligosaccharide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


