



PW Consulting: Blue Laser Diodes Market Set for 8.15% CAGR

Blue Laser Diodes Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As demand for higher-power, more efficient blue laser diodes accelerates across industrial, medical, automotive and consumer segments, senior executives must decide where to allocate capital, whom to partner with, and how to shape supply chains resilient to geopolitical and raw-material shocks. PW Consulting’s latest Blue Laser Diodes Market study (base year 2025, forecast 2026–2032) synthesizes market sizing, technology trajectories, and competitive positioning to support those decisions. This preview outlines the study’s strategic value for 2026 decision-makers while preserving the granular subsegment intelligence available only in the full report.
Blue Laser Diodes Market
Market trajectory in one glance
Between 2020 and 2025, the blue laser diodes market expanded from approximately USD 120.5 million to USD 188.5 million—reflecting rapid technology adoption and an improving efficiency-cost profile for GaN-based devices. Our forecast for the 2026–2032 period projects continued momentum, with the market expected to grow at a compound annual growth rate (CAGR) of 8.15%, reaching roughly USD 326.0 million by 2032. These top-line numbers frame a market that is substantial enough to attract strategic investments, yet still concentrated and technically nuanced, where leadership advantages can be sustained through focused R&D, manufacturing scale, and proprietary process control.
Blue Laser Diodes Market
Why this study matters for 2026 strategic planning
- Actionable market sizing and scenario-ready forecasts: The report provides base-year calibration (2025) and probabilistic forecasts across 2026–2032 to support capital allocation, product roadmap prioritization, and M&A valuation. The forecast enforces a clear growth baseline and alternative scenarios tied to material access, regulatory change, and defense procurement shifts.
- Risk-adjusted supply-chain diagnostics: With critical inputs such as gallium subject to pricing volatility and export controls, the study quantifies exposure points and models the cost and lead-time impacts of different sourcing strategies.
- Competitive playbooks: We map incumbent capabilities, product roadmaps, and manufacturing footprints so executives can prioritize partnerships, licensing, or in-house development to secure performance differentials (e.g., wall-plug efficiency, output power, lifetime).
- Regulatory and demand catalysts: The analysis highlights how defense procurement, medical device regulation, and automotive safety standards create both immediate demand and long-term technology requirements—essential inputs for product-planning and pipeline funding.
Report contents — what you’ll find inside
The full PW Consulting report blends quantitative models, primary interviews, and executable recommendations. Key deliverables include:
Blue Laser Diodes Market
- Comprehensive market sizing (historical 2020–2025; base year 2025) and demand forecasts to 2032 with scenario sensitivity to raw-material pricing and export constraints.
- Segmentation by region, device type (single-mode, multi-mode, other) and end-use application (industrial, medical, consumer electronics, automotive, and others), with demand drivers and buyer behavior analysis—note: detailed subsegment tables are available in the full report.
- Supply-chain mapping and cost-stack analysis, including GaN epitaxy, substrate sourcing, packaging, and test—highlighting where margin compression may occur and where scale can unlock outsized returns.
- Technology roadmap and performance benchmarking, including wall-plug efficiency, optical power scaling, thermal management, and life-cycle reliability parameters critical to different use cases.
- Regulatory, export-control and procurement risk analysis—quantifying the near-term implications of controls on critical precursors and major public-sector procurement programs.
- Detailed competitive landscaping and strategic scenarios for market entrants, incumbents, and potential consolidators, including acquisition and partnership targets.
- Go-to-market playbooks and pricing strategy guides tailored to OEM, aftermarket, and direct-to-system integrator channels.
Competitive landscape — who matters and why
The market is moderately concentrated, such that a handful of manufacturers capture a majority share of revenue; our concentration metrics (CR3 and CR5) show a market where strategic moves by leading firms quickly ripple across the value chain. Below we summarize the positioning of core players covered in the study and the strategic implications for partnerships, procurement, and competitive response.
- Nichia Corporation (Anan, Tokushima, Japan) — Nichia’s focus on high-power blue laser diodes and long-standing expertise in GaN epitaxy position it as a technology and supply anchor for industrial and projector applications. Their product depth and manufacturing scale make them a preferred partner for integrators seeking a reliable supply and robust product specs.
- ams-OSRAM AG (Premstätten, Austria) — With recent product introductions pushing wall-plug efficiencies higher, ams-OSRAM is playing a dual role: improving the efficiency floor for industrial and medical applications and challenging incumbents on cost-per-watt. Their March 2025 launch of a high-power 455 nm device with competitive optical power and efficiency underscores a tactical shift toward value-rich, industrial-grade diodes.
- Sharp Fukuyama Laser Co., Ltd. (Fukuyama, Hiroshima, Japan) — Sharp supplies blue diodes tuned for consumer and automotive applications where integration, thermal packaging, and manufacturing consistency are paramount. Their channel relationships and volume-production experience make them attractive for high-volume OEMs.
- Sony Semiconductor Solutions Corporation (Atsugi, Kanagawa, Japan) — Sony’s strengths in optical storage, projector technologies, and automotive systems give it an edge in application-specific engineering. Expect Sony to compete on system-level integration and application certification rather than on raw device throughput alone.
- KYOCERA SLD Laser, Inc. (Goleta, California, USA) — KYOCERA SLD focuses on GaN-based high-performance diodes for lighting, fiber-coupled systems, and automotive headlights. Their US presence and product mix make them a candidate for defense and aerospace partnerships where domestic sourcing is prioritized.
- BluGlass Limited (Silverwater, Australia) — A smaller, technology-driven player, BluGlass is notable for its GaN processing innovations and targeted applications in defense, quantum, and biotech. For buyers seeking niche performance characteristics or early-access to new manufacturing concepts, BluGlass represents a strategic R&D partner.
Industry dynamics that will shape 2026 decisions
- Raw-material and pricing dynamics: Gallium, a critical precursor for GaN devices, has exhibited price volatility and divergent pricing between domestic and export markets due to export licensing regimes. Companies must model procurement exposure—short-term spot volatility can materially affect margins, while longer-term access constraints may necessitate upstream integration or alternative material sourcing.
- Regulatory and trade controls: Export controls and licensing on gallium are shifting the cost and availability landscape. Firms with global manufacturing footprints will need to evaluate compliance risk, customs delays, and inventory strategies to avoid production interruptions.
- Public-sector procurement tailwinds: Large photonics procurement programs—most notably defense allocations—are a near-term demand accelerator for high-reliability blue laser diodes. These programs also raise the bar for domestic-sourcing requirements, certification, and long-tailed aftermarket commitments.
- Technology-driven differentiation: Wall-plug efficiency, lifetime under elevated temperatures, and fiber-coupling capability are the primary axes of competition. Vendors that can deliver convincing system-level advantages (e.g., lower system cooling costs, longer maintenance intervals) command premium pricing.
Immediate strategic recommendations for 2026
- De-risk supply of critical inputs: Secure multi-sourced gallium contracts, consider strategic investments or upstream partnerships, and build buffer inventories aligned with scenario analyses provided in the full report.
- Prioritize application-led product development: Allocate R&D dollars to improve metrics that matter to high-value buyers (efficiency, lifetime, fiber-coupling). Use co-development agreements with key OEMs to shorten time-to-certification in medical and automotive segments.
- Assess near-term M&A and JV opportunities: Identify small technology players that can accelerate efficiency or packaging improvements and evaluate tuck-in acquisitions to secure IP and accelerate product differentiation.
- Prepare for defense procurement demands: If defense or homeland-security customers are strategic, invest in domestic manufacturing capacities and compliance programs—contracts can be significant but come with higher qualification thresholds and longer payment cycles.
- Adopt a dynamic pricing and channel strategy: Use the report’s pricing models to segment customers by willingness-to-pay and risk tolerance; deploy value-based pricing where system-level savings are demonstrable.
What we deliberately withhold in this preview
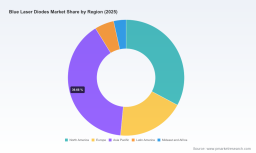
To preserve the strategic value of the full study for subscribing clients, this preview does not disclose detailed regional or application-level revenue splits, nor the granular company market-share tables and price-by-performance curves. Those critical inputs—used for valuation, supply-chain stress-testing, and go-to-market planning—are presented in the full report alongside downloadable models and an executive dashboard.
How to use the full report for execution in 2026
Executives should use the full PW Consulting report to: (1) validate and stress-test board-level capital allocation scenarios; (2) develop supplier scorecards and contingency plans; (3) identify M&A candidates with technical fit and manufacturability; and (4) construct commercial strategies that align product roadmaps to defense and industrial OEM procurement cycles. The report’s scenario modules can be plugged into CFO and operations planning cycles to quantify cash-flow timing, margin resilience, and inventory needs under various raw-material and regulatory outcomes.
For access to the complete dataset, segmentation matrices, competitive market-share tables, and the executable appendices (including supplier shortlists and a roadmap for securing GaN supply), please visit our Blue Laser Diodes Market report page or contact your PW Consulting account lead. The full intelligence package is designed to convert uncertainty into a playbook for sustained leadership through 2032.
For detailed analysis of this topic, please visit the official page: Blue Laser Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


