



PW Consulting: Capecitabine Market to Reach USD 743.71 Million by 2032 (6.01% CAGR)

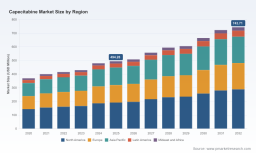
Capecitabine Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As oncology portfolios and procurement strategies are rebalanced for a post‑pandemic, value‑conscious era, capecitabine’s established role as an oral fluoropyrimidine positions it at the intersection of clinical utility, policy pressure, and supply‑chain fragility. PW Consulting’s Capecitabine Market study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes quantitative market trajectory—anchored with a mid‑single‑digit CAGR—and qualitative ecosystem changes that will determine winners and losers in 2026 and beyond.
Capecitabine Market
This preview distills the research’s strategic value for corporate leaders: why the market’s steady expansion (reported through 2025 and modeled into 2032 in USD millions) matters to portfolio prioritization, commercial planning, and risk management—while preserving the detailed segment matrices and price/volume scenarios that are available only in the full report.
Capecitabine Market
Market trajectory: what the headline numbers mean for strategy
Capecitabine demonstrated resilient growth through the early 2020s and, under conservative projection assumptions, continues to expand through 2032 at a projected compound annual growth rate consistent with a mature oncology small‑molecule product class. The base‑year view (2025) and our modeled path into the forecast window (2026–2032) highlight a market that is neither hyper‑volatile nor static: it provides a predictable revenue corridor that supports incremental investment in lifecycle management, manufacturing redundancy, and differentiated formulations.
Capecitabine Market
For executive teams, the practical takeaway from the aggregated market sizing is straightforward: capecitabine remains a stable revenue contributor with upside driven primarily by formulary positioning, label and guideline developments, and shifts in delivery channel mix. These are the levers that will determine whether a company captures a disproportionate share of the steady growth or is marginalised by competitors who move faster on access and risk mitigation.
Competitive landscape — concentrated but contestable
The competitive structure is characterized by a relatively low top‑tier concentration, suggesting room for agile players to scale through tactical wins. Market concentration metrics in the study (CR3 and CR5) point to a market in which originator brands coexist with multiple generic producers and regionally strong marketers. This configuration alters the calculus for entrants and incumbents alike: brand equity and regulatory stewardship matter, but so do supply reliability and distribution partnerships.
- Genentech, Inc. — The originator behind the well‑known branded formulation, retaining significant prescriber awareness and payer negotiation leverage in markets where branded reimbursement persists.
- CHEPLAPHARM Arzneimittel GmbH — Notable for its strategic acquisition of branded rights and for executing region‑specific commercialization tactics, especially in key high‑value markets.
- Indian manufacturers (Alkem, Hetero, Dr. Reddy’s, MSN Laboratories) — Supply‑chain scale and cost competitiveness underpin their roles as primary generic suppliers in multiple markets; partnerships with distribution specialists enable access to developed‑market channels.
- Sandoz and Viatris — Large generics platform players with established regulatory footprints and channel reach, competing on reliability, contract depth, and formulary access.
The full report contains actionable profiles and benchmarked supplier scorecards that quantify manufacturing capacity, regulatory history, and commercial reach—critical inputs when negotiating supply agreements or planning regional launches.
Regulatory and supply‑chain shocks driving near‑term strategy
2024–2025 saw several regulatory and operational events that materially change how organizations should approach capecitabine in 2026:
- Regulatory recalibration: A major regulatory authority completed a label modernization in late 2025 that updated dosing guidance and patient‑selection considerations, and introduced requirements for pre‑treatment genetic screening linked to drug metabolism risk. This change elevates the importance of diagnostics linkage and payer coding clarity.
- Supply interruptions: Market surveillance flagged significant supply interruptions in select developed markets during 2025 caused by unexpected demand surges and logistical incidents. Such episodes emphasize the ROI of dual‑sourcing strategies, buffer inventories for critical strengths, and transparent communication plans with health systems.
- Product security and distribution risk: High‑risk incidents affecting specific lots in certain geographies underline the reputational and regulatory consequences of transport and storage control weaknesses.
For 2026 planning, these signals translate into concrete operational priorities: accelerate DPYD/genotype testing collaborations, validate alternative API and finished‑dosage manufacturers, and update commercial contracting templates to include shortage and quality‑incident clauses. PW Consulting’s report models the financial and operational impact of these mitigants under alternative shortage and uptake scenarios.
Innovation pulse: incremental innovation and next‑generation approaches
While capecitabine is a legacy cytotoxic, clinical innovation is ongoing. Early‑stage programs aim to improve therapeutic index and pharmacokinetics, and initial clinical data presented for next‑generation capecitabine candidates show promise in modulating systemic 5‑FU exposure and safety profiles. Adaptive trial readouts already in progress will influence the competitive window for modified formulations or combination strategies.
Companies evaluating R&D or in‑licensing opportunities should treat these developments as asymmetric bets: low probability of displacement of the existing standard in the short term, but significant long‑term value if improved safety or convenience meaningfully increases use or allows label expansion.
Implications for commercial, R&D, and M&A decisions in 2026
Executives preparing budgets and M&A pipelines for the 2026 fiscal year should prioritize actions that capture near‑term market growth while protecting against downside shocks. Key strategic imperatives include:
- Market access and coding: Invest in payer engagement to ensure DPYD screening workflows are reimbursed and that updated labels do not become access blockers. Bundle diagnostics and drug contracting where feasible.
- Supply resilience: Implement tiered sourcing strategies that balance cost with redundancy. The economics of maintaining a second qualified finished‑dosage supplier are compelling when modeled against the revenue at risk in shortage scenarios.
- Portfolio optimization: Reassess the role of capecitabine within broader oncology portfolios—allocate commercial resources to strengths (formulary markets, hospital contracts) and consider divestiture or partnering where long‑term margins are structurally constrained.
- R&D and lifecycle management: Prioritize investments in formulation improvements or patient‑support programs that strengthen prescriber preference and adherence, and build a defensive moat while next‑generation entrants progress through trials.
- M&A and licensing: Use the current market concentration profile to identify bolt‑on targets that deliver complementary manufacturing capacity, geographic market access, or downstream distribution capabilities.
What the full PW Consulting report delivers (high‑value, execution‑oriented content)
Our comprehensive study blends proprietary modeling with primary interviews to support executable decisions. Highlights include:
- Granular demand and revenue scenarios across the 2026–2032 forecast horizon, denominated in USD (millions), with sensitivity runs tied to regulatory and supply events.
- Detailed competitive scorecards and supplier due‑diligence templates for manufacturers and distributors—designed to accelerate procurement negotiations.
- Commercial playbooks for hospital, retail, and online pharmacy channels that prioritize interventions by return on investment and operational feasibility.
- Regulatory risk matrices and a step‑by‑step DPYD testing implementation guide for market access teams.
- M&A target shortlists and valuation heuristics focused on capacity, regulatory standing, and channel strength.
Note: In keeping with the “trailer” principle, this preview intentionally limits publication of the report’s proprietary segmentation matrices—regional, indication, and distribution splits are summarized in the full report along with downloadable financial models, price sensitivity curves, and contract templates.
How to use these insights in your 2026 planning cycle
Senior leaders should use this research to structure cross‑functional planning workshops that align commercial, manufacturing, and regulatory levers. Practical next steps we recommend for 2026 decision cycles include:
- Immediate: Convene a cross‑functional rapid review of DPYD testing readiness and payer reimbursement pathways.
- Quarter 1: Run a supply‑risk simulation using the report’s scenario models to define minimum buffer inventory and second‑source qualification timelines.
- Mid‑year: Revisit contracting strategies with hospitals and specialty pharmacies to capitalize on channel shifts toward oral oncology care delivery.
- Strategic: Evaluate bolt‑on M&A and licensing opportunities against the report’s supplier scorecards to close capability gaps quickly.
Conclusion — why this study matters for 2026
Capecitabine will remain a strategically important asset class: stable in demand, sensitive to regulatory and supply events, and open to value capture by organizations that align commercial execution with operational robustness. For leaders tasked with 2026 budgets and strategic priorities, the core benefit of PW Consulting’s Capecitabine Market study is that it converts high‑level trends into prioritized, executable choices—backed by scenario‑tested financials and operational playbooks.
To access the full segmentation datasets, supplier scorecards, and the interactive forecasting models that power these recommendations, review the complete report or contact PW Consulting’s industry team to schedule a tailored briefing. The full intelligence is designed to accelerate decision cycles and reduce the downside risk of misallocated capital in a market where stability and timeliness are competitive advantages.
For detailed analysis of this topic, please visit the official page: Capecitabine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


