



PW Consulting: Cochlear Implants Market — USD 1,850M in 2025, 7.5% CAGR (2026–2032)

Cochlear Implants Market 2026: Strategic Intelligence for High-Stakes Decisions
As PW Consulting’s Senior Industry Analyst, I present an executive preview of our forthcoming Cochlear Implants Market study — a practice-oriented strategic asset designed to inform boardrooms, corporate development teams, and market-access planners as they set course for 2026 and beyond. This preview synthesizes the macro trajectory of the market, highlights the competitive inflection points that will shape supplier economics, and spells out the specific decision levers where our full report delivers immediate operational value. To respect the “trailer” principle of this brief, we intentionally withhold granular regional and application-level splits from this summary; the full dataset and model access are available on the report landing page.
Cochlear Implants Market
Macro outlook: a growing, resilient market
The cochlear implants market has shown steady expansion over the first half of the decade, rising from USD 1,280 Million in 2020 to USD 1,850 Million in 2025 (base year). Our modeling projects continued momentum across the 2026–2032 forecast window, with the market expanding at a compound annual growth rate (CAGR) of 7.5% to reach approximately USD 3,064 Million by 2032. This trajectory reflects a combination of technology-driven replacement cycles, broadened clinical indications, and improving access pathways in multiple health systems.
Cochlear Implants Market
- Durable demand fundamentals: demographic tailwinds, rising diagnosis rates, and greater clinician familiarity are driving a predictable underlying growth rate that supports multi-year capacity planning.
- Upside from regulatory and indication expansions: recent approvals and label expansions are accelerating adoption in traditionally later-stage cohorts (notably younger pediatric populations).
- Structural margin pressure and price transparency: procurement programs and reimbursement dynamics are exerting downward pricing pressure in selected markets, necessitating productivity and value-capture responses from suppliers.
Why this matters for 2026 decision cycles
Corporate leaders must translate the market’s steady growth into prioritized investments and risk mitigations in 2026. The choice of where to allocate capital — R&D, commercialization, manufacturing scale, or M&A — will determine whether an organization captures disproportionate share and margin as the market matures.
Cochlear Implants Market
- Go-to-market timing: firms considering product launches or new clinical indications should align regulatory and commercialization calendars to capitalize on the forecasted expansion window. Our full report provides scenario maps linking approval timelines to revenue trajectories under several adoption curves.
- R&D Focus: with firmware/upgradability and patient-facing software emerging as differentiators, investments in modular, upgradable architectures can unlock recurring revenue and reduce product obsolescence risks. The report quantifies the potential aftermarket revenue pool and offers a staged investment roadmap.
- Market access and reimbursement playbooks: stable CPT coding and Medicare policies create a predictable foundation in key payor markets, but the advent of large-volume procurement initiatives in select geographies requires tailored pricing strategies. We provide playbooks that reconcile clinical value propositions with public procurement realities.
- Manufacturing and supply chain resilience: given rising volumes, decisions on capacity expansion versus contract manufacturing should be stress-tested against the forecast’s demand scenarios. The study includes a capacity-planning tool that ties unit economics to lead times and inventory policies.
Competition and concentration — what the data reveals
The cochlear implants market is concentrated, with the top three players capturing a clear majority of market revenue and the top five an even larger share. This concentration creates a dynamic where technology leadership and access play an outsized role in shaping competitive advantage. The competitive landscape is being influenced by several tactical developments in 2024–2025 that have structural implications for 2026 strategy.
- Technology differentiation: the introduction of implants capable of post-market firmware upgrades is a material inflection in product economics — enabling extended device lifecycles, differentiated service offerings, and new software-driven revenue models.
- Regulatory-driven addressable population growth: expanded pediatric indications remove a prior constraint on adoption in select markets, increasing absolute demand and altering the customer mix in clinical segments.
- Procurement participation: inclusion in government volume-procurement programs in high-volume markets materially alters tender dynamics and price elasticity — forcing incumbent suppliers to balance margin preservation with volume capture.
Profiles of strategic players to watch
- Cochlear Limited (Sydney, Australia) — Manufacturer of the Nucleus series, including the recently FDA-cleared Nucleus Nexa System (July 2025), which introduced on-field firmware upgrade capability. This capability reshapes aftermarket engagement and lifecycle value capture.
- MED-EL (Innsbruck, Austria) — Offers a broad portfolio including the Rondo, Sonnet, and Opus series. Notably, in November 2025 MED-EL secured expanded pediatric indications for younger infants, expanding its clinical reach and altering future pediatric cohort sizing.
- Advanced Bionics (Santa Clarita, CA; Sonova subsidiary) — Known for Naida, Neptune, and Harmony processors. The company’s selection in China’s volume-based procurement program signals a competitive posture in large public tenders and underscores the strategic importance of procurement participation.
These players’ moves illustrate two concurrent trends: first, product innovation is migrating toward software-enabled lifetime enhancement; second, payor and procurement mechanisms are forcing a strategic balance between price competitiveness and differentiated clinical/technical value.
Regulatory and reimbursement context — stability amid selective disruption
- Procedure coding stability: CPT code 69930 for cochlear device implantation remains in effect through 2025, providing predictability in procedure-level reimbursement and clinical coding workflows.
- Medicare coverage continuity: Medicare continues to cover cochlear implantation under the existing national coverage determination (NCD 50.3), which reduces reimbursement uncertainty for device suppliers targeting the senior population.
- Country-level procurement initiatives: selective government-led procurement programs are altering pricing norms in high-volume markets and require specific tender strategies; inclusion in these programs can materially accelerate unit uptake but typically compresses margins.
Report deliverables — what you get in the full study
Our full PW Consulting Cochlear Implants Market study is engineered to be immediately actionable for 2026 planning cycles. Key components include:
- Comprehensive market-sizing model (USD, Million) with historical 2020–2025 data and a 2026–2032 forecast. Models are provided in editable format so teams can run alternate scenarios.
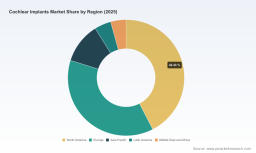
- Segmentation by product type, patient cohort, and region (note: detailed segment data are available in the full report; summary indicators in this preview intentionally omit granular splits).
- Competitive benchmarking: product feature maps, patent landscaping, and a timeline of regulatory events tied to commercial impact assessments.
- Procurement and reimbursement playbooks: country-level reimbursement matrices, tender strategy templates, and payer negotiation playbooks calibrated for 2026 dynamics.
- Go-to-market execution guides: channel selection analysis, referral pathway optimization, and clinician adoption levers tailored for new-indication launches.
- M&A and partnership scoring tool: shortlists of potential tuck-ins and alliance targets, valuation sensitivity analysis, and integration-risk checklists.
- Risk register and mitigation blueprints: supply-chain stress tests, competitive response simulations, and regulatory change scenario planning.
How to use the study in 90/180/360-day planning horizons
- Next 90 days: Use our clinical-indication and reimbursement matrices to validate product claims and refine messaging for payor dossiers and clinician KOL engagement. Short-term actions include realigning commercial targets by facility type and initiating reimbursement discussions where label expansions open new patient cohorts.
- Next 180 days: Finalize capacity and supply-chain decisions using the model’s mid-case demand forecast; begin pilot launches in prioritized geographies where procurement and reimbursement signals align. Review potential partnership targets identified in our M&A tool.
- Next 360 days: Execute product-upgrade monetization strategies, roll out aftermarket software/service offers, and secure long-term contracts in key public procurement programs where feasible. Track the impact of pediatric indication expansions on device mix and training needs.
Strategic takeaways — what leaders must not overlook
- Software and upgradability are now strategic product pillars: organizations that lock into static hardware-only models will face increasing aftermarket disadvantage.
- Market concentration favors those who can combine clinical credibility with procurement-savvy pricing strategies: your competitor set is consolidated and able to shift market norms quickly.
- Regulatory and reimbursement stability provides a runway for investment — but targeted procurement programs can create asymmetric risk/reward profiles that must be modeled explicitly.
- Operational readiness — especially manufacturing flexibility and clinician training programs — will determine whether forecasted volume growth translates into higher share or simply fuels incumbents.
PW Consulting’s full Cochlear Implants Market report provides the granular segmentation, model access, and playbooks that senior teams need to convert the market’s steady growth into sustainable competitive advantage. For teams making allocation decisions in 2026, the difference between acting on headline growth and acting on calibrated, segment-level insights will be measured in share gains, margin resilience, and speed to market.
To access the complete dataset, interactive models, and the tactical playbooks referenced here, please visit our report page — where the full intelligence package is available for download and licensing.
For detailed analysis of this topic, please visit the official page: Cochlear Implants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


