



PW Consulting Outlook: Karl Fischer Titrators Market to Grow at 5.5% CAGR

Karl Fischer Titrators Market — Strategic Outlook for 2026: A PW Consulting Executive Brief
Executive snapshot
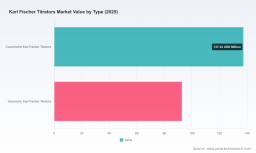
The Karl Fischer titrators market sits at the intersection of analytical precision, regulatory rigor, and incremental digital innovation. Our PW Consulting study — with a 2025 base year and a 2026–2032 forecast horizon — shows a market that expanded steadily through the early 2020s and is expected to continue growing at a mid-single-digit compound annual growth rate (CAGR) of 5.5%. Measured in USD (Million), the market grew from approximately 170 million in 2020 to roughly 230 million in 2025, and PW forecasts a continuation of that trajectory into the early 2030s. This brief explains why those macro dynamics matter for executive decisions in 2026, what tactical moves will likely create competitive advantage, and how to use the full report to operationalize strategy without revealing the granular segmentation tables we reserve for subscribers.
Karl Fischer Titrators Market
Why 2026 is a strategic inflection point
-
Regulatory pressure meets digital opportunity. Two trends converge in 2026: reinforced regulatory requirements for data integrity and cyber resilience in laboratory environments, and a rapid emergence of software-enabled instrumentation (AI-assisted calibration, remote diagnostics, secure connectivity). Compliance requirements such as FDA 21 CFR Part 11 and regional cyber rules are forcing instrument vendors and laboratory operators to rethink both instrument design and lifecycle management.
Karl Fischer Titrators Market -
Market scale supports focused investment. The market’s scale and predictable growth at a 5.5% CAGR create room for targeted R&D and bolt-on acquisitions. The overall market size trajectory (from low hundreds of millions in 2020 to a mid-three-hundreds projection by the end of the forecast) is large enough to justify investments in modular instrument platforms, reagent ecosystems, and software services that extend recurring revenue.
Karl Fischer Titrators Market -
Concentration shapes competitive tactics. The market displays a relatively high concentration at the top: the three largest suppliers hold a substantial majority of commercial volumes, and the top five dominate even further. This concentration creates both barriers and opportunities — scale advantages for incumbents, and whitespace for niche players that can deliver distinct value (e.g., field-ready analyzers, reagent sustainability, or tightly integrated LIMS/ERP connectivity).
What the full PW report delivers (practical contents)
-
Actionable market model: a bottom-up revenue model across historical (2020–2025) and forecast (2026–2032) horizons, with sensitivity scenarios tied to adoption rates of automated and portable solutions, reagent pricing, and regulatory-driven replacement cycles.
-
Decision-ready playbooks: tailored strategic options for vendors, OEMs, reagent suppliers, and laboratory groups — covering go-to-market, product development roadmaps, partnerships, and M&A priorities for 12–36 month timeframes.
-
Channel and pricing analysis: diagnostics on distributor economics, service and consumable margins, and recommended pricing levers to protect installed-base economics while accelerating consumables uptake.
-
Risk and compliance checklist: concrete steps to align instrument design and software stacks with data integrity and cyber regulations, including recommended controls for audit trails, user access, and secure telemetry.
-
Operational playbook for labs: practical protocols for reagent management, calibration cadences, sample handling, and instrument selection criteria for laboratories operating under GMP or in field conditions.
-
Competitive benchmarking: vendor scorecards across product breadth, automation level, reagent ecosystems, software capability, and service footprint — used to identify realistic partnership or acquisition targets.
Key dynamics that will shape purchasing and investment decisions in 2026
-
Data integrity and cyber-regulatory compliance: Vendors and lab managers must build towards compliance not just for validation but as a commercial differentiator. Instruments that provide secure telemetry, immutable audit trails, and configurable user roles will command premium positioning in regulated verticals.
-
Consumables and reagent economics: Routine reagent stability — for example, standard solvents used in volumetric titration — degrades over time and imposes recurring operational costs and QC burden. Our analysis includes operational scenarios where a typical solvent requires systematic titer checks and replenishment planning, affecting total cost of ownership and service models.
-
Shift to automation and field-capable devices: The release of compact and wireless analyzers opens new use-cases (on-site QC, in-line process monitoring). Vendors offering seamless handoff between lab-grade accuracy and field portability will capture incremental market share.
-
Software and AI-enabled measurement assurance: Recent product introductions with AI-assisted calibration and predictive maintenance capabilities reduce downtime and enhance reproducibility. Embedding these capabilities into service contracts increases recurring revenue and stickiness.
Competitive landscape — what incumbents and challengers are doing
The market contains long-established instrumentation leaders with comprehensive portfolios and multiple specialist players that address niche verticals. Notable vendors and their strategic postures include:
-
Metrohm AG — Swiss instrumentation leader focusing on both volumetric and coulometric titrators, increasingly integrating analytics and remote diagnostics into its product stack. Recent product introductions emphasize accuracy and compliance-friendly data handling.
-
Mettler Toledo — a US-headquartered incumbent pushing high-throughput automation, with oven autosamplers and algorithmic advances designed for regulated environments and large-scale QC labs.
-
Xylem Analytics — European player with a focus on modular automatic titrators that balance trace-level sensitivity with industrial robustness, positioning into process and lab workflows.
-
Regional and specialist players — manufacturers from Japan, China, and the US (including Hiranuma, KEM, Koehler, Hanon, Infitek, Hanna, Hach) who pursue vertical depth (petrochemicals, food, pharmaceuticals) or cost-competitive offerings and firmware-driven differentiation.
-
Recent moves — The competitive timeline through 2024–2025 showed multiple suppliers launching AI-enabled instruments, firmware upgrades for stability, reagent partnerships for greener chemistries, and the emergence of rugged portable analyzers suitable for field work.
Strategic implications and recommended actions for 2026
-
For vendors seeking growth: Adopt a two-track product strategy — (1) defend and expand installed-base value through software, services, and consumables; (2) pursue adjacent growth via portable/field instruments and reagent sustainability initiatives. Prioritize integrations that reduce laboratory friction (LIMS, ERP) and address CFR 21 Part 11 requirements out of the box.
-
For potential acquirers: Target niche players with unique IP in AI-assisted titration or proprietary reagent formulations. Given the market concentration, bolt-on acquisitions can rapidly improve scale in service coverage or expand a vendor’s consumables funnel.
-
For laboratory managers and end-users: Reassess procurement criteria to include lifecycle costs (reagents, calibration intervals, and software subscription fees) and cyber-compliance readiness. Operational playbooks that tighten reagent management (to counter solvent titer drift) will materially improve measurement consistency.
-
For reagent suppliers: There is a commercial opening for greener, more stable formulations and reagent-as-a-service subscriptions that reduce customer operational overhead and create recurring revenue streams.
Risk map — what to watch through 2026
-
Regulatory shock: Stricter regional cyber and data regulations could increase time-to-market for connected devices unless compliance is redesigned into product roadmaps early.
-
Supply and raw-material volatility: Periodic degradation of key solvents and the need for frequent re-titration create operational risk and cost pressure for laboratories, an area where improved reagent stability could be a decisive differentiator.
-
Incumbent entrenchment: High market concentration among top suppliers raises barriers for new entrants; therefore, differentiation through services and digital ecosystems becomes critical for challengers.
How to use this study to make decisions in 2026
-
Stage investments using scenario modeling provided in the report: map product launches and regulatory milestones to expected market-shift inflection points to prioritize R&D spend.
-
Translate vendor scorecards into partnership pipelines: use our benchmarking to identify best-fit OEM or reagent partners for joint go-to-market pilots targeted at high-value verticals.
-
Reframe commercial conversations toward life-cycle economics: position instruments not just on capex but on TCO, consumable attachment, and compliance risk reduction — the areas purchasers will value most in 2026.
Conclusion — the path forward
The Karl Fischer titrators market presents a classic strategic trade-off in 2026: stability in aggregate demand (supported by a clear historical growth path and a 5.5% CAGR projection) alongside accelerating functional disruption driven by software, reagent innovation, and regulation. Executives who prioritize modular product architectures, embed compliance-by-design, and convert consumables into recurring revenue will be best positioned to capitalize. For those ready to operationalize these insights, our full PW Consulting report contains the detailed segment matrices, vendor scorecards, and scenario models necessary to convert strategic intent into 12–36 month execution plans.
Next step
Access the full report to obtain the granular segmentation, regional and application breakdowns, and downloadable financial model that support acquisition screening, product roadmaps, and lab procurement policies. Our executive team is available to tailor a strategy session that maps the report’s findings to your organization’s priorities.
For detailed analysis of this topic, please visit the official page: Karl Fischer Titrators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


