



PW Consulting: Polyurea Coatings Market at USD 1,400M in 2025

Polyurea Coatings Market — Strategic Briefing for 2026 Corporate Decision-Making
As PW Consulting’s Chief Industry Analyst, I present a compact, strategy-focused preview of our full Polyurea Coatings Market study. The sector’s structural growth and risk profile present a clear set of strategic choices for executives planning investments, partnerships, and go-to-market pivots in 2026. This briefing synthesizes the report’s most consequential insights — enough to shape near-term decisions while reserving the detailed segment-level tables, deal pipelines, and project-level maps for subscribers to the full study.
Polyurea Coatings Market
Market snapshot: trajectory and scale
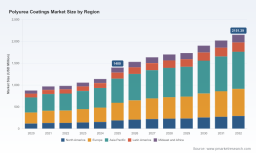
Polyurea coatings have moved from a niche high-performance material toward mainstream specification across infrastructure, industrial, and protective applications. Measured on a historical basis (2020–2025), the global market expanded from under USD 900 million to approximately USD 1.4 billion in our base year (2025). Looking forward across our forecast window (2026–2032), we model a steady compound annual growth rate of 6.33%, driving a market size north of USD 2.15 billion by 2032 under the base scenario.
Polyurea Coatings Market
That trajectory reflects a combination of accelerating adoption in high-value use-cases and incremental displacement of legacy coating technologies where lifecycle performance and regulatory compliance are decisive procurement criteria. Importantly for strategists, the market’s scale today is large enough to support specialization and global scale plays, yet concentrated enough that a small set of incumbent manufacturers and formulators continue to command meaningful share and influence.
Polyurea Coatings Market
Why this study matters for 2026 planning
- Timing of capacity and product decisions: With demand projected to grow at a mid-single-digit CAGR, capital deployment in manufacturing, application equipment, and technical service capabilities must be synchronized to avoid either stranded assets or missed share. Our report frames the optimal timing windows for capex and capacity expansion decisions across three realistic demand scenarios.
- Regulation-driven product specifications: Environmental compliance (VOC limits and lifecycle reporting) is shifting procurement toward 100% solids and low-VOC chemistries. Suppliers who pre-position low-emission product lines will find tender and project windows opening in regulated markets. The study quantifies the regulatory tailwinds and maps them to likely specification changes by buyer cohort.
- Supply chain and margin resilience: Volatility in feedstock pricing — notably isocyanates and specialty amines — is a high-probability, high-impact risk. The study offers pragmatic hedging frameworks, supplier contracting playbooks, and margin protection levers for both upstream manufacturers and downstream applicators.
- Competitive advantage playbook: We provide a decision matrix that links choice of strategic focus (vertical integration, niche premiumization, or geographic expansion) to realistic ROI timelines given current concentration and innovation dynamics.
Dynamics: forces shaping the market in 2026
- Performance economics: Buyers are increasingly valuing whole-life cost over first-cost. Polyurea’s cure speed, chemical resistance, and durability change project scheduling and maintenance economics — a factor we quantify under several asset-life assumptions.
- Environmental profile: Polyurea formulations are typically 100% solids and largely free of VOCs, a structural advantage as public-works and large private projects move toward stricter environmental specifications. Producers are also investing in solvent-free and lower-impact chemistries to align with upcoming regulation cycles.
- Raw material volatility: Fluctuating prices of isocyanates and amine resins present both a cost risk and an innovation incentive; firms that secure long-term feedstock agreements or develop alternative chemistries will enjoy asymmetric advantages.
- Concentration and customer power: Market concentration shows that a small group of suppliers capture a majority of commercial value; this creates opportunities for focused challengers to win by specialization, and for incumbents to consolidate adjacent value pools (formulation IP, application services, logistics).
Competitive landscape: what recent moves reveal
Our analysis pays close attention to a core set of market participants and their recent strategic moves — a reliable signal of where competition and margins will concentrate over the next 24 months.
- ArmorThane USA Inc. — aggressive programmatic wins: Recent contract announcements (including multiple blast mitigation awards) indicate a firm leveraging specialized performance credentials to win government and hardened-shelter projects. For competitors, the implication is clear: deep technical capabilities plus program-level relationships create high-barrier niches.
- BASF SE — capacity and sustainability bets: BASF’s capacity expansion in Asia signals a dual strategy: meet surging regional demand and advance sustainable chemistries that reduce VOCs and extend coating longevity. Big-chemical plays like this compress supply cycles and pressure smaller players to either differentiate or pursue partnering exits.
- Huntsman Corporation — product performance differentiation: Product launches touting measurable polymer performance improvements (e.g., intumescent technologies) show the market still rewards meaningful R&D-driven upgrades. Incremental performance gains translate to specification wins on projects where fire, corrosion, or longevity is mission-critical.
- Other notable players: System formulators and applicators (Sika, Covestro, Chemline, SPI, Polymer Nation) are clustering around specialization: waterproofing membranes, automotive systems, cast elastomers, and decorative/high-performance flooring. These positions highlight the two-tier market structure: platform-grade suppliers and highly focused applicators.
Taken together, incumbent moves suggest an emergent meta-strategy: verticalize where you can (formulation + application), out-innovate on sustainability and performance specs, or specialize into high-barrier niches where scale is less determinative.
What the full PW Consulting report delivers
- Validated market sizing and topline forecasts (historical analysis 2020–2025; base year 2025; forecast 2026–2032) with scenario modeling and sensitivity testing around raw material and regulatory shocks.
- Actionable go-to-market playbooks for manufacturers, applicators, and distributors — including pricing tactics, tender strategies, and installer economics.
- Comprehensive competitive profiles for leading suppliers, with M&A watchlists and a timeline of strategic moves mapped to capability gaps.
- Supply chain stress-testing and recommended contracting frameworks to mitigate isocyanate/amine price volatility and delivery risk.
- Technology roadmaps (chemistry, equipment, and integrative systems) that align R&D choices with addressable commercial value pools.
- Regulatory impact matrices that translate evolving VOC and sustainability rules into product-spec and procurement outcomes by buyer type.
Recommended 2026 executive actions
- Lock in strategic feedstock coverage: Secure multi-year or indexed supply agreements for critical intermediates; alternatively, pursue joint-ventures with chemical suppliers to share margin and risk.
- Prioritize low-VOC formulations and lifecycle claims: Move R&D and commercialization resources to formulations that deliver measurable LCA improvements — these products gain prioritized inclusion on public tenders and corporate procurement lists.
- Adopt a two-track growth approach: For scale players: pursue selective capacity expansion in geographies with near-term demand visibility. For challengers: double down on niche specialization (blast mitigation, intumescent systems, extreme-environment waterproofing) where technical differentiation yields pricing power.
- Invest in application ecosystems: Training, certified applicator networks, and bundled service models increase installed-base retention and margin capture. Our case studies quantify ROI on certification programs vs. pure product selling.
- Prepare M&A and partnership playbooks: Use 2026 as a window to acquire complementary formulation IP or regional applicator networks while valuations remain rational; our competitive concentration analysis highlights likely targets and valuation bands.
- Scenario-proof pricing: Adopt tiered pricing with raw-material pass-throughs and contractual hedges for long-duration projects; apply value-based pricing for whole-life cost propositions on large infrastructure accounts.
How to use this briefing
Treat this document as a strategic compass. If you are an executive evaluating capex, the key input is timing: align any greenfield capacity decisions with the demand scenarios in our full study to avoid overexposure to price shocks. If you are a product leader, use the regulatory and lifecycle insights to prioritize formulations that will be specified in tomorrow’s tenders. For M&A strategists, the competitive concentration and company profiles identify realistic acquisition corridors and partnership candidates.
PW Consulting’s full Polyurea Coatings Market report contains the underlying data tables, segmented forecasts, buyer-level procurement maps, and the transaction-ready annexes that operational teams need to execute on these recommendations. The critical, segment-level intelligence (regional and application split tables, project-level contract pipelines, and supplier cost models) are intentionally withheld from this preview to preserve competitive value and are available via our report portal.
Concluding perspective
In 2026, polyurea coatings represent a strategic growth corridor for materials and service companies that can move beyond commodity competition to offer demonstrable whole-life value and compliance certainty. The market is large enough, growing predictably, and concentrated in a way that makes both focused challenger plays and scale consolidation attractive. Executives who convert the insights above into concrete sourcing, product, and M&A moves this year will be well positioned for the next expansion phase through 2032.
For immediate access to the full dataset, segmented forecasts, and the playbooks described here, consult PW Consulting’s Polyurea Coatings Market report page or contact your PW Consulting account director.
For detailed analysis of this topic, please visit the official page: Polyurea Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


