



PW Consulting: Dairy Packaging Market to Hit USD 33.17 Billion by 2032 at 4.89% CAGR

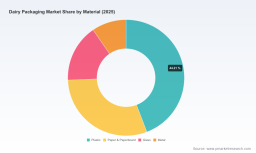
Dairy Packaging Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise yet substantive preview of our new Dairy Packaging Market study. Built on a 2025 base with historical coverage from 2020–2025 and forward-looking forecasts to 2032, the report synthesizes macro-scale market sizing, competitive positioning, regulatory dynamics, and executable playbooks that procurement, R&D, commercial and M&A teams will use to make higher-confidence decisions in 2026.
Dairy Packaging Market
Macro snapshot (what the numbers tell you)
The dairy packaging universe is expanding steadily. Our topline market model tracks growth from an estimated USD 18.48 Billion in 2020 to USD 23.68 Billion in 2025, and projects a progression to roughly USD 33.17 Billion by 2032. The modeled compound annual growth rate across the 2026–2032 forecast window is 4.89%. These figures reflect secular demand for refrigerated and ambient dairy formats, product line extensions (including plant-based dairy analogues), and ongoing investment in packaging innovations that preserve shelf life while responding to sustainability imperatives.
Dairy Packaging Market
Why this study matters for decisions you must take in 2026
- Regulatory inflection points: Between regional mandates for minimum recycled content and producer-responsibility regimes, packaging specifications that were once commercial choices are rapidly becoming compliance requirements. Examples include state-level recycled content mandates that escalate through the decade and major frameworks that took effect across jurisdictions beginning in 2025–2026.
- Technology and material shifts: Aseptic and barrier innovations are enabling new distribution models for dairy and dairy-alternative beverages. Simultaneously, suppliers are rolling out alu-free, paper-based barriers and higher-recycled-content polymers — forcing choices about capital allocation, supplier partnerships, and speed-to-market of reformulated packaging solutions.
- Market structure and competitive tension: The market exhibits measured concentration; top-three and top-five firm shares indicate room for both scale players and focused specialists. That profile rewards disciplined M&A and partnership plays as much as operational excellence.
What’s inside the PW Consulting study (practical, operational content)
This is a hands-on toolkit for executives deciding where to invest and how to adapt in 2026. Key deliverables include:
Dairy Packaging Market
- Topline market model and transparent forecast engine (2026–2032) with sensitivity scenarios for raw-material inflation, recycled-content premiums, and accelerated sustainability mandates.
- Supply-chain and capability maps that identify upstream resin and board suppliers, midstream converters, and downstream filler and retail bottlenecks — with decision trees for near-term mitigation of capacity constraints.
- Material transition playbooks that quantify the trade-offs between barrier performance, recyclability, cost-to-serve, and product shelf-life (presented as scenario outputs rather than raw proprietary splits).
- Commercial playbooks for brand owners: pricing levers, packaging-led premium strategies, and retailer negotiation scripts for pass-through of recycled-content costs.
- Regulatory compliance matrices and an actionable timeline for jurisdictions enacting recycled-content and EPR rules — enabling a prioritized compliance roadmap for 2026.
- Acquisition and partnership screening frameworks: target profiles, valuation sensitivities, and integration risk checklists calibrated to current market concentration.
- Operational pilot templates: full lifecycle from lab-scale barrier validation to commercial line trials and retailer acceptance testing — with KPI dashboards for testing success.
Competitive landscape — the players shaping 2026 outcomes
Our competitive analysis focuses on the incumbents and fast-movers whose strategies will define 2026–2028 momentum. Rather than a directory, the study diagnoses strategic intent and tactical levers for each major cohort.
- Tetra Pak — Continues to push paper-based barrier systems into higher-throughput aseptic lines. Their strategy plays to customers seeking a credible pathway from plastic to renewable-fiber-based formats without sacrificing aseptic performance. Expect continued investments in line compatibility and co-development programs with dairy brand partners.
- SIG Combibloc Group (SIG) — Expanding aseptic carton innovations and localized product introductions. Recent first deployments of alu-free full-barrier cartons underscore a push for differentiated offerings that reduce aluminium dependency while maintaining shelf life — a direct response to retailer and regulatory pressures.
- Elopak — Scaling sustainable carton capacity in key markets. Facility launches and regional manufacturing footprints align with a play to capture retail demand for fiber-based cartons, particularly where supply chains favor shorter lead times and regional sourcing.
- Amcor, Berry Global, Huhtamaki, Winpak, ProAmpac — These converters and flexible-pack specialists are sharpening their value propositions around lightweighting, recyclability, and specialty film performance for dairy applications. Look for product launches that target butter wraps, tubs, and spouted pouches with improved recyclability attributes.
- Material suppliers (SABIC, INEOS/Styrolution) — Resins and bio-attributed polymers are central to compliance and cost. Their roadmaps for recycled-content grades and bio-attributed offerings will directly determine the marginal economics of many conversion projects.
- Specialized PET and closure players (e.g., Alfipa) — Focused on bottle and closure innovations to support yogurt and drinking-yogurt formats; niche capability here can command premium margins in differentiation-led product launches.
Recent market moves — facility launches, product introductions, and pilot partnerships — demonstrate two concurrent trends: incumbents are defending share by broadening sustainable portfolios; nimble specialists are exploiting segment-specific gaps (e.g., butter wraps, sour-cream cups with recycled polymers). This concurrent action creates windows for both consolidation and targeted organic growth.
Regulatory landscape — a non-negotiable element of 2026 planning
- States and national frameworks enacted or entering enforcement in 2025–2026 are raising the bar on minimum recycled content and establishing producer responsibility for packaging flows. These are not optional commercial features; they will be table stakes in procurement specifications and tender evaluations.
- Timelines for compliance are material to capital planning. Requirements that escalate over the next decade mandate early supplier engagement, pilot programs for recycled-content grades, and revised contractual terms to shore up performance guarantees.
Priority actions for 2026 — a distilled playbook
- Immediate (0–6 months): Run a regulatory-gap analysis tied to your SKUs and top-3 markets; launch supplier dialogues to qualify recycled-content resin and fiber grades; initiate one rapid pilot on a high-volume SKU to validate recyclability claims with retail partners.
- Medium term (6–18 months): Build cost-to-serve models that internalize recycled-content premiums and potential EPR fees; hardwire sustainable-material clauses into procurement contracts; deploy packaging pilots with measurable shelf-life and returns-rate metrics.
- Strategic (18–36 months): Evaluate bolt-on acquisitions for converters with sustainable-capability IP or regional carton capacity; consider co-investment in barrier-line upgrades with converters to secure capacity; pursue differentiated packaging that enables premium pricing (e.g., convenience closures, on-pack consumer communication about circularity).
How the report will change what you do
Clients who use this study gain three advantages: a calibrated market size and growth trajectory to support capital-allocation decisions; a tested set of implementation templates that reduce time-to-market for material transitions; and a competitive scoreboard that signals where competitors will attempt to capture share. The analysis is intentionally prescriptive: it doesn’t stop at what is happening — it tells you how to act, how to measure pilot success, and how to de-risk full-scale deployment.
Market concentration and strategic consequence
Measured concentration metrics show that the category has meaningful lead players but is not so consolidated as to bar entry for focused specialists or large strategic entrants. This structure favors selective consolidation, targeted partnerships between brand owners and converters, and the creation of differentiated, sustainability-led offers.
Closing — what to do next
If your 2026 planning cycle includes packaging spend, supplier strategy, or capital allocation to processing and filling lines, this study is designed as a decision-grade input. It provides the models, regulatory calendars, supplier diagnostics, and pilot templates you will need to move from strategy to execution during a period of rapid regulatory and material change.
For complete regional and application-level segmentation, proprietary scenario outputs, and downloadable pilot templates and ROI calculators, consult the full PW Consulting Dairy Packaging Market report. Our clients use the granular companion data to build board-ready investment cases and to accelerate compliance and go-to-market timelines with measurable KPIs.
For detailed analysis of this topic, please visit the official page: Dairy Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


