



PW Consulting: Color Coated Steel Market to Reach USD 330.71 Million by 2032

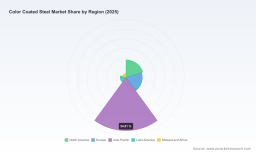
Color Coated Steel Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused executive preview of our 2026 Color Coated Steel Market study. This briefing synthesizes the research’s strategic value for corporate leaders preparing decisions in 2026 — from sourcing and capital investment to product positioning and M&A. The commentary demonstrates the analytical depth behind the full report while intentionally withholding granular segment-level figures to encourage direct access to the source for transaction-ready detail.
Color Coated Steel Market
Why this research matters in 2026
Color coated steel remains a structurally important, medium-growth specialty within the broader steel complex. Our base-year alignment (2025) and historical window (2020–2025) frame a market that has recovered from pandemic-era dislocations and is now subject to structural policy and supply-chain shifts. Under the forecast horizon (2026–2032), PW Consulting models the market to grow at a compound annual growth rate (CAGR) of 4.86%, with clear inflection points driven by trade policy, carbon regulation, and material-cost volatility.
Color Coated Steel Market
For executives, this means three actionable realities in 2026: (1) stable expansion at a modest CAGR creates opportunities for incremental capacity and product premiumization rather than runaway volume growth; (2) policy shocks materially reprice supply chains and must be modeled explicitly in procurement and pricing scenarios; and (3) the market’s moderate concentration profile creates space for targeted consolidation and niche specialization.
Color Coated Steel Market
Market trajectory and what the headline numbers tell you
-
Historical trajectory: The market has expanded consistently from the start of the decade through 2025, reflecting demand recovery in construction, aftermarket, and industrial segments.
-
Base year and forecast framing: Using 2025 as the analytical base, our forecast through 2032 captures both near-term policy shocks and medium-term structural trends, culminating in a materially larger market by the end of the period under the central scenario.
-
Concentration and competition: Market concentration metrics show the top three and top five players control a majority of industry volumes, signaling that scale advantages still matter — especially for integrated producers and full-service processors.
Key dynamics shaping 2026 decisions
-
Trade and tariffs: 2025–2026 saw significant policy interventions — notably increased US Section 232 steel tariffs and newly instituted anti-dumping measures in select export markets. These measures alter landed costs and create immediate windows for domestic processors and regional champions to capture incremental share.
-
Carbon regulation: The EU’s Carbon Border Adjustment Mechanism (CBAM) is now operational for iron and steel, which imposes a carbon cost on imports and shifts competitiveness toward lower-emission domestic or certified suppliers. Buyers and exporters must recalibrate supplier scorecards to include embodied carbon and compliance pathways.
-
Coating and chemical compliance: Regulatory regimes in major markets are raising the bar on formulation (e.g., chromate-free, ultra-low-VOC). Compliance is no longer a cost-center checkbox but a product differentiator, affecting coating lines, capital expenditures, and product claims.
-
Input cost sensitivity: Zinc galvanizing — the anti-corrosion backbone of many color coated systems — represents a meaningful share of production cost and is exposed to LME pricing swings. Procurement optimization and hedging strategies for zinc can materially protect margins.
Competitive landscape — how players are positioning
Our competitive analysis segments players into three archetypes relevant for corporate strategy:
-
Integrated steel champions: Large integrated producers with in-house coating lines are leveraging scale, integrated logistics, and certification breadth to serve global OEM and construction chains. These firms can absorb regulatory cost shocks more easily and monetize lower carbon-intensity product lines.
-
Regional specialists and processors: North American processors and merchant-coaters position on speed-to-market, customization (color, emboss, thickness), and service (cut-to-length, just-in-time supply). Their proximity to end-markets and flexible lot sizes are competitive advantages where tariffs and logistics matter.
-
High-volume exporters and contract manufacturers: Producers in cost-advantaged regions pursue volume contracts and competitive pricing for large roofing and construction programs. Trade measures in importing countries can rapidly curtail access to these channels, forcing exporters to accelerate certification and cost-pass-through strategies.
Representative company profiles examined in the report include a cross-section of the industry: experienced US processors and merchant-coaters with service differentiation; Indian integrated mills and large capacity exporters; and Asian producers combining production scale with export orientation. The full report evaluates each firm on supply footprint, coating technologies, certification status, commercial channels, capital intensity, and strategic mobility under tariff and carbon regimes.
Recent policy events and immediate implications
-
Section 232 escalation (US): The doubling of steel tariffs repositions domestic supply economics and provides a clearer short-term rationale for local processing investment and inventory holding. Import-reliant buyers face a decision: accept higher landed costs, re-source to domestic processors, or pursue tariff mitigation through trade remedies and exemptions.
-
Anti-dumping measures in select markets: Definitive duties on imports from certain origins create transient demand shifts and can catalyze regional sourcing pivots. Exporters must prepare legal and commercial responses, and buyers should run scenario-impact analysis for supplier continuity.
-
CBAM activation (EU): Importers now face embedded-carbon accounting. Firms that can document lower scope-1 and scope-2 emissions — or who invest in decarbonization pathways — enjoy a competitive advantage. Carbon exposure must be translated into price and contract terms.
What the full PW Consulting report delivers (practical and transaction-ready)
-
State-of-play market sizing and validated forecasts (2026–2032) with scenario overlays for tariff, carbon, and raw-material stress tests.
-
Supply-chain heat maps and destination flows that identify substitution risks and nearshoring opportunities (note: full regional and application splits are included in the report; summary here omits granular figures).
-
Supplier scorecards and a shortlist of acquisition targets and strategic partners across tiers with compatibility matrices for technology, geographic reach, and compliance readiness.
-
Pricing and margin models that incorporate LME zinc dynamics, coating formulation differentials, and applied tariff regimes — enabling CFOs to run “what-if” profitability scenarios.
-
Capex and retrofit playbooks for coating lines — covering investment sizing, lead times, and expected ROI under multiple demand cases.
Strategic recommendations for 2026 decision cycles
-
Prioritize supplier carbon transparency: Incorporate embodied-carbon criteria into procurement RFPs and tier-one supplier agreements to limit CBAM exposure and to unlock preferential access to low-carbon buyers.
-
Hedge zinc exposure and model tariff pass-through: Establish hedging frameworks and dynamic pricing clauses tied to clear indices so that margin erosion from raw-material and tariff swings is predictable.
-
Consider selective nearshoring or regional capacity investments: Where trade barriers have raised landed costs materially, small-to-medium sized coating lines or toll-coating partnerships can deliver service continuity and margin protection.
-
Invest in compliant coating platforms: Transitioning to chromate-free and ultra-low-VOC topcoats is both regulatory compliance and a route to premium positioning — particularly for façade, architectural, and appliance customers.
-
Use M&A to acquire capabilities, not just capacity: Target deals that bring certification capabilities, low-carbon energy inputs, or proprietary coating chemistries rather than only incremental tonnage.
How to use the report in your 2026 planning
Corporate planners, procurement executives, and business-development teams should use this study as the analytical backbone for three immediate deliverables in 2026: (1) a supplier-risk remediation plan that integrates tariff and carbon scenarios; (2) a 24-month capex and retrofit prioritization with clear ROI thresholds; and (3) a strategic M&A shortlist informed by competitive benchmarks and regulatory exposure maps.
PW Consulting’s full report contains the granular regional and application breakdowns, unit economics, and company-level scorecards needed to operationalize these actions. This preview has signaled the report’s analytical rigor and direct applicability to 2026 decisions while withholding the detailed segment tables and monetary breakdowns that are provided in the full publication.
Next steps
Clients ready to translate these insights into tactical plans can request the full dataset, supplier scorecards, and scenario models via the report landing page. For bespoke strategy sessions, PW Consulting offers workshop modules that convert the market forecast and policy scenarios into procurement contracts, capex plans, and M&A roadmaps tailored to your portfolio.
For detailed analysis of this topic, please visit the official page: Color Coated Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


