



PW Consulting: Benzaldehyde Market poised at USD 325M in 2025

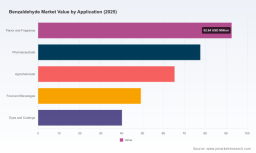
Benzaldehyde Market — Strategic Preview for 2026 Decision-Making
Executive snapshot
As companies recalibrate their product portfolios and supply chains for a post‑pandemic, geopolitically complex industrial landscape, benzaldehyde is re-emerging as a strategically relevant intermediate across flavors & fragrances, pharmaceuticals, agrochemicals and specialty chemicals. Our PW Consulting Benzaldehyde Market study (base year 2025, historical 2020–2025, forecast 2026–2032) models a steady continuation of growth driven by steady end‑market demand and evolving regulatory and feedstock dynamics. Key macro outputs from our analysis frame that trajectory: the market expanded through 2020–2025 and reached an estimated USD 325 Million in 2025, with a modeled Compound Annual Growth Rate (CAGR) of approximately 5.0% into the forecast window. By 2032, the market size is projected to reach the mid‑hundreds of USD Million, reflecting both demand resilience and pockets of premiumization in high‑purity grades.
Benzaldehyde Market
Why this matters for 2026 decisions
-
Investment timing: capital projects and brownfield expansions announced or considered in 2026 must be assessed against a predictable, single‑digit CAGR rather than a boom scenario — implying that returns hinge on efficiency, product mix premium capture, and feedstock cost management.
Benzaldehyde Market -
Portfolio prioritization: manufacturers and downstream formulators should determine whether to prioritize conventional technical grades or to move up the chain into FCC/high‑purity offerings where value per metric ton and regulatory hurdles differ markedly.
Benzaldehyde Market -
Supply chain resilience: the interplay between toluene feedstock volatility and concentrated production footprints creates both procurement risk and arbitrage opportunities for agile players.
Market trajectory — what the numbers mean (high level)
Our modeled historical series shows consistent growth through 2020–2025, culminating in the 2025 estimate of USD 325 Million (USD, Million). Under a baseline scenario we assume a steady 5.0% CAGR into 2032, producing a market size materially larger by the end of the forecast. This trajectory should be read as confirmation of a mature specialty chemical market: growth is reliable, but not explosive. That profile favors strategic moves that optimize margin per ton — product differentiation, downstream integration, and cost leadership — over pure volume plays.
Competitive landscape and strategic positions
The benzaldehyde value pool remains oligopolistic with a handful of established producers operating across distinct geographies and technology routes. Market concentration metrics indicate that top-tier groups collectively control a substantial share of global capacity, leaving space for regional specialists and export‑oriented manufacturers to serve niche demand corridors. Key industry participants we profile in the study include legacy chemical producers, aroma‑specialists and vertically integrated regional players.
-
Large chemical producers with multi‑site assets provide scale and diversified feedstock sourcing; their strategic advantage is reliability of supply for industrial intermediates and capacity to serve large industrial customers.
-
Aroma and flavor specialists focus on high‑purity grades and regulatory compliance. Their value proposition is technical service, traceability, and rapid qualification for sensitive applications in food and pharma.
-
Regional manufacturers and exporters play to cost and logistics advantages, offering competitive entry points into price‑sensitive markets and supplementing global supply during tightness.
Our company profiles examine manufacturing routes, grade portfolios, and commercial strategies. Recent industry movement — such as the commissioning of new chlorotoluene‑route capacity by a major Indian producer with first dispatches in mid‑2025 — underlines that new capacity is already entering the market and will affect regional flows and pricing dynamics into 2026.
Dynamics and risk matrix
To craft robust strategies for 2026, executives must consider five interlinked dynamics we explore in depth:
-
Feedstock volatility: toluene remains the primary economic driver. Spot price ranges witnessed in recent periods create quarter‑to‑quarter margin variability. Our sensitivity tables demonstrate that modest swings in toluene pricing materially alter cash margins for different process routes.
-
Regulatory trajectory: benzaldehyde has been flagged in recent regulatory review programs for potential concerns under wide dispersive use and consumer exposure. Anticipate increased registration and potential use restrictions in certain jurisdictions. This will increase compliance costs and extend lead times for product qualification in consumer‑facing applications.
-
Concentration and customer bargaining power: a concentrated supply base magnifies the influence of individual capacity changes on availability and commercial terms, while large buyers in flavors, pharma and agrochemicals continue to extract stringent quality and lifecycle documentation requirements.
-
Trade and tariff stability: tariff lines for benzaldehyde have remained stable in major jurisdictions in the near term, but non‑tariff measures and origin rules are a growing feature in procurement contracts and can affect landed costs.
-
Innovation and downstream substitution: formulation shifts, bio‑based alternatives and shifts in fragrance trends can change volume dynamics for specific grades; our report maps plausible substitution scenarios and their impact on grade mix investment economics.
Practical content of the full report (what executives will get)
We designed the report as an operational toolkit for 2026 decision cycles. Highlights include:
-
Demand and price modeling: an integrated demand model spanning 2020–2032 with baseline, upside and downside scenarios to stress test investment returns.
-
Cost benchmarking: plant‑level cash cost curves by dominant technology routes, sensitivity to toluene and utilities, and break‑even metrics for greenfield versus retrofit projects.
-
Commercial playbook: go‑to‑market options for producers and distributors — premiumization, tolling agreements, long‑term off‑take structures, and blue‑chip qualification matrices for pharma and F&F sectors.
-
Regulatory action plan: jurisdiction‑specific compliance checklists, anticipated timelines for substance evaluation outcomes, and practical mitigation levers (formulation pivots, restricted‑use labeling, insurance and indemnity strategies).
-
Competitive dossiers: actionable profiles of incumbent suppliers, manufacturing footprints, technology choices, and a matrix of strategic moves (capacity additions, M&A targets, JV potential).
-
Deal structuring annex: valuation multiples observed in recent specialty chemical transactions, earn‑out structures tailored to regulatory risk, and sample term sheets for strategic partnerships.
We intentionally avoid reproducing granular segmentation tables in this preview; the full dataset — including region and application split forecasts, price series and downloadable cost curves — is available via the full report portal for subscribers.
Strategic recommendations for 2026
-
For producers considering capacity moves: favor staged capacity increases and modular brownfield upgrades over large greenfield projects. The market’s single‑digit CAGR supports incremental expansion tied to secured offtake and feedstock hedges.
-
For margin improvement: pursue grade differentiation. High‑purity grades for pharma and F&F command premium risk‑adjusted returns when paired with robust regulatory support and traceability systems.
-
For procurement and trading desks: use the market’s concentrated supply dynamics to negotiate hybrid contracts (fixed base volumes plus index‑linked swing volumes). Build optionality around toluene sourcing and consider hedging strategies timed to capital and inventory cycles.
-
For downstream users: accelerate supplier qualification and dual‑sourcing plans now. Regulatory reviews and episodic feedstock volatility can create short‑term dislocations that disadvantage single‑sourced supply chains.
-
For M&A and partnership seekers: prioritize targets that offer either access to high‑purity grades, proprietary downstream channels, or regional logistics advantages that reduce landed costs in strategic markets.
Scenario lens — three plausible 2026 landscapes
-
Baseline: continued low‑single‑digit growth with manageable feedstock cycles — incumbents optimize margins and regional trade flows stabilize.
-
Price‑up shock: sustained toluene price escalation triggers cost pass‑through and narrows margins for commodity grades; selectively positioned high‑purity suppliers gain market share.
-
Regulatory tightening: restrictive classifications or additional controls in major jurisdictions lengthen qualification timelines and raise compliance costs, favoring larger producers with regulatory and documentation capabilities.
Final note — how to use this preview
This preview is designed to crystallize the strategic choices facing senior executives in 2026: invest for scale or invest for specialty; hedge feedstock risk or lock in long‑term supply; qualify new suppliers or secure incumbent relationships. PW Consulting’s full Benzaldehyde Market study provides the complete numerical appendix, segmentation matrices and actionable templates referenced above. For teams writing business cases, negotiating offtake contracts, or sizing investments, accessing the full dataset will materially shorten decision cycles and reduce execution risk.
Next steps
-
Request the full report to access the region‑ and application‑level forecasts, downloadable cost curves, and supplier scorecards referenced in this preview.
-
Book a strategic briefing with our industry team to translate the scenarios into a tailored playbook for your firm’s 2026 capital and commercial planning.
For detailed analysis of this topic, please visit the official page: Benzaldehyde Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


