



PW Consulting: SHMP Market to Reach USD 975.93M by 2032 at 4.45% CAGR

Strategic Preview: Sodium Hexametaphosphate (SHMP) Market — A 2026 Decision Playbook
As organizations plan capital, procurement and go-to-market moves for 2026, clarity on the trajectory of specialty phosphate markets is non‑negotiable. This preview distills the strategic value of PW Consulting’s full Sodium Hexametaphosphate (SHMP) Market study — highlighting the analytic rigor and practical tools executives will need, while preserving the granular segment intelligence that warrants direct access to the report.
Sodium Hexametaphosphate (SHMP) Market
Market snapshot: trajectory and growth expectations
SHMP has been on a steady expansion path through the early 2020s. Using 2025 as the base year, PW Consulting’s modeled time series shows a market that rose from roughly USD 575 million in 2020 to about USD 717 million in 2025. Our forecast period (2026–2032) assumes a compound annual growth rate (CAGR) of 4.45%, producing a continuation of growth into the next decade driven by demand resilience across water treatment, food & beverage, detergents, pulp & paper and industrial applications.
Sodium Hexametaphosphate (SHMP) Market
Two takeaways for decision-makers: (1) the market is large enough to justify targeted capital deployment, and (2) growth is steady rather than explosive — which places a premium on operational efficiency, feedstock management and selective product differentiation rather than broad, high‑risk expansion.
Sodium Hexametaphosphate (SHMP) Market
What the full report supplies — practical, transaction‑ready intelligence
- Executive Summary and 360° Market Map — accessible, board‑level framing of demand drivers, risk vectors and strategic levers for 2026.
- Proprietary Demand Model — bottom‑up forecasts by application and region calibrated to macro indicators, with sensitivity toggles for key variables (economic growth, municipal wastewater policy, industrial output).
- Cost‑and‑Price Simulator — dynamic margins model that links phosphoric acid and phosphate‑rock feedstock pricing to output costs and recommended pricing bands.
- Supply Landscape and Capacity Tracker — facility-level coverage of global producers, recent capex and near‑term commissioning events (including dedicated units and debottlenecking projects).
- Regulatory Impact Matrix — scenario analysis of tightening nutrient limits, trade measures and product‑use restrictions, with quantified impact vectors for producers and large end‑users.
- Commercial Playbooks — procurement negotiating levers, inventory strategies, contract templates and indexation approaches for buyers and distributors.
- M&A & Partnership Heatmap — acquisition targets, JV opportunities and likely consolidation corridors informed by concentration metrics and strategic positioning.
Competitive landscape: what incumbents and challengers are doing
The SHMP market shows a moderate concentration profile — sufficient scale among the leaders to influence trade flows, but with room for nimble, regionally focused players. PW Consulting’s CR3 and CR5 metrics confirm a market where the top three and top five firms exert influence without creating a tight oligopoly; this dynamic fosters both competition and selective consolidation.
- Prayon S.A. (Engis, Belgium) — Strategic capital investment is a clear signal. The company inaugurated a new 10,000 tpa SHMP unit in Engis in November 2025 (a roughly €30 million project), doubling dedicated capacity at that site. That move underscores a European push to secure local, food‑grade and technical grade supply in close proximity to downstream customers and to reduce import dependency.
- Hubei Xingfa Chemicals Group — As an integrated phosphate producer, Xingfa’s vertical footprint supports competitive feedstock sourcing and export capability. Their position highlights the trade‑flow tension between integrated Chinese producers and markets under import restriction regimes.
- Innophos Holdings — A North American specialty phosphate leader with integrated polyphosphate lines. Innophos exemplifies the value of product breadth and technical service in retaining food and water‑treatment customers where specifications and regulatory compliance matter.
- ICL Performance Products — Focused on condensed phosphates for industrial, mining and dispersant roles. ICL’s playbook highlights the importance of technical sales and application engineering where SHMP functions as a performance additive.
- Aditya Birla Chemicals — Regional manufacturing footprint in India supports both domestic demand and export strategies. Their presence signals the competition between low‑cost regional producers and higher‑spec suppliers in developed markets.
Collectively, these players illustrate a market where strategic moves — capacity expansions, integration, technical service differentiation and selective geographic positioning — determine advantages more than scale alone.
Regulatory & trade dynamics: near‑term pressure points
- Environmental tightening: Recent revisions to wastewater directives in the EU and intensified U.S. EPA nutrient controls are raising compliance costs and shifting demand profiles. Stricter phosphate discharge thresholds are accelerating substitution risk in developed markets and elevating the value of lower‑discharge formulations and application support.
- Trade measures: Section 301 tariffs remain a live factor in North American trade flows, creating a 25% ad valorem headwind for some Chinese‑origin shipments. That distortion is prompting near‑market capacity additions and reshaping sourcing strategies.
- Feedstock volatility: Phosphoric acid and phosphate rock price swings are the principal margin lever. Producers with integrated upstream access or effective hedging strategies will protect margins in the face of spikes; others face margin compression or must pass cost through to buyers.
Supply, pricing and substitution risk — why procurement must change in 2026
For buyers and manufacturers, three structural realities should inform 2026 procurement strategies:
- Indexation and hedging become core. Given input volatility, long‑term contracts with cost‑pass‑through mechanisms or feedstock‑linked indexation will reduce earnings volatility for producers and cost surprises for large buyers.
- Localisation premiums are real. Tariffs and logistics costs make near‑market supply and strategic inventory hubs more attractive despite higher unit costs in some cases.
- Technical service and formulation support can offset substitution. Where environmental limits create substitution pressure, suppliers that couple product grades with application engineering and compliance documentation will retain share.
Three strategic scenarios for boardrooms to stress‑test
- Base case (reference) — Market grows in line with the 4.45% CAGR assumption. Incremental capacity is absorbed; pricing follows feedstock direction with moderate margin recovery for well‑positioned producers.
- Regulatory‑tight scenario — Faster tightening of wastewater phosphorus limits accelerates demand for alternative sequestrants and higher‑spec SHMP grades; winners will be suppliers that offer documented environmental performance and technical support, while commodity positions face erosion in developed markets.
- Supply‑shock scenario — Sharp phosphoric acid or logistics cost spikes compress suppliers without integration; this produces short‑term dislocations, spot‑market premiums and an accelerated push for upstream integration or offtake partnerships.
Strategic actions for 2026 — priority playbook
- Producers: Prioritize feedstock security (vertical integration, strategic offtake) and differentiate via technical services. Delay broad greenfield capex unless returns are robust under conservative feedstock price scenarios.
- Buyers/Distributors: Move to tiered contracts — combine short‑term agility with partial index‑linked longer‑term volumes to hedge price and availability risk. Build supplier scorecards that weight regulatory compliance and application support higher.
- Investors/M&A: Target bolt‑on assets that fill geographic gaps or add technical service capabilities. Distress or consolidation opportunities may emerge under supply‑shock assumptions; focus diligence on feedstock exposure and contract mix.
- Regulators & NGOs: Expect friction points between environmental goals and supply stability. Early engagement with producers on realistic phase‑in periods for new limits reduces unintended supply shocks.
Why PW Consulting’s full study matters to your 2026 choices
This preview lays out the strategic contours. The full study equips decision-makers with the granular inputs and interactive tools to act: facility-level capacity analytics, application‑by‑application addressable market breakdowns, supplier scorecards and an editable pricing/margin model calibrated to our dataset. Those elements transform the directional insights above into executable plans — procurement contracts, capex timing, target lists and regulatory lobbying strategies.
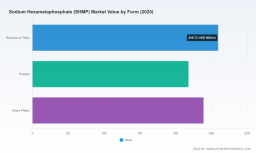
We intentionally withheld the granular segment and regional shares in this preview to preserve the unique, actionable value of the proprietary splits and scenario outputs contained in the full report. Executives who require transaction-ready charts, downloadable models and a tailored briefing for internal stakeholders should consult the full report and request a 1:1 strategy session with PW Consulting’s SHMP practice.
Next steps
- Request the full SHMP market study for access to the detailed application and regional breakdowns, supplier scorecards and the interactive cost/pricing simulator.
- Book a tailored 90‑minute briefing to align your 2026 procurement, investment or product‑portfolio plan with our scenarios and to stress‑test proposed capex decisions under multiple regulatory and supply outcomes.
In markets defined by steady growth but high upstream volatility and regulatory pressure, competitive advantage is created by superior intelligence and disciplined execution. PW Consulting’s SHMP Market study is designed to be the operating manual for those who want to convert 2026 uncertainty into opportunistic, defensible moves.
For detailed analysis of this topic, please visit the official page: Sodium Hexametaphosphate (SHMP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


