



PW Consulting: Spirometer market to reach USD 1,056M by 2032 at 6.63% CAGR

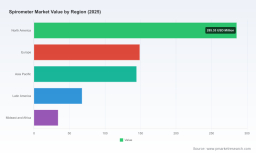
Spirometer Market 2026: Strategic Imperatives for Decision‑Makers
As healthcare providers, device OEMs, investors and policy teams calibrate strategy for the coming planning cycle, spirometry occupies an outsized role in respiratory care, occupational surveillance and primary‑care chronic disease management. PW Consulting’s Spirometer Market research (base year 2025; historical series 2020–2025; forecast 2026–2032) synthesizes clinical, commercial and regulatory vectors into an actionable playbook. At the market level, the sector demonstrated steady expansion from USD 450 Million in 2020 to USD 680 Million in 2025 and — under our core scenario — is projected to reach roughly USD 1,056 Million by 2032, reflecting a 6.63% CAGR over the 2026–2032 forecast window. These headline dynamics matter for capital allocation, product roadmaps and market access strategies in 2026 and beyond.
Spirometer Market
Why this market matters in 2026
-
Clinical prevalence and screening imperative: Rising burden of chronic respiratory disease, renewed focus on early detection (COPD, asthma) and expanded occupational surveillance programs are keeping spirometry central to diagnostic pathways.
Spirometer Market -
Digital transformation in pulmonary diagnostics: Convergence of portable hardware, embedded software, and cloud connectivity is enabling new care models — home monitoring, hub‑and‑spoke primary care diagnostics and integrated occupational health reporting.
Spirometer Market -
Regulatory and payer inflection points: Standards for electronic data transfer, laboratory compliance and reimbursement policy shifts are creating winners and losers almost overnight; compliance with program standards is now a table‑stakes commercial capability.
Market trajectory and structural takeaways
The sector’s move from a mid‑single‑hundred million market in 2020 to a high‑six‑hundred million base in 2025 reflects both product replacement cycles and demand expansion into outpatient and home health settings. Our forecast — which models a 6.63% CAGR across 2026–2032 — captures continued adoption of connected devices, an expanding installed base in emerging markets and accelerated consumables/recurring revenue streams as screening programs scale. The market concentration is meaningful but not monopolistic: the three largest firms account for under half of total revenues (CR3 ~45.6%), and the five leading suppliers control roughly 62.8%, leaving room for focused challengers, niche specialists and fast‑moving startups to carve out differentiated positions.
Regulation, reimbursement and programmatic constraints
-
NIOSH and occupational surveillance: By May 2026, only a subset of spirometer manufacturers meet the National Institute for Occupational Safety and Health (NIOSH) requirements for electronic data transfer to the Coal Workers’ Health Surveillance Program (CWHSP). The companies currently compliant include Benson, Depisteo, MGC Diagnostics, ndd Medical Technologies, Vitalograph and Vyaire Medical. For vendors targeting occupational health contracts, NIOSH compatibility is a non‑negotiable procurement filter.
-
Accessibility and device ergonomics: Recent product approvals and compliance milestones (for example, examination equipment achieving US Access Board standards) are altering procurement specifications for ambulatory clinics and community health centers. Accessibility compliance is increasingly written into purchase orders and certification checklists.
-
Payer economics: Reimbursement for spirometry remains modest on a per‑test basis (U.S. Medicare Physician Fee Schedule average reimbursement for spirometry testing, CPT 94060, is USD 38.97 per test as of January 2026). That unit price underscores why vendors are pursuing recurring revenue via consumables, software subscriptions and integrated diagnostic bundles rather than relying on hardware margins alone.
Competitive landscape — practical implications
Our competitive assessment maps incumbent strengths and near‑term moves by the market’s core vendors. This is a synthesis designed to guide negotiation, partner selection and R&D prioritization; the full benchmarking matrices and scorecards are available in the report.
-
ndd Medical Technologies (Switzerland) — Established reputation for precision portable and PC‑based systems (EasyOne series) and strong software integration (EasyOne Connect). Ndd’s NIOSH‑approved data transfer capabilities make it a preferred vendor for occupational health programs and a benchmark for interoperability features.
-
MIR – Medical International Research (Italy) — A global leader in smartphone‑compatible spirometers and oximeters, notable for rapid market reach (100+ countries) and regulatory coverage (FDA/CE). Their mobile‑first product strategy makes them a potent competitor in consumer‑facing and point‑of‑care segments.
-
Vitalograph (United States) — Strong compliance with ATS/ERS standards and proprietary V‑Core desktop/handheld platforms position Vitalograph well in clinical and diagnostic lab settings. Their focus on clinical accuracy supports premium pricing and institutional adoption.
-
MGC Diagnostics (United States) — Strength in PC‑based systems and clinical workflow software (Platinum Elite, Ultima series with BreezeSuite) makes MGC a go‑to for hospital respiratory labs and integrated pulmonary function testing suites.
-
Vyaire Medical (United States) — With Vyntus and Masterscreen lines, Vyaire is engineering‑led and hospital‑oriented, competing on integration with broader cardiopulmonary diagnostic ecosystems.
-
Midmark Corporation, Jones Medical, COSMED, Depisteo and regional specialists — Midmark and Jones Medical command strength in ambulatory and ambulatory care integration (IQmanager), with Midmark also achieving recent regulatory accessibility milestones. COSMED and Depisteo are notable for portable and metabolic‑capable instruments, and regional specialists deliver strong service coverage and aftermarket support in their markets.
Recent industry events underscore the pace of product and solution innovation. Midmark released a new digital spirometer targeted at ambulatory care clinics in February 2026, while exhibitors at Medicall 2025 showcased integrated photonic gas analysis combined with spirometry for richer point‑of‑care diagnostics. These developments illustrate two critical trends: (1) product differentiation through combined sensing modalities, and (2) the blurring line between diagnostic hardware and continuous monitoring software platforms.
What the PW Consulting Spirometer Market report delivers (practical, executable content)
We structure the report to be directly usable by commercial and clinical leadership teams. Key deliverables include:
-
Top‑line market sizing and trend model (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario‑based sensitivities and revenue trajectory mapping to support five‑year budgets.
-
Competitive benchmarking dashboards: product feature maps, interoperability scores, NIOSH/compliance status and aftermarket service economics.
-
Go‑to‑market playbooks for three archetypes — OEMs seeking hospital penetration, medtech innovators pursuing direct‑to‑consumer/home health channels, and regional distributors targeting primary care networks.
-
Regulatory and procurement checklist: NIOSH CWHSP compatibility, accessibility standards, and country‑level certification roadmaps relevant to procurement cycles in 2026.
-
Reimbursement and pricing models: unit economics calibrated to current payer schedules, sensitivity to utilization rates and bundled service contracts.
-
M&A and partnership screening tools: valuation heuristics for tuck‑ins (software, consumables) and partner scorecards for cross‑selling respiratory care bundles.
-
Operational playbook for service and consumables: repair network design, consumable lifecycle planning and subscription monetization templates that lift overall EBITA.
Strategic recommendations for 2026 decision cycles
-
Prioritize interoperability and certified data pathways. For vendors seeking institutional and occupational health contracts, invest in certified electronic data transfer and program compliance now — procurement teams increasingly use NIOSH compliance and data‑format compatibility as pass/fail gates.
-
Shift to recurring revenue models. Given modest fee‑for‑service reimbursement (e.g., Medicare CPT 94060), hardware margins alone are insufficient. Bundle devices with software subscriptions, consumables and service agreements to stabilize revenue and increase customer lifetime value.
-
Differentiate with multi‑modal diagnostics. Combining spirometry with oximetry, gas analysis or AI‑driven interpretation creates defensible value propositions for clinics and home monitoring programs — as recent product demonstrations show, this is where buying interest is heading.
-
De‑risk market entry through targeted partnerships. For entrants, partnering with regional distributors, occupational health integrators or established clinical software vendors shortens procurement cycles and addresses after‑sales support — two common barriers to adoption.
-
Make service networks a strategic asset. In many markets, repair and calibration lead time determines clinician choice; invest selectively in localized service hubs or certified third‑party networks to increase conversion.
-
Use M&A to buy capabilities, not just share. The next wave of consolidation will favor buyers who acquire software orchestration, cloud analytics and regulatory compliance capabilities — not just incremental device volume.
Invitation — where to next?
This introduction is intentionally high‑signal and selective: it presents the macro picture, the competitive contours and the operational levers you need to evaluate options in 2026. For procurement teams, investors, and product leaders requiring granular split‑level intelligence (regional and application segmentation, product‑level revenue by country, supplier share matrices, and modeled reimbursement impacts by scenario), PW Consulting’s full Spirometer Market report contains the detailed datasets, financial models and executable templates that translate insight into decisions.
Contact the PW Consulting team for access to the full report package, the interactive forecast model (USD Million units), and a tailored briefing that maps these insights directly to your portfolio or procurement timetable.
For detailed analysis of this topic, please visit the official page: Spirometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


