



PW Consulting: Zinc Sulfide Market to Grow at 2.9% CAGR (2026–2032)

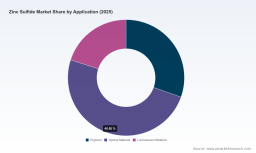
Zinc Sulfide Market 2026: Strategic Insights for Decision-Makers
As global value chains recalibrate and materials criticality ascends corporate board agendas, Zinc Sulfide (ZnS) is emerging as a quietly strategic commodity across pigments, optical substrates, and luminescent applications. PW Consulting’s latest Zinc Sulfide Market study (base year 2025; historical review 2020–2025; forecast 2026–2032) synthesizes market sizing, supply dynamics, regulatory risk, and competitive positioning into a decision-grade roadmap for executives planning capital allocation, sourcing, and product strategy in 2026.
Zinc Sulfide Market
Executive snapshot
- The global Zinc Sulfide market expanded modestly through the early-2020s, rising from roughly USD 115 million in 2020 to about USD 128 million in 2025.
- From the 2026–2032 forecast window the market is projected to grow at a compound annual growth rate of 2.9%, reaching the mid-100s million USD range by the end of the period.
- Market structure remains moderately fragmented: our concentration metrics indicate limited dominance by the largest players (CR3 ~28.5%; CR5 ~32.0%), creating room for regional specialists and niche technology suppliers to capture value.
These headline facts mask important inflection points — supply risk, purity-driven product differentiation, and regulatory shocks — that will determine value creation for suppliers, OEMs, and investors in 2026. Below we unpack the dynamics most likely to shape tactical and strategic decisions over the next 12–24 months.
Zinc Sulfide Market
Why this research matters for 2026 decisions
- Procurement and supply-chain leaders: Zinc Sulfide’s upstream exposure to zinc concentrates and refined zinc flows means procurement must translate commodity market moves into workable sourcing strategies. Our analysis equips buyers with scenario-driven hedging and diversification options.
- R&D and product strategy: ZnS is not a monolith — purity grades and form factors (e.g., powders, sputtering targets, phosphor grades) materially affect price, margin and end-use adoption. Our study explains where to prioritize investments in process control and analytic capability.
- Investors and corporate development: With a sub-30% CR3, attractive mid-stream profits can accrue to disciplined acquirers who combine regional footprint with high-purity manufacturing capability. The report quantifies transaction levers and integration risks.
Market dynamics and structural drivers
Three interlinked forces will govern Zinc Sulfide outcomes in 2026:
Zinc Sulfide Market
- Upstream feedstock and price dynamics: ZnS production ultimately ties back to zinc ore concentrates (sphalerite), and composites of refined zinc flows. Global zinc pricing (LME reference averages around USD 1.33 per pound in recent years) and regional refined zinc import concentrations materially influence producer margins and supply elasticity.
- Regulatory and trade volatility: Recent policy moves — from export controls affecting advanced materials to shifting tariff discussions — create episodic supply shocks. For example, geopolitical trade measures and temporary export control adjustments have already affected adjacent advanced-material supply chains and can propagate volatility into specialty ZnS supplies.
- Demand composition and quality premium: Demand is driven not just by volumetrics but by specification. Optical and thin-film applications command a quality premium and long qualification cycles. This creates asymmetric value that favours producers with stringent quality systems and co-development capabilities with OEMs.
Collectively these forces produce a market that grows at a steady, modest clip but is highly sensitive to episodic supply and technology shifts. Our forecast reflects this: steady compound growth accompanied by mid-period oscillations driven by cyclical end-markets and regulatory episodes.
Regulatory and regional risk highlights
- Refined zinc import dependence: Some major markets source a significant portion of refined zinc from abroad, making them vulnerable to trade measures and tariff negotiations that can alter feedstock economics for ZnS producers.
- Export control regimes: Recent export restrictions and temporary suspensions on critical materials underscore the need for scenario planning. Materials upstream or adjacent to ZnS value chains can be subject to sudden policy shifts that ripple downstream.
- Input-cost pressures: In several regions, sulfur and energy-related pressures have firmed intermediate prices (e.g., for zinc sulfate), increasing production cost floors for ZnS manufacturers and compressing margins where quality premiums are absent.
Competitive landscape — what leaders and challengers are doing
The ZnS competitive set mixes multinational specialty chemical firms, regional producers, downstream thin-film and sputtering-target suppliers, and by-product producers. Notable players analysed in the report include globally diversified specialty chemical producers, regional pigment specialists, and several Chinese and Indian manufacturers focused on high-purity and phosphor-grade powders.
- Global specialty incumbents leverage scale and diversified product portfolios to serve optical and industrial customers.
- Regional manufacturers and thin-film specialists offer localized supply and tailored grades for deposition and photonics applications.
- By-product producers can act as swing suppliers, introducing episodic supply into the market depending on polymetallic ore economics.
Our competitive maps evaluate capability across four strategic vectors: product purity and QA systems; thin-film and target manufacturing; customer co-development and qualification; and logistic/resilience footprints. While the largest firms provide stability and breadth, the fragmentation numbers indicate meaningful opportunity for targeted M&A or partnership plays — particularly in high-value, high-purity niches.
Actionable strategic imperatives for 2026
Executives should prioritize three pragmatic lines of action this year:
- Secure and diversify high-quality feedstock: Translate exposure to refined zinc and concentrate flows into concrete contracts and optionality. Consider multi-sourcing, toll-manufacturing agreements, and convertible offtakes to manage supplier concentration risk.
- Invest selectively in purity and qualification capability: The highest margins accrue to producers that can reliably meet optical and phosphor-grade tolerances and shorten qualification cycles for OEMs. Investments in analytics, clean-room processing and co-development labs yield disproportionate commercial returns.
- Embed regulatory scenario planning into procurement and sales strategies: Build a minimal set of trade-policy scenarios and map their impact on supply costs, lead times, and customer qualification. Use these scenarios to define pre-authorized sourcing and pricing responses.
For investors and corporate development teams, we recommend a playbook centered on bolt-on acquisitions that add purity capability or regional market access, coupled with operational improvements to lift yields and stabilize cost-of-goods sold.
What the full PW Consulting report delivers (practical content)
Our research is structured to inform executable decisions, not just descriptive market commentary. Key deliverables include:
- Verified market sizing and a transparent forecast model (2026–2032) with scenario toggles for commodity and policy shocks.
- Supply-chain mapping from sphalerite concentrate to finished ZnS grades, highlighting chokepoints, lead-time metrics, and cost pass-through sensitivities.
- Competitive profiles and capability matrices for leading manufacturers and specialty suppliers — including technology, geographic reach, and go-to-market posture.
- Commercial playbooks tailored to buyers, suppliers, and investors: procurement term templates, supplier scorecards, M&A due-diligence checklists, and go-to-market frameworks for grade introductions.
- Regulatory and geopolitical risk matrix with mitigation options calibrated to different exposure levels.
In keeping with our “trailer” principle, the executive summary above surfaces the analytical thrust and strategic recommendations; the full study contains the granular segmentation, price and margin curves, and supplier-level exhibits required to operationalize these insights.
Recent market intelligence and signals to monitor
- Trade-show and innovation signalling: Firms continue to showcase additive and specialty ZnS grades at major coatings and materials events — an indicator of product-development momentum in pigment and additive applications.
- Upstream raw material trends: Watch zinc price movements and regional refined zinc trade flows closely; they are leading indicators for input-cost pass-through into ZnS pricing.
- Policy watch: Pay special attention to export-control and tariff movements from major producing and consuming geographies. Temporary embargoes or suspensions can rapidly reshape procurement economics.
These signals, as well as pricing and supply anecdotes, are synthesized into time-stamped intelligence layers in our subscription dataset to support rolling decision cycles.
Methodology and credibility
The study combines primary interviews (producers, OEMs, traders), proprietary bottom-up supply modelling, and triangulation with public data sources. We reconcile company disclosures, trade flows, and commodity price series to produce a defensible market view. Where granular segment numbers materially affect commercial outcomes, we reserve those exhibits for the full report to protect commercial value and support client licensing.
Next steps — how to use these insights in 2026
- For procurement: request the supply-risk appendix and the supplier scorecard toolkit to operationalize diversification strategies.
- For product and R&D leads: seek the Q&A on purity-driven qualification pathways and test-facility investments included in the report.
- For investors and BD teams: review our M&A playbook and target screen to prioritize high-margin, de-riskable acquisitions.
PW Consulting’s Zinc Sulfide Market study is designed to be a working document for 2026 — not an archival read. If you are preparing supplier contracts, evaluating capex for a purity upgrade, or modeling the impact of trade-policy scenarios on margin, the evidence-based scenarios and tools in the full report will materially shorten your decision cycle.
Contact and access
Access to the full study and our dynamic forecast models is available through PW Consulting’s research portal. Clients may license the dataset, commission custom scenario runs, or engage our advisors for a tailored workshop that applies these findings directly to your commercial plans for 2026.
For detailed analysis of this topic, please visit the official page: Zinc Sulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


