



PW Consulting: Video Intercom Market Poised for USD 652.4M by 2032, 12.45% CAGR

Video Intercom Devices Market: Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s senior industry analysts, we present a tightly focused executive introduction to our full Video Intercom Devices Market study. Built on a 2025 base, the research spans the historical window 2020–2025 and delivers a forward view across 2026–2032. The market is on a clear expansion trajectory: our base modelling shows mid‑double‑digit aggregate growth (CAGR ~12.45%) from the 2025 baseline toward a materially larger installed and recurring‑revenue opportunity by the end of the forecast horizon. This briefing explains why that projected growth matters for boardroom priorities in 2026, what forces will determine winners and losers, and how the full PW Consulting deliverable equips executives to convert signals into decisions — without exhausting the proprietary, granular tables and segment-level forecasts that we reserve for subscribers and clients.
Video Intercom Devices Market
Why this research matters now
-
Strategic inflection: Video intercoms have evolved from utility devices to strategic edge nodes in property security, resident experience and building‑level telemetry. The device‑level market is becoming entwined with cloud platforms, identity and access services, and managed security offerings — creating new revenue models for OEMs and integrators.
Video Intercom Devices Market -
Capital allocation decisions: Investment committees in 2026 are weighing capex across product roadmaps, software development, and M&A. Our study translates top‑line market growth into investment scenarios and risk‑adjusted ROI pathways that support real capital decisions.
Video Intercom Devices Market -
Procurement and supply chain: Procurement leaders must respond to concentrated supplier risk and recent export controls disrupting key components. Our analysis provides actionable sourcing strategies and stock/contract playbooks tailored to these dynamics.
-
Commercial models: As subscription and managed‑service adoption accelerates, commercial teams need product packaging, channel incentives and pricing tests. The report contains buyer persona maps and GTM experiments you can operationalize in 90 days.
Macro picture and what the headline numbers mean
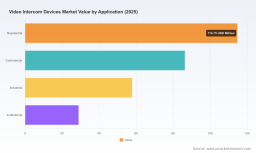
At the aggregate level the market is moving from a mid‑hundreds of millions (USD, base year 2025) toward a substantially larger market by the early 2030s. Growth is driven by converging adoption in residential, commercial and institutional applications and by rising spend on integrated building security and cloud services. A roughly 12.45% compound annual growth rate over the forecast period signals more than a cyclical uptick — it reflects structural change: higher device density per building, software monetization, and replacement cycles driven by camera/AI upgrades and cybersecurity requirements.
Importantly, market concentration is moderate. The largest three suppliers account for a meaningful share of revenue, while the top five widen that footprint; the result is an environment where scale advantages coexist with meaningful opportunities for specialists and fast followers that can out‑execute on integration, software, or channel access.
Key market dynamics to watch (2026 lens)
-
Platformification: Buyers increasingly prefer solutions that integrate with building management systems, access control platforms and mobile identity services. Intercoms that act as secure edge gateways unlock new service layers — but demand expertise in cloud ops, data privacy and APIs.
-
SaaS and recurring revenue: Manufacturers and integrators are testing subscription bundles (cloud storage, concierge services, remote monitoring). These models improve lifetime value but require investment in billing, SLAs and support economies.
-
Component & geopolitical risk: Two sets of supply‑side events are reshaping procurement risk. First, export controls and trade policy actions affecting rare earths and specialty materials have increased concentration and price volatility for some components. Second, recent rulings and export licensing requirements have extended controls to products incorporating Chinese‑sourced materials — complicating certification and cross‑border procurement for OEMs with global supply chains.
-
Technology convergence: PoE, Wi‑Fi‑6/6E, IP‑native audio/video, on‑device AI for analytics and privacy‑preserving processing are migrating from premium lines into mainstream portfolios. This compresses feature premium but expands addressable use cases.
-
Channel evolution: System integrators remain crucial, but new routes — property managers, telco bundles and direct consumer channels — are gaining share where service layers are differentiated.
Competitive landscape — what the field tells us
The competitive set is diverse, spanning specialist intercom manufacturers, multinational electronics groups and security system integrators. Below are focused strategic reads on core players we track closely. These summaries emphasize strategic posture rather than attempting an exhaustive financial comparision.
-
Aiphone Corporation (Japan) — Strength: deep product family and proven scalability across multi‑tenant and commercial deployments. Strategy: continue to leverage a hardware‑centric reputation while expanding cloud integration options for enterprise customers. Tactical risk: translating hardware loyalty into cloud subscription economics.
-
Panasonic Corporation (Japan) — Strength: broad consumer and commercial footprint with strong R&D in wireless and DECT integrations. Strategy: play both high‑quality residential and commercial markets with a focus on extensibility and brand recognition.
-
Dahua Technology (China) — Strength: aggressive cost/feature positioning and deep CCTV integration. Strategy: compete on integrated solutions and mobile app tie‑ins. Tactical risk: regulatory and supply‑chain scrutiny in some geographies.
-
Honeywell International (US) — Strength: systems integrator reach and cross‑selling into existing building controls. Strategy: embed intercoms within broader access and automation bundles for commercial clients.
-
Siedle & Sohne (Germany) — Strength: premium, IP‑centric systems with growing cloud concierge functionality. Recent product releases underline an aggressive move into cloud services and large residential complexes — a case study in how premium vendors can expand into service revenue.
-
Comelit (Italy) & Legrand (France) — Strengths: strong OEM/installer networks in Europe and product lines tuned to property management needs. Strategy: focus on integrated building ecosystem and installer economics.
-
Zenitel (Norway), 2N (Czech Republic), TCS AG (Germany) — Strengths: specialized IP/SIP solutions and ruggedized devices for industrial and critical infrastructure. Strategy: capture high‑value verticals where reliability and standards compliance are the purchase drivers.
Recent market activity reinforces these dynamics: product innovations from companies such as Siedle (enhanced concierge and cloud‑enabled stations released in late 2025 and early 2026), Mircom’s touchscreen launch in 2025, and targeted project installations by specialists such as Zenitel signal rapid feature rollouts and verticalization.
Strategic implications and priority actions for 2026
-
Build dual‑track roadmaps: preserve hardware differentiation in the near term while accelerating a parallel path for software, cloud services and subscription offerings.
-
Harden procurement: implement a supplier‑tiering framework that accounts for geopolitical export controls and rare‑material exposure; prioritize dual‑sourcing for critical semiconductors and optics.
-
Monetize services: run controlled pilots of managed‑service bundles with select integrator partners to establish pricing benchmarks and churn metrics before full roll‑out.
-
Refine channel economics: redesign incentive models to favor long‑term service relationships (installation + recurring services) rather than one‑time hardware discounts.
-
Pursue targeted inorganic moves: prioritize tuck‑ins that accelerate cloud, analytics or edge‑AI capabilities rather than broad scale acquisitions that add hardware volume but little digital capability.
-
Invest in compliance and certification: build capabilities to manage cross‑border supply restrictions and 0.1%‑type rules that can create compliance costs and limits to how products are manufactured and sold.
-
Protect margins via modularization: design platforms that allow OEMs to upsell software features without wholesale hardware replacements.
What PW Consulting’s full report delivers (operational highlights)
-
Transparent forecast model (base year 2025; scenario variations across 2026–2032) with downloadable inputs so clients can run custom scenarios.
-
Market dynamics heatmap and supplier risk matrix mapping supply‑chain exposures (including rare‑earth and specialty material risks) to product lines and geographies.
-
Vendor scorecards and go‑to‑market playbooks for OEMs, integrators and telco partners, including partner selection checklists and contract templates for recurring revenue deals.
-
Commercial experiments and pricing sensitivity analyses for subscription vs. perpetual models, plus seven ready‑to‑deploy pilot designs.
-
M&A screening tool: a prioritized list of capability targets by strategic theme and integration complexity.
-
Regulatory tracker and compliance playbook detailing how export controls and material restrictions flow through BOMs, certifications and country‑of‑origin risk.
How to use this briefing — next steps
Consider this article a strategic trailer: it highlights key vectors and near‑term actions, but the granular segmentation, pricing ladders, and interactive financial models are intentionally reserved for the full PW Consulting report and bespoke advisory engagements. If your team is evaluating product roadmap shifts, supplier re‑architecture, or a go‑to‑market pivot in 2026, the next step is a short diagnostic workshop with our practice to translate the study’s insights into prioritized, time‑bound initiatives and a tailored implementation plan.
PW Consulting stands ready to run scenario workshops, validate procurement hedges, or support M&A due diligence — all anchored to the rigorous forecasting and operational toolkits in the full report. Reach out to discuss a focused, outcome‑oriented engagement that turns the market’s projected growth and the evolving risk landscape into defensible, revenue‑driving action.
For detailed analysis of this topic, please visit the official page: Video Intercom Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


