



PW Consulting: Durable Juvenile Products Market Eyes USD 20.14M by 2032 with 7.4% CAGR

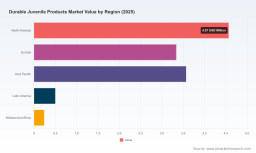
Durable Juvenile Products Market 2026: Strategic Imperatives from PW Consulting’s Market Preview
Executive trailer
The durable juvenile products market is entering a phase where safety mandates, sustainability expectations and channel reshaping converge to create both higher margins for market leaders and fresh entry points for agile challengers. Our upcoming PW Consulting research—anchored on a comprehensive 2020–2025 historical base and a 2026–2032 forecast horizon—quantifies this transition and translates it into operational and strategic choices that matter for 2026 planning cycles.
Durable Juvenile Products Market
Macro trajectory: what the headline numbers say (and why they matter)
At a compound annual growth rate of 7.4% over the forecast horizon, the global durable juvenile products market is projected to move significantly beyond its mid‑decade size. From a clearly measurable base in the early 2020s, the market expands steadily through 2026 and beyond, reaching materially larger scale by 2032. This pace of growth is robust for a category that blends discretionary spend with essential safety purchases—meaning that both premiumization and value plays remain viable, but require different operational priorities.
Durable Juvenile Products Market
For executives defining 2026 budgets, three immediate implications arise from these macro dynamics:
Durable Juvenile Products Market
- Volume growth will support continued investment in product safety certification and higher‑margin innovations, but only if go‑to‑market execution and distribution partnerships are optimized.
- Capital allocation decisions (R&D vs. M&A vs. channel development) must be guided by scenario planning: higher growth predictable in safety‑led premium products and in services (aftermarket, rental, refurbishment) where margins can outpace product sales.
- Supply chain resilience and materials strategy become differential advantages—both to protect gross margins and to authenticate sustainability claims increasingly required by regulators and retailers.
What’s inside the full PW Consulting research (practical outputs)
The report is built for decision-makers. It blends quantitative forecasting with executable workstreams and toolkits to accelerate 2026 initiatives, including:
- Market sizing and validated forecasts by product family and channel, with sensitivity scenarios reflecting regulatory shocks and raw‑material price swings.
- A regulatory and standards playbook mapping current CPSC and voluntary verification programs and their near‑term trajectories, with a step‑by‑step compliance checklist for new product introductions (NPIs).
- Commercial playbooks tailored for manufacturers, retailers and private equity buyers: pricing ladders, trade promotion optimization, and omnichannel assortment frameworks.
- Supply‑chain risk matrices and procurement levers focused on high‑impact inputs (fabrics, polymers, metal assemblies), plus mitigation strategies—dual sourcing, nearshoring and long‑lead inventory modeling.
- Go‑to‑market templates for digital direct‑to‑consumer (D2C) launches, subscription and rental pilots, and enhanced aftermarket services (repair, certification transfers, trade‑in programs).
- Target screening for bolt‑on M&A and JV opportunities, with scorecards combining strategic fit, manufacturing footprint, and achievable synergies.
- Consumer segmentation insights and product design direction informed by ethnographic studies and retailer scan data to shorten concept‑to‑shelf cycles.
Competitive landscape: how incumbents and challengers are positioning
The durable juvenile products market sits in a moderately fragmented structure—where the largest three players account for under a third of global revenues and the top five capture roughly a third. That concentration level indicates meaningful room for both scale plays and niche premium strategies.
Across the competitive set we analyzed, several archetypes and strategic postures emerge:
- Heritage global brands (e.g., Artsana/Chicco, Peg Perego, Inglesina): leverage long-standing distribution relationships and safety credentials, and are investing in sustainable materials and product longevity to defend premium pricing.
- North American platform multibrands (e.g., Newell Brands with Graco, Baby Jogger): focus on scale distribution, retailer co‑development and multi‑channel assortment optimization, using awards and recognized product lines to drive retail shelf space.
- Asia origin OEMs and global integrators (e.g., Goodbaby International): combine cost competitiveness with rapid product cadence and increasing IP around modular platforms—they are pivotal players for white‑label and co‑branded programs.
- Safety‑centric specialists (e.g., Britax, Recaro, BeSafe): differentiate on engineering, certification leadership and post‑sale service; these players will capture premium share where safety compliance and advanced restraint systems are strict buying criteria.
- Design and lifestyle specialists (e.g., Stokke, BabyBjörn, Ergobaby): compete on ergonomic design, lifestyle branding and D2C experience, which resonates with affluent parent cohorts and allows higher gross margins.
Recent company moves underscore these dynamics: product awards and recognized innovations continue to drive retail momentum (e.g., accolade wins for Graco in 2025), while progressive material choices—like Artsana’s 2024 shift to recycled polyester in apparel categories—signal how sustainability is being operationalized. Britax’s late‑2025 expansion of its all‑in‑one line with recycled, naturally flame‑retardant fabrics exemplifies how product extensions are being used to marry safety and sustainability claims.
Regulation, standards and industry governance—implications for 2026
Regulatory and verification regimes are tightening and expanding. The Consumer Product Safety Commission continues to be the principal federal authority on durable juvenile products, and industry verification programs have broadened scope to encompass new categories. Notably, the industry association’s rebranding to the Baby Safety Alliance in 2025 reflects a strategic refocus toward rigorous safety verification and broader category coverage.
Operationally, firms must expect higher inspection and certification intensity. Our report provides a prioritized compliance map: which tests are now table stakes, which are differentiators, and how to cost‑effectively validate claims across geographies. For 2026 planning, allocating incremental spend to verification and labeling will be non‑negotiable for market access and for downstream retail listings.
Trade, taxation and policy noise—near‑term levers
Policy changes—both at state and federal levels—affect pricing and demand patterns. For example, selective sales tax reductions on juvenile products in certain jurisdictions during 2025 altered local affordability dynamics and retailer promo strategies. Similarly, the industry’s advocacy work around tariff exemptions for safety‑critical products highlights the importance of coordinated trade lobbying as a margin protection tactic.
Strategic playbook for 2026 (what to do now)
Based on our integrated analysis, PW Consulting recommends four pragmatic moves for organizations aligning 2026 actions with mid‑term value creation:
- Prioritize certified safety and sustainability upgrades on core product platforms: Allocate R&D and capex to retrofit best‑selling models with verified recycled content and to streamline compliance workflows—this protects retail distribution and supports premium price positioning.
- Rebalance channel investments toward D2C and service monetization: Run controlled pilots for subscription/rental and certification‑anchored resale to capture aftermarket margins and to extend lifetime customer value.
- Execute targeted M&A or strategic partnerships to shore up capability gaps: Use our report’s M&A scorecards to identify bolt‑ons that reduce sourcing risk or accelerate entry into high‑margin segments (safety systems, ergonomic carriers, modular strollers).
- Harden supply chain resilience: Hedge key raw materials, diversify production geographies and implement serialized product verification to address both regulatory traceability requirements and consumer trust concerns.
What we are intentionally holding back (and why you should read the full report)
To keep this article a high‑value preview, we have purposely not disclosed granular segmentation tables, regional breakout percentages or specific application‑level revenue line items. The full PW Consulting report contains those critical layers—detailed by product family, channel and market scenario—and includes downloadable models executives can use to run bespoke forecasts for board presentations and investment committees.
Next steps
As you formalize your 2026 strategic plan, the choices you make now about product compliance, materials sourcing, channel mix and M&A will determine whether you capture disproportionate share from the market’s projected expansion. PW Consulting’s full Durable Juvenile Products Market study equips teams with the numbers, the playbooks and the target lists to move from insight to execution in weeks—not months.
Contact PW Consulting to access the complete dataset, scenario models and the actionable annexes that support board‑ready strategic recommendations for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Durable Juvenile Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


