



Washing Machines Market to Reach USD 344.8M by 2032 at 3.7% CAGR — PW Consulting

Washing Machines Market — 2026 Strategic Preview
As companies prepare strategy roadmaps for 2026, the washing machines market demands a disciplined, evidence‑based response. PW Consulting’s latest study synthesizes market sizing, regulatory change, product innovation, and competitive positioning into an actionable intelligence package. This preview highlights the strategic value of the full report for executives making portfolio, go‑to‑market, and M&A decisions next year — demonstrating the depth of our analysis while intentionally preserving the granular segment matrices available in the full subscription.
Washing Machines Market
Headline market context: steady expansion, technology intensification
The market reached a material milestone in our base year (2025), and the trajectory into the forecast horizon is clear: after consistent growth through 2020–2025, the industry is positioned for continued expansion underpinned by appliance modernisation and feature premiumization. Our topline model — expressed in USD Million — shows the market advancing in 2026 and compounding toward 2032 at a mid‑single‑digit CAGR (3.7% across the forecast period). These macro dynamics establish both opportunity and urgency for product strategy, regulatory compliance, and channel investments.
Washing Machines Market
Why this study matters for 2026 decisions
- Regulatory timing matters: New energy and testing requirements that took effect in 2025 are now shaping permissible product specifications and test laboratories’ workloads. Manufacturers and retailers must adapt design and validation calendars to avoid costly stock obsolescence or late certification.
- Technology is redefining value: AI, camera‑guided optimisation, automatic dosing, and integrated wash‑to‑dry combos are moving feature sets from niche differentiators to mainstream purchase drivers. Product roadmaps that do not prioritise these capabilities risk compression on price and margin.
- Channel and service economics are evolving: Aftermarket services, subscription models, and digital ecosystems are shifting lifetime value calculations. Decisions made in 2026 about service infrastructure and digital experiences will affect customer retention for years.
What the full report delivers (practical, decision‑ready outputs)
- Robust topline and forecast model (historical 2020–2025 and forward 2026–2032) in USD Million, with scenario testing for macro and regulatory shocks.
- Actionable go‑to‑market playbooks for OEMs and distributors — covering SKU rationalisation, pricing ladders, and channel mix optimisation.
- Competitor profiles and capability maps that benchmark R&D focus, product features, and go‑to‑market choices across the industry’s leading players.
- Regulatory impact assessment and compliance roadmaps aligned with recent DOE requirements and major international standards.
- Investment and M&A screening: target clusters, valuation comparators, and integration risk assessments tailored to strategic buyers and private equity.
- 100‑day operational checklists for engineering, QA, and supply‑chain teams to align product launches with new testing regimes and consumer expectations.
Market dynamics shaping 2026 strategy
- Feature convergence around smart AI capabilities. Vendors are embedding machine learning across fabric sensing, cycle optimisation, and wash‑to‑dry sequencing. Expect feature parity to increase; sustained differentiation will require ecosystem play (voice, app services, home automation integration).
- Energy and test standards as product architects. Mandatory conservation standards and updated testing protocols are no longer peripheral — they directly influence motor choice, sensor suites, and materials selection. Product teams must lock regulatory inputs into concept gating.
- Modular platforms and scale economics. Manufacturers are choosing between platform consolidation (to amortise R&D and certification costs) and targeted modularity (to serve regional preferences). Each approach has trade‑offs for speed to market, inventory complexity, and aftermarket parts strategy.
- Service and ownership models reshape margin pools. Subscription laundry care, extended warranties, and service‑first marketing create recurring revenue opportunities that can offset compression in product gross margins.
- Channel shift and inventory risk. E‑commerce and direct channels increase visibility into sell‑through; however, they also heighten sensitivity to SKU proliferation and returns. Retailers are tightening assortments around proven, differentiated SKUs.
Competitive landscape — where leading players are placing their bets
The market’s competitive topography is mixed: several global incumbents hold meaningful shares while a broad middle layer of regional and specialist manufacturers competes on price, durability, or feature niches. Market concentration metrics indicate that the top few firms capture a material portion of value, but there is substantial headroom for focused challengers and regional champions.
Washing Machines Market
- Samsung Electronics (Suwon, South Korea): Rapidly scaling its Bespoke AI Laundry Combo with enhanced AI Wash & Dry + and voice optimisation. Samsung’s strength is ecosystem integration and strong brand pull for premium smart appliances; competitive implications include elevated expectations for user experience and faster wash‑to‑dry timelines.
- LG Electronics (Seoul, South Korea): Pushing AI frontiers with the AI DD 2.0 series that touts tens of thousands of wash patterns and advanced fabric/soil detection. LG’s approach signals a race for algorithmic superiority and patentable wash logic.
- Whirlpool (Benton Harbor, US): Focused on reliability, high‑efficiency top‑ and front‑load models with convenience features (Load & Go dispenser, FreshFlow). Whirlpool remains a benchmark for scale manufacturing and channel reach, critical for mass segments.
- Robert Bosch (Gerlingen, Germany): Emphasising precision (automatic dosing i‑DOS) and intuitive interfaces (ProWash). Bosch’s play is premium efficiency and durability aligned with environmentally conscious buyers.
- AB Electrolux (Stockholm, Sweden): Double‑down on energy‑efficient front‑loads and compliance with top efficiency tiers; Electrolux targets sustainability‑minded consumers and premium dealer channels.
- Haier Group (Qingdao, China): Aggressive product innovation (multi‑drum concepts and camera‑guided optimisation) and rapid rollouts at major trade shows. Haier’s scale and price engineering enable fast experimentation and regional customisation.
- Midea, IFB, Toshiba, Panasonic : Each brings regional strengths — from large‑capacity smart suites to compact, efficiency‑focused units for constrained living spaces. These players compete on price, localisation, and specific feature sets.
Recent product launches and line extensions through late 2025 and early 2026 underline a shift: vendors are accelerating investments in AI, camera sensing, and multi‑function combos. These moves increase feature competition but also raise the bar for certification and quality assurance.
Strategic playbook — immediate priorities for 2026
- Lock regulatory compliance into engineering timelines. Treat energy standards and testing windows as non‑negotiable inputs to product development and procurement.
- Adopt a two‑track product architecture. Maintain a modular platform for cost efficiency while enabling rapid feature add‑ins (AI modules, dosing hardware) for premium or regional SKUs.
- Monetise aftercare. Design subscription and extended service offers that leverage telematics and predictive maintenance to improve retention and lifetime value.
- Prioritise software and UX talent. Differentiation is moving from drum design to data models and mobile experiences — invest accordingly or partner with specialist start‑ups.
- De‑risk supply chains. Rebalance sourcing to reduce single‑point exposures and create capacity buffers for certification retesting.
- Use M&A strategically. Acquire narrow‑scope techs (AI, dosing, camera sensing) instead of large, overlapping businesses to accelerate time to differentiated product features.
Signals to watch in 2026 (early warning indicators)
- Adoption rates for AI‑enabled combos versus conventional models.
- Retail sell‑through velocity and return rates on newly certified SKUs.
- Warranty claim trends tied to new sensor suites or smart features.
- Patent filings and partnership announcements in wash‑pattern algorithms and dosing technology.
- Shifts in channel mix and aftermarket subscription take‑rates.
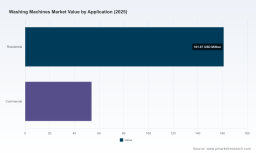
PW Consulting’s full washing machines market report contains the granular regional, type and application splits, vendor scorecards, cost‑build models, and a set of 12 executable recommendations with timeline and resource estimates. For strategy teams preparing 2026 budgets and 3‑year product roadmaps, the report supplies the calibrated inputs required to prioritise engineering spend, plan SKU rationalisation, and target the highest‑return geographies and channels.
To access the complete datasets, scenario models, and tailored 100‑day playbooks that transform these insights into implementable plans, please consult the full study on our portal. PW Consulting stands ready to assist with bespoke workshops to translate the findings into board‑level decisions and operational roadmaps for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Washing Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


