



PW Consulting: Hemp Fiber Market Soars to USD 1.8B in 2025

Hemp Fiber Market 2026 Briefing: Strategic Imperatives for Leaders
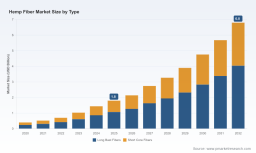
As PW Consulting’s senior industry analyst, my objective in this briefing is to translate our latest Hemp Fiber Market research into the decision frame that matters most for executives planning moves in 2026. The market is transitioning from niche to scale: after rising from roughly USD 0.4 billion in 2020 to an estimated USD 1.8 billion in 2025 (base year), modelled growth projects the market to reach the mid-single-digit billions by the early 2030s under an 18.5% CAGR. Those headline dynamics matter, but the value for busy leaders is practical line-of-sight: where to allocate capital, how to design resilient supply chains, and which commercial partnerships and capabilities will determine winners over the next 24 months.
Hemp Fiber Market
Why this study matters for 2026 decision-making
-
Clarity in a high-growth window: The market’s compound annual growth rate near 18.5% creates a compressive time frame in which scale and market access matter disproportionately. Late entrants face not only higher cost of capture but increasing technical and regulatory barriers to entry.
Hemp Fiber Market -
Intersection of agriculture, industrial processing and textiles: Hemp fiber is not a single-technology play; it requires orchestration across farm production, decortication/processing, fiber refinement, and end-market integration (textiles, composites, construction and specialty industrial uses). Decisions that ignore any node in this value chain create downstream margin leakage.
Hemp Fiber Market -
Regulatory inflection points: Federal and state policy changes in 2025–2026 materially alter commercial viability and compliance cost structures. Firms that align strategy to the evolving regulatory landscape unlock faster go-to-market than those that react after the fact.
Market trajectory — a strategic reading
Our topline model uses 2025 as the base year. The market expanded rapidly during 2020–2025, reflecting both new processing capacity and growing end-market adoption. The forecast through 2032 shows continued acceleration driven by textile re-shoring, increasing use of natural fiber composites in mobility and construction, and premiumisation in sustainable apparel. For corporate leaders this means a two-tier decision horizon: tactical investments to secure feedstock and processing capacity in 2026–2027, and strategic investments (R&D, brand partnerships, and plant scale) for 2028 onward.
Key demand and supply dynamics (executive summary)
-
Demand drivers: Sustainability mandates in apparel and automotive sectors, rising consumer preference for natural-fiber content, and regulatory encouragement for low-carbon building materials are collectively broadening demand beyond legacy niche buyers.
-
Supply evolution: U.S. open-field fiber hemp production is rising—our reference data shows production increasing in 2025, with measured growth and an average grower price signal that keeps raw material economics attractive for processors and composite manufacturers.
-
Processing bottlenecks: Decortication and fiber refinement capacity remains the gating factor. Investments in low-impact technologies that can produce textile-grade fibers at scale are the differentiator between commodity and premium product strategies.
-
Fragmented supplier base: Market concentration is low; the top three players capture only about a quarter of the market, and the top five roughly one-third. This fragmentation creates opportunities for consolidation and for buyers to secure preferential supply via partnerships and offtake agreements.
Regulatory and policy context — immediate implications
-
Enforcement timing matters: USDA’s delayed enforcement of DEA-registered laboratory testing until December 31, 2026, effectively creates a short window of regulatory uncertainty. Firms should plan compliance upgrades but can use the delay to test and scale traceability, lab partnerships, and QA workflows.
-
Farm Bill language: Draft 2026 Farm Bill provisions that clarify industrial hemp as an agricultural commodity are likely to reduce producer-level regulatory burdens. This will encourage farm acreage expansion and vertical integration by processors seeking feedstock security.
-
State-level variance: States are moving at different paces on retail registration and labeling. Firms scaling to new states must account for asymmetric compliance processes and potential product-retail restrictions.
Competitive landscape — strategic profiles and recent moves
The market’s present structure includes vertically integrated firms, specialized processors, and technology-driven textile startups. The competitive landscape is best read as a set of capability clusters rather than pure product players: (1) raw-material aggregators and decorticators, (2) refinement and textile innovators, and (3) downstream integrators focusing on composites and construction systems.
-
IND HEMP, LLC (Fort Benton, Montana): A decortication and export-oriented operator that has been active in building trade relationships with textile manufacturers in Asia. Recent April 2026 MOU activity to integrate U.S.-grown fiber into Vietnam’s textile supply chain signals a play to bridge premium U.S. feedstock with cost-competitive downstream textile capacity.
-
American Hemp, BastCore, Hemp Inc., BaFa, Konoplex (U.S.): These players emphasize vertical integration—scaling decortication and processing while pursuing offtake with textile and construction customers. Their strategy centers on securing feedstock, optimizing processing yields, and reducing unit costs per kilogram of usable fiber.
-
Canvaloop & Ecofibre : Technology-led incumbents focused on low-impact conversion and textile-grade outputs. Product launches and IP around waste-to-fiber processes position them as suppliers for premium yarn and fabric producers.
-
Dun Agro Hemp Group & Cavac Biomateriaux (Europe): European processors and materials specialists that emphasize construction and composite systems, offering partnership potential for market entrants seeking regional manufacturing capacity and regulatory know-how.
Recent signals to watch: capacity expansions (e.g., new textile plants aimed at U.S. hemp fiber adoption), product launches of textile-grade yarns, and trade shows where technologies for decortication and refined fiber are showcased. These are early indicators of which players will move from pilot to industrial scale in 2026–2027.
Strategic playbook — recommended actions for 2026
-
Secure feedstock through diversified offtake and tolling agreements. Given rising production and remaining processing capacity constraints, buyers should lock in multi-year procurement agreements but avoid single-source dependency.
-
Invest selectively in processing intelligence. Rather than building large decortication plants outright, consider strategic minority investments in technology providers or capacity-as-a-service models that can scale with demand.
-
Pursue co-development with textile and composite manufacturers. Early-stage product integration and co-design reduce time-to-market and allow firms to codify quality specs that become de facto industry standards.
-
Operationalize regulatory readiness. With federal and state rules in flux, dedicate a compliance pod to track lab-testing requirements, labeling rules, and cross-border documentation to prevent costly market access delays.
-
Design for modular expansion. Capex in 2026 should favor modular plants and flexible processing lines to pivot between textile-grade and industrial-grade outputs as demand signals solidify.
Risks and watchlist for C-suite
-
Regulatory reversals or tightening: If federal enforcement timelines change or state-level restrictions proliferate, markets and offtake timelines could be disrupted.
-
Quality and standardization shortfalls: Inconsistent fiber quality and lack of agreed industry standards can slow adoption by mainstream textile and automotive OEMs.
-
Feedstock concentration shocks: Weather events or input-price volatility at the farm level could create short-term scarcity and margin pressure; hedging and geographic diversification are essential mitigants.
-
Competitive consolidation: Roll-ups by stronger cash-rich players could change the negotiating landscape quickly; mid-sized players should be clear about exit or scale-up thresholds.
What the full PW Consulting report delivers (practical scope)
-
Granular demand modelling by application pathways and adoption scenarios through 2032, with sensitivity analysis under alternative policy outcomes.
-
Capex and Opex benchmarking for decortication, refining and textile conversion, with unit economics for common plant sizes and processing technologies.
-
Supplier and buyer due-diligence templates and a playbook for structuring offtake and tolling agreements tailored to hemp fiber.
-
Competitive profiles with capability matrices, patent and technology mapping, and M&A heatmaps to support inorganic growth decisions.
-
Regulatory scenario planning tools and a compliance roadmap aligned to USDA, state-level requirements and likely Farm Bill outcomes.
To preserve the report’s commercial value and to respect partner confidentiality, this briefing intentionally omits detailed split data across regions, finer application percentages, and proprietary segment-level revenue tables. Those elements—critical for transaction diligence and operational planning—are available in the full report.
Concluding guidance
2026 is a make-or-break year for organizations aiming to lead in the hemp fiber value chain. The macro trajectory—marked growth from a small base and an 18.5% CAGR—creates high reward for the firms that combine supply security, processing capability, and early partnerships with textile and composite buyers. Companies that move too slowly risk being commodity suppliers to a set of integrated players that already control scale processing and preferential trade channels.
If your board’s 2026 agenda includes new materials, low-carbon product lines, or sustainable sourcing commitments, treating the hemp fiber market as a strategic growth frontier—not a tactical experiment—will materially change outcomes. PW Consulting’s full Hemp Fiber Market report provides the data, operational tools, and negotiation templates you need to convert opportunity into competitive advantage. Contact our research access desk to obtain the complete dataset and modelling workbooks that support the recommendations outlined here.
For detailed analysis of this topic, please visit the official page: Hemp Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


