



PW Consulting: Floor Panel Market to Reach USD 299.2M by 2032 at 6.56% CAGR

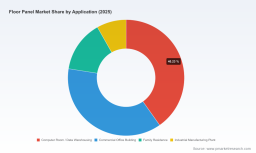
Floor Panel Market — 2026 Strategic Brief
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present this strategic introduction to our latest Floor Panel Market study. Grounded in a rigorous base year of 2025 and a forward-looking 2026–2032 forecast horizon, this brief highlights the decision-relevant intelligence executives must factor into 2026 planning cycles. The narrative demonstrates the analytical depth available in the full report while intentionally withholding granular segment-level outputs — the precise splits, channel shares and line-item forecasts are reserved for the report portal to preserve the “trailer” experience and drive direct engagement with our interactive model.
Floor Panel Market
Market trajectory you need to plan around
Our bottom-up model tracks a focused industry definition measured in USD (Million). The floor panel market expanded from approximately 143.2 million in 2020 to 195.4 million in 2025, reflecting rebound and structural demand across commercial infrastructure, data centers and flexible office refits. Looking out, we project growth to roughly 299.2 million by 2032, implying a compound annual growth rate of 6.56% over the forecast period. The step-change between 2025 and subsequent years is driven by concentrated investment in resilient, serviceable flooring systems that integrate cabling, airflow management and sustainability credentials.
Floor Panel Market
Note: broader industry publications cite larger aggregate valuations for the “flooring” universe (for example, industry sources report a global floor panels market in the multi-billion-dollar range in 2025). PW Consulting’s scope isolates market activity consistent with the product and application definitions used throughout our modeling — a clarity that delivers actionable, enterprise-grade insights for capital allocation and product strategy.
Floor Panel Market
Why this study matters for 2026 corporate decisions
-
Timing and capital allocation: With 2026 budgets being finalized, the trajectory embedded in our 2026–2032 scenarios helps boards and business unit leaders justify or re-prioritize investment in manufacturing capacity, digital configuration tools, and service platforms.
-
Procurement and supply-chain resilience: Raw-material sourcing and supplier concentration are primary cost and lead-time risks. Our analysis identifies where procurement concentration and regulatory standards are likely to exert the greatest pressure on lead times and margin stability.
-
Product, specification and standards alignment: Compliance regimes (notably EN ISO 20326:2018 and its subsequent A1:2020 amendment) are raising entry barriers for loose-laid and certain engineered systems. Specification-driven procurement in commercial and mission-critical applications means manufacturers who can demonstrate certified compliance will capture disproportionate value.
-
Go-to-market design: The convergence of modularity, low-profile systems and integrated cable/airflow features is reshaping buyer requirements — particularly among data-center operators and flexible-office landlords. The study transforms these trends into executable GTM and commercialization playbooks.
What the full report delivers — a practical toolkit for executives
-
Market sizing and validated forecasts (2020–2025 historical; 2026–2032 forward) built from primary interviews, capacity-mapping and transactional datapoints.
-
Scenario suite: base, upside, downside and disruption cases with sensitivity to raw-material price shocks, regulatory tightening, and accelerated green-spec adoption.
-
Modularity and product roadmaps: specification checklists, performance trade-off matrices (load vs. acoustics vs. ventilation), and quick-win product changes to increase sell-through and margin capture.
-
Channel and commercial playbooks: specifier engagement templates for architects and MEP consultants, distributor incentive models, and installer enablement programs optimized for 2026 procurement cycles.
-
Supplier scorecards and concentration heat maps that identify single-source risks and near-term disruption vectors across polymer, metal and composite inputs.
-
M&A and partnership screen: capability-first criteria for targets that accelerate access to high-growth applications or deliver fill-in capabilities (e.g., ventilation-ready panels, low-profile systems, or zero-VOC laminated ranges).
-
Interactive dashboards and an accompanying financial model that allow users to test custom scenarios and evaluate the P&L impact of strategic choices.
Key themes and strategic implications
-
Demand concentration in infrastructure-sensitive applications. Investment in mission-critical environments (e.g., data centers) and high-availability commercial spaces is a major demand engine. These buyers prioritize serviceability, airflow management and certified fire/structural performance over lowest-cost solutions.
-
Material and design differentiation are decisive. Lightweight metals, engineered wood cores and calcium-based composites each offer distinct value propositions. Manufacturers that can combine performance with sustainability credentials (e.g., low VOCs, recycled content) will gain specification advantages.
-
Standards compliance is a gatekeeper. EN ISO 20326 and its amendments are increasingly referenced by architects and procurement teams; compliance is non-negotiable for high-margin specifications.
-
Service orientation expands margins. Warranty upgrades, on-site maintenance contracts, and predictive maintenance enabled by sensor integration convert commoditized panels into annuity-like services.
-
Market structure remains fragmented. Despite some national champions and specialized exporters, the top-three and top-five manufacturers account for a relatively modest share of total market revenue — a dynamic that preserves M&A opportunities for consolidation and capability plays.
Competitive landscape — focused profiles and strategic inference
-
Tate Access Floor (Columbia, MD, USA) : Tate’s ConCore® raised access panels are positioned as premium solutions for commercial office and data center segments, with variants engineered for heavy loading and integrated ventilation. Their strategy emphasizes certified performance, specification-driven sales and sustainability features. Strategic implication: Tate should continue deepening specifier relationships, extend service contracts for mission-critical applications, and invest selectively in ventilation-enabled R&D to protect premium unit economics.
-
FreeAxez (Delran, NJ, USA) : FreeAxez markets low-profile modular steel systems designed for flexible workspaces, emphasizing integrated cable management and rapid reconfigurability. This proposition aligns with hybrid-office trends and end-user demand for agility. Strategic implication: FreeAxez can scale by building installer networks, licensing modular sub-assemblies to global partners, and adding digital configuration tools that reduce specification friction.
-
Swiss Krono (Menznau, Switzerland) : Known for high-quality laminated panels with zero-VOC options, Swiss Krono competes on durability, indoor air quality and installation flexibility—attributes prized in commercial fit-outs. Strategic implication: Swiss Krono’s pathway to higher value lies in expanding European spec channels, integrating circular-sourcing claims and certifying products for leading green building programs.
Recent industry association activity underscores shifting supply-chain relationships: in May 2026 several upstream and downstream players joined major trade associations, signaling both consolidation of specification dialogue and potential collaboration on compliance and sustainability initiatives. For manufacturers and buyers, these moves can shorten time-to-standardization or accelerate raw-material alignment — both of which affect 2026 procurement choices.
Decision playbook for 2026
-
Prioritize product lines that combine serviceability and compliance. Shift R&D emphasis to ventilation-ready and low-profile systems where ROI timelines match procurement cycles.
-
Lock in strategic suppliers where single-source risk is material. Negotiate long-term agreements with key polymer and metal suppliers and build dual-sourcing options for critical inputs.
-
Commercialize services alongside products. Pilot maintenance-as-a-service offerings in one major account to validate pricing and operational models.
-
Target bolt-on acquisitions that fill capability gaps (e.g., sensor integration, modular pedestals, or installer networks) rather than purely revenue-dilutive roll-ups.
-
Operationalize compliance: institute a certification roadmap tied to product launch milestones and integrate compliance checkpoints into warranty and contract language.
Why PW Consulting’s study is different
Our report blends primary commercial intelligence, supplier and installer interviews, and a transaction-level model calibrated to 2020–2025 observed performance and a 2026–2032 forecast calibrated to macro and micro indicators. The study provides an executable playbook — not just high-level views — including procurement templates, M&A screens and a live financial model. For executives preparing 2026 capex requests, GTM shifts or M&A dossiers, the report converts trend signals into dollarized outcomes and operational checklists.
To preserve the consultative value of the work and to guide senior buyers toward tailored insights, we reserve granular segmentation tables and the complete dataset for the report portal. Readers seeking specific regional, type and application splits — and the downloadable scenario model used to generate the forecasts above — should access the PW Consulting report center for full access and an onboarding walkthrough by our analyst team.
In closing: 2026 will be a year of selective investment and specification-led competition in the floor panel market. Executives who blend product compliance, service monetization and supply-chain resilience into their strategic plans will turn the market’s growth trajectory into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Floor Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


