



PW Consulting: Acrylic Rubber Market to Rise to USD 2,670M by 2032 at 6.98% CAGR

Acrylic Rubber Market 2026: Strategic Preview for Executive Decision-Making
Executive Teaser
As the acrylic rubber (ACM) market enters a new phase of maturation and technical differentiation, 2026 will be a pivotal year for commercial and capital decisions. This preview synthesizes the most consequential, data-driven signals from PW Consulting’s full market study (base year 2025; historical 2020–2025; forecast 2026–2032) to equip senior leaders with the strategic framing needed to act quickly and confidently. The market expanded from roughly USD 1.29 billion in 2020 to USD 1.685 billion in 2025 and is forecast to reach about USD 2.67 billion by 2032, implying a compound annual growth rate of approximately 6.98% through the forecast horizon. While this briefing surfaces the strategic implications, detailed segment-level tables, regional and application breakdowns, and proprietary scenario models are reserved for the full report.
Acrylic Rubber Market
Why 2026 Matters — The Inflection Points
-
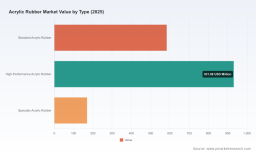
Acceleration of technical differentiation: Demand is shifting from commodity acrylic rubbers toward specialized grades that combine heat, oil and low-temperature performance. Manufacturers that can demonstrate certified performance in demanding end-use environments are gaining pricing power and share.
Acrylic Rubber Market -
Supply-side consolidation and concentration: The market shows meaningful concentration among a handful of global producers, with the top three and five players commanding substantial combined shares. This structure creates asymmetric advantages for firms with scale, integrated feedstock access, and global manufacturing footprints.
Acrylic Rubber Market -
Raw material and energy dynamics: Early 2026 pricing and tariff signals are already reshaping sourcing calculations and capital plans for energy-intensive production.
Market Fundamentals — What the Numbers Tell Us
Between 2020 and 2025, the industry grew steadily, reflecting resilient end-demand from automotive sealing systems, industrial machinery, and specialty oil-engine applications. Looking forward to 2032, the market’s near 7% CAGR reflects a composite of steady replacement demand, incremental new specifications (notably in powertrain and industrial sealing for electrified systems), and margin-accretive migration to higher-value grades.
At the same time, market concentration metrics point to an environment where mid- and long-term profitability will increasingly hinge on technical differentiation, operational scale, and proximity to feedstock and strategic customers. These dynamics create both defensive rationales for incumbent players and acquisition opportunities for growth-seeking entrants.
Dynamics to Watch — Inputs, Regulations, and Cost Signals
-
Raw materials: Upstream volatility has returned as a primary driver. Analysts reported that butyl acrylate prices in April 2026 were firm across major hubs, with China and India showing elevated price points after Q1 pressures driven by higher acrylic acid costs and constrained supply. For manufacturers, this underlines the need for robust feedstock hedging and alternative sourcing strategies.
-
Energy and transmission economics: Regulatory developments are altering manufacturing cost structures. Notably, a tariff proposal published in late 2025 adjusted transmission tariffs for high-voltage customers—creating differentiated energy cost outcomes for large plants depending on their connection class. Firms that lock favorable power contracts or re-optimize plant locations may secure a structural competitiveness advantage.
-
End-market evolution: Automotive OEMs continue to demand lower-emission profiles and higher durability in sealing systems, while industrial customers prioritize longer service intervals and improved solvent and oil resistance—trends that are increasing the share of high-performance and specialty ACM in procurement specifications.
Competitive Landscape — Profiles and Strategic Implications
The competitive map is dominated by established polymer and specialty chemical players that combine proprietary grades, regional manufacturing footprints, and close OEM relationships. Three representative suppliers illustrate the archetypes and strategic playbooks we examine in the full study:
-
Zeon Corporation (Tokyo) — A technology-led producer with a portfolio of ACM grades targeted at both heat-resistant and low-temperature applications. Zeon’s strategy relies on regional manufacturing capabilities (including sites in Asia and North America) and grade-level differentiation. Its multi-site capacity and product breadth make it a natural partner for global OEM programs and a difficult competitor to displace on performance-spec accounts.
-
Mitsui Plastics, Inc. (Tokyo) — A specialty orientation emphasizing high-purity acrylic esters and advanced grades (low-Mooney, epoxy- and carboxyl-modified, cold-resistant variants). Mitsui’s technical depth and product customization capabilities position it to win development contracts where specification and processing characteristics matter as much as unit price.
-
Unimatec Chemicals Europe GmbH (Germany) — Focuses on ACM grades engineered for automotive seals, gaskets and hose applications demanding heat and oil resistance. Unimatec’s value proposition is a mix of performance certification and close European OEM integration.
Collectively, the competitive environment rewards integrated capabilities—product R&D, regional manufacturing flexibility, and secure feedstock access. The market’s concentration levels also mean that targeted M&A, JV strategies and selective capacity investments are viable paths to rapid share gains for well-capitalized challengers.
What the Full Report Contains — Practical, Actionable Elements
PW Consulting’s full Acrylic Rubber Market study translates these dynamics into executable tools for C-suite and commercial leaders. Highlights include:
- Granular demand models and scenario-based forecasts through 2032 (by region, type, and application) with sensitivity testing for raw material and energy shocks.
- Supply-side mapping: plant-by-plant capacity, vintage, throughput economics and retrofit potential.
- Price and margin analytics: historical pass-through patterns, break-even curves, and recommended commercial hedges for common feedstocks.
- Competitor scorecards: capabilities, strategic intent, and likely next-move playbooks for the leading suppliers.
- Regulatory and ESG checklists tailored to production and downstream applications, including capex implications and compliance timing.
- 90-day to 24-month action frameworks for procurement, R&D prioritization, go-to-market and inorganic growth.
These modules are delivered with an integrated financial model and customizable scenario dashboards to support board-level investment and M&A decisions.
Strategic Recommendations for 2026 Decision Cycles
Based on the market trajectory and the competitive dynamics above, PW Consulting recommends executive teams prioritize the following in 2026:
-
Secure feedstock options and hedge selectively: Given the early-2026 firmness in butyl acrylate and related feedstocks, firms should institutionalize multi-supplier contracts, consider regional sourcing hedges, and evaluate partial fixed-price agreements to stabilize input cost exposure.
-
Prioritize high-value grade deployment: Redirect R&D and commercial focus toward grades that address rising OEM specifications—especially heat- and oil-resistant variants—where margin uplift and longer-term contracts are achievable.
-
Re-evaluate plant footprints against tariff and energy regimes: Transmission tariff adjustments create a window for optimizing large-site economies. Model energy contract renegotiations and potential relocation or capacity toggling for vulnerable plants.
-
Use M&A and JVs to close capability gaps: Acquire or partner to fast-track access to specialty grades, regional customer lists, or feedstock integration—especially where organic timelines would miss 2026 commercial windows.
-
Implement customer co-development pilots: Lock multi-year offtakes by sharing development costs and guaranteeing performance milestones—this is particularly effective with OEMs specifying higher-performing sealing solutions for electrified vehicles and industrial equipment.
Risk Factors and Contingencies
Key uncertainties that should be stress-tested in every strategic plan include prolonged upstream constraints, abrupt regulatory shifts affecting energy tariffs or chemical use, and faster-than-anticipated substitution of ACM by competing elastomers in certain niche applications. Our full report contains scenario matrices and decision-tree guidance to assess capex and commercial outcomes under each contingency.
Conclusion — What to Do Next in 2026
The acrylic rubber market presents both defensive imperatives and offensive opportunities this year. Leaders who align procurement discipline with targeted investments in differentiated grades, while preserving tactical flexibility on capacity and energy exposure, will capture disproportionate upside. PW Consulting’s full study provides the granular segmentation, supplier-level intelligence, and transaction-ready financial models you need to convert these insights into actionable 2026 plays.
For the complete data tables, segmented forecasts, plant-level maps, and a downloadable Excel model, please consult the full report landing page. The detailed breakdowns and proprietary scorecards are intentionally reserved for the full study to preserve the integrity of our client-grade analysis and to enable tailored consulting engagements.
For detailed analysis of this topic, please visit the official page: Acrylic Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


