



PW Consulting: ALA Market to Reach USD 1,466M by 2032 at 5.92% CAGR

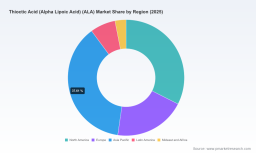
Thioctic Acid (Alpha Lipoic Acid, ALA) Market: Strategic Imperatives for 2026
As PW Consulting’s lead industry analyst, I present a concise but incisive preview of our full-market study on Thioctic Acid (Alpha Lipoic Acid, ALA). This briefing is designed to demonstrate the analytical rigor and practical orientation of the research while reserving the granular, transaction-grade intelligence for the full report. For corporate leaders planning 2026 allocations—R&D, sourcing, M&A, or commercialization—this note explains why ALA deserves prioritized strategic attention this year.
Thioctic Acid (Alpha Lipoic Acid) (ALA) Market
Executive snapshot
- The global ALA market has expanded meaningfully from the early 2020s into the mid-decade, reaching a base-year total of approximately USD 985 million in 2025. Our forecast, built on a blend of bottom-up capacity modelling and demand-side adoption curves, projects compound annual growth of 5.92% across the 2026–2032 horizon, lifting the market toward roughly USD 1.47 billion by 2032 under the base scenario.
- Market structure shows a mid-level concentration: the top three producers control material share of the market, with the top five firms approaching half of global supply—enough to shape pricing and access dynamics, but not so dominant as to preclude targeted entrants and contract manufacturers from capturing niche value.
- Critical drivers are changing rapidly: form differentiation (stereoisomer and formulation science), regulatory trajectories in major jurisdictions, and upstream raw-material volatility together create both risk and arbitrage opportunities for agile players.
Why this matters for 2026 corporate decisions
Companies that treat ALA as a commodity will be outcompeted by those that take a portfolio approach—aligning technical differentiation (R-ALA vs other forms), supply resilience, and regulatory strategy. With the market passing the USD 900–1,000 million threshold in 2025 and clear mid-single-digit growth ahead, 2026 is the inflection year for commitments: securing long-term supply contracts, investing in stabilized-enantiomer capabilities, and standing up regulatory playbooks for market access. Timing matters: lead times for qualified suppliers, capacity expansion, and dossier development for certain geographies all intersect in the 12–24 month window.
Thioctic Acid (Alpha Lipoic Acid) (ALA) Market
Market trajectory and interpretation of the numbers
- Historical momentum: The market expanded materially between 2020 and 2025, reflecting rising consumer and clinical interest in antioxidant and neuroprotective applications, broader supplementization in aging populations, and incremental adoption in cosmeceutical formulations.
- Forecast logic: Our 5.92% CAGR is scenario-weighted—combining a base case that assumes stable commodity inputs and conservative regulatory outcomes, with downside and upside variants tied to raw-material price shocks and regulatory rulings. The plan-of-record projection to 2032 therefore signals durable, investible demand rather than a transient fad.
- Concentration implications: With the top echelons of suppliers controlling a meaningful portion of available capacity, pricing power will reside with those who can credibly pledge supply continuity and quality certifications. That creates a premium for suppliers that can demonstrate solvent-free processes, enantiomeric purity, or clinical-grade manufacture.
Market dynamics: where immediate risks and opportunities lie
- Raw-material and cost pressure: Conversion economics for ALA are sensitive to inputs such as medium-chain fatty feedstocks. Recent swings in octanoic-acid-related inputs (driven by El Niño effects in 2024–2025) produced double-digit percent swings in upstream costs, narrowing supplement margins and forcing repricing or reformulation decisions. Buyers should stress-test margin models against +/- 20% raw-material volatility.
- Regulatory headwinds and marketing constraints: In the U.S., limitations on certain nutrient claims have already narrowed permissible marketing language, a trend likely to continue as regulators scrutinize structure–function assertions. In the EU, ongoing Article 8 evaluations could materially curtail permitted uses of ALA in supplements in certain scenarios—our modelling includes a sensitivity that quantifies material market contraction if adverse determinations are issued.
- Reimbursement and clinical channels: Compounded ALA retains a role in certain pharmacy compounding pathways in the U.S., and clinical use in neuropathy and metabolic support continues to underpin pharmaceutical interest. Companies that bifurcate strategies—one for consumer-facing supplements and another for clinical/pharmaceutical channels—stand to capture higher-value product placement.
- Supply-chain concentration: Two Chinese suppliers supplied a very large share of global ALA capacity in 2025, creating geographic single points of failure. Events such as shipping disruptions in strategic maritime chokepoints amplified that risk during the prior 18 months. Buyers should evaluate dual-sourcing, strategic inventory, and alternative-route logistics to immunize programs against episodic outages.
Competitive landscape: what the leading players reveal about strategy
The report benchmarks key manufacturers and brand owners across product purity, form portfolio, geographic footprint, and go-to-market approach. Highlights include:
Thioctic Acid (Alpha Lipoic Acid) (ALA) Market
- Sabinsa Corporation (East Windsor, NJ): Known for high-purity ALA targeted at cosmeceutical and nutraceutical customers. Their playbook focuses on branding around ingredient pedigree and application support for formulators—valuable for partnerships in premium SKUs.
- AlzChem Group AG (Trostberg, Germany): A strategic differentiator is its solvent-free, Alipure® manufacturing claim—positioning for pharmaceutical and dietary-supplement channels that prioritize low residual solvents and consistent crystalline profiles.
- GeroNova Research Inc.: Commercializes stabilized R‑lipoic acid enantiomer forms. Their approach demonstrates the commercial value of enantiomer-specific R&D and how clinical substantiation translates into a pricing premium.
- Jarrow Formulas and other branded supplement houses: These players convert ingredient-level differentiation into consumer messaging (nerve support, antioxidant benefits). Their success underscores the importance of evidence-backed claims and supply certainty.
- Large-volume suppliers in China and India (several contract and bulk manufacturers): They deliver scale and cost leadership but introduce concentration and quality narrative challenges for western buyers—creating an opening for near-shore or regionally certified providers who can bridge cost and compliance.
Overall, the ecosystem reveals three viable competitive plays: (1) premium technical differentiation (clinical-grade R‑ALA, solvent-free processes), (2) cost-and-scale supply leadership, and (3) branded consumer product differentiation. Most successful strategies combine elements of two of these plays rather than pure single-axis competition.
What the PW Consulting report delivers (practical, transaction-ready content)
Our full study is engineered for decision-makers who need executable outputs for 2026 action plans. Key deliverables include:
- Demand and supply models with SKU- and form-aware forecasting to 2032, including upside/downside scenarios tied to regulatory and raw-material shocks.
- Supplier scorecards and a CR3/CR5 concentration map that identifies substitution levers, qualification lead times, and risk-adjusted capacity.
- Regulatory decision trees for major jurisdictions (U.S., EU, Asia) with contingency roadmaps and dossier checklists to accelerate market defense or entry.
- Pricing sensitivity analysis and margin impact matrices to inform pricing strategy and contract negotiation thresholds.
- M&A and partnership heatmaps, highlighting targets and acquirers by strategic fit—technical capabilities, geographic profile, and certification footprint.
- Commercial playbooks—go-to-market trajectories for branded supplements, cosmeceuticals, and pharmaceutical channels, including recommended clinical-investment thresholds to achieve premium positioning.
- Supply-chain stress tests and inventory-optimization templates to model resilience at given service levels and cost-of-capital assumptions.
Strategic recommendations for 2026 (prioritized)
- Lock in supply diversity: Execute at least one long-form offtake or capacity reservation with an alternate-region supplier while qualifying a domestic/regional backup. The concentration profile makes this a first-order risk-mitigation action.
- Invest selectively in differentiation: For firms targeting premium channels, prioritize R‑ALA capabilities or partnerships with suppliers who hold solvent-free/clinical-grade claims. The ability to substantiate efficacy and purity is increasingly monetizable.
- Prepare regulatory playbooks now: Anticipate constrained marketing language and potential EU Article 8 impacts. Pre-emptive dossier harmonization and targeted clinical endpoints will shorten time-to-market if regulators require additional evidence.
- Model cost shocks into your pricing: Run scenario analyses that stress raw-inputs by +/-20% and quantify pass-through versus margin compression. Use indexed contract clauses where feasible to share volatility risk with suppliers or customers.
- Explore M&A selectively: Look for bolt-on manufacturers that close geographic supply gaps or brands with sticky direct-to-consumer channels to capture downstream margin.
Conclusion — the 2026 decision window
With a base-year market approaching USD 1 billion and a mid-single-digit growth trajectory through 2032, ALA represents a market with real scale and differentiated value pools. The strategic playbook for 2026 is clear: secure supply flexibility, invest in credible product differentiation, and build regulatory resilience. PW Consulting’s full report provides the granular maps—by form, application, and region—plus supplier-level intelligence and operational templates you need to move from strategy to execution.
Next steps
To access the complete datasets, breakouts, and executable tools (including our supplier scorecards, scenario models, and M&A heatmap), please visit the PW Consulting report page. The full intelligence package is structured to accelerate your 2026 planning and to convert uncertainty into prioritized, fundable actions.
For detailed analysis of this topic, please visit the official page: Thioctic Acid (Alpha Lipoic Acid) (ALA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


