



PW Consulting: PGMEA for Electronic Materials to Reach USD 207.08M by 2032 (6.2% CAGR)

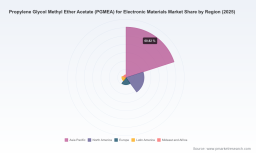
Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials — Strategic Preview for 2026 Decision Makers
As global electronics supply chains reassess resilience, cost and regulatory risk entering 2026, Propylene Glycol Methyl Ether Acetate (PGMEA) continues to be a strategically critical specialty solvent across semiconductor manufacturing, photoresist chemistry, and display production. This briefing frames the strategic value of PW Consulting’s full market study for executives making capital allocation, procurement, and M&A decisions in 2026. It highlights the structural drivers underpinning market growth, the levers that will determine competitive advantage, and the practical, actionable analyses the full report delivers—while intentionally reserving granular tables and proprietary segmentation to the paid report.
Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market
Market trajectory at a glance
- Recovery and momentum: The PGMEA market has shown sustained expansion from the early-2020s into the mid-decade, reflecting the electronics industry’s recovery and structural demand from advanced semiconductor and display processes.
- Size and pace: On a macro basis, the market expanded from approximately 101 million USD in 2020 to roughly 136.8 million USD by the 2025 base year, and is projected to reach just over 207 million USD by 2032 under the central scenario—a compound annual growth rate (CAGR) of about 6.2% over the forecast window.
- Implication for 2026 planning: That growth profile translates into predictable incremental demand for high‑purity grades, but also amplifies supply‑chain and regulatory pressures that will shape supplier selection and investment timing in 2026 and beyond.
Why this market matters to your 2026 playbook
- Strategic input to high-value manufacturing: PGMEA is not a commodity in electronics contexts—electronic‑grade specifications and manufacturing controls materially affect wafer yields and downstream device performance. Procurement decisions therefore have direct operational and quality implications for chip fabs and advanced packaging lines.
- Price and margin lever: Electronic-grade PGMEA commands a purity premium in the high single-digit dollars per kilogram range—an input cost that can erode or protect margin depending on sourcing strategy, hedging, and specification management.
- Exposure to upstream volatility: Production costs are sensitive to propylene oxide and acetic acid feedstock moves. Volatile feedstock pricing has historically transmitted quickly to contract and spot terms, creating timing risk for buyers and opportunity for producers who can hedge or vertically integrate.
- Regulatory and emissions constraints: Tighter emissions rules in North America and Europe, and chemical notification requirements such as those under US TSCA for novel grades, add compliance cost and time-to-market risk—important inputs for capex scheduling and product launch planning.
Competitive landscape: concentration, capabilities, and recent shifts
The PGMEA value chain exhibits a measurable degree of concentration: the top three producers control a meaningful share of global market volumes, and the top five account for a clear majority. This concentration creates both negotiating power for large buyers and an elevated strategic premium for incumbents who can guarantee ultra-high purity, on-time shipments, and regulatory compliance.
Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market
- Major integrated chemical players dominate supply: Multinational producers with integrated propylene-based operations and established global distribution networks (examples include large petrochemical and specialty chemical groups) hold the manufacturing scale and logistical reach that many electronics customers require.
- Specialists in high‑purity grades maintain differentiation: Several specialist producers and chemistry-focused firms have developed refined purification and quality control platforms that are valued by semiconductor and display manufacturers.
- Recent industrial moves: Notable capacity expansions in Asia-Pacific by leading specialty chemical producers (announced in 2025) reflect a strategic bet on continued electronics-driven demand and a push to secure regional supply for OEMs and fabs in the Asia supply cluster.
Supply‑chain and regional dynamics—what keeps CEOs awake
- Geography matters: Asian production hubs continue to be the primary global source for PGMEA volumes, creating freight, insurance, and tariff differentials that raise landed cost for North American and European purchasers. For global procurement teams, regional sourcing decisions now require integrated landed-cost modeling—not just unit-price comparisons.
- Feedstock and cost transmission: Propylene oxide and acetic acid remain the upstream cost drivers. Sharp moves in these feedstocks can rapidly compress producer margins or pass through to buyers, depending on contract structures and inventory strategy.
- Regulatory overlay: Pre‑manufacture notifications and evolving emissions standards introduce time and compliance costs. These factors are increasingly part of supplier selection criteria for risk‑averse OEMs.
What PW Consulting’s full report delivers (practical, transaction‑ready content)
PW Consulting’s comprehensive study translates market intelligence into operational decision tools for 2026. Key deliverables designed for immediate executive and C-suite use include:
Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market
- Granular demand and growth scenario models—multiple demand scenarios calibrated to semiconductor fab build-outs and display industry trajectories (note: granular region/application tables and underlying assumptions are provided in the paid report).
- Supplier scorecards and risk maps—qualitative and quantitative assessments of manufacturing capability, quality systems for electronic‑grade production, on‑time performance, regulatory compliance posture, and logistics risk.
- Cost and margin playbooks—bottom‑up cost models that decompose COGS drivers, feedstock sensitivity analyses, and threshold pricing required to justify new capacity investments or long‑term offtake deals.
- Procurement and contracting frameworks—recommended contract structures for 2026 (fixed/variable blends, indexation approaches tied to feedstock, inventory commitments), and a ready‑to‑use supplier due‑diligence checklist tuned to high‑purity solvents.
- M&A and capex prioritization guidance—valuation multiples, earn‑outs, and go/no‑go IRR thresholds for greenfield versus bolt‑on acquisitions in regions where growth or supply security is most urgent.
- Regulatory compliance playbook—roadmap for TSCA notifications, EU/NA emissions compliance, and best practices for product stewardship and customer specification management to accelerate qualification in semiconductor supply chains.
Strategic recommendations for 2026 (actionable, prioritized)
Below are prioritized moves for key stakeholder groups based on PW Consulting’s analysis.
- For producers and investors:
- Prioritize capacity investments in proximity to major electronics clusters while coupling expansions with rigorous quality systems—scale alone will not win business without documented ultra‑high purity performance.
- Implement feedstock hedging programs or secure long‑term upstream offtakes to stabilize margins. Consider vertical integration opportunities where economics support capex payback within acceptable investment horizons.
- Assess targeted M&A to acquire purification know‑how or local logistics assets that reduce landed cost exposure for key customers.
- For semiconductor and display OEMs / large consumers:
- Move from spot buying to portfolio contracting: blend strategic long‑term supply agreements for core volumes with spot opportunities to capture favorable pricing windows.
- Invest in multi‑sourcing where feasible to mitigate regional disruption risk; evaluate local blending/packaging hubs to reduce freight and tariff impact.
- Embed supplier auditing for regulatory compliance (TSCA and regional emissions) as a mandatory gating criterion pre-qualification step.
- For private equity and strategic buyers:
- Screen assets for quality‑process differentiation and existing customer relationships within semiconductor value chains—these attributes command multiples above generic solvent assets.
- Use the PW Consulting cost models to stress-test valuation under commodity feedstock swings and tightening regulatory scenarios.
Risks, blind spots and watch‑points for 2026
- Feedstock shocks remain the single most material short‑term risk to both margins and contract pricing—scenario stress tests in the full report demonstrate asymmetric impacts across different contracting strategies.
- Regulatory developments could lengthen qualification cycles for new grades or suppliers; buyers should allow for regulatory lead time in their supplier onboarding timelines.
- Geopolitical shifts and trade measures that affect freight and tariff regimes could quickly invert landed-cost advantages—dynamic sourcing strategies and regional stocking can mitigate but not eliminate this risk.
Competitive profiles (what executives need to know)
Leading chemical producers combine scale, global logistics, and integrated feedstock access, while specialist firms focus on purification and single‑source reliability for electronic processes. Recent capacity expansions in Asia and ongoing investments in quality and environmental controls highlight where incumbents are placing strategic bets. PW Consulting’s supplier dossiers provide executive briefs on manufacturing footprints, product portfolios, quality certifications, and commercial posture—synthesized into procurement negotiation playbooks.
Conclusion — how to use this preview in 2026 planning
This briefing establishes the strategic contours of the PGMEA market that matter for 2026 decisions—stable mid‑single digit CAGR growth, concentration among incumbent chemical producers, material procurement and regulatory risk, and a clear premium for electronic‑grade performance. The full PW Consulting report converts these insights into executable work streams: sourcing strategies, contract templates, cost models, and M&A screening filters tailored for executives who must commit capital or lock in supply in 2026.
For boards, procurement leaders, and corporate development teams preparing 2026 plans, the next step is a targeted review of the full report’s proprietary segmentation tables, supplier scorecards, and quantitative scenario outputs. These deliverables are intentionally gated to provide clients with actionable, defensible intelligence when negotiating contracts, sizing investments, or pursuing transactions in this strategically important specialty chemicals space.
To obtain the full dataset, supplier dossiers, and executable tools referenced in this preview, visit PW Consulting’s Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market report page or contact our advisory desk for a tailored briefing and model package.
For detailed analysis of this topic, please visit the official page: Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


