



PW Consulting: Hardening Machines Market to Reach USD 344.8M by 2032, 6.98% CAGR (2026–2032)

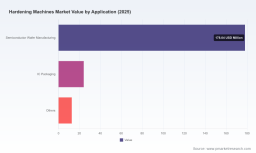
Hardening Machines Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s senior industry analyst presenting the Hardening Machines Market study, this briefing is designed as a strategic companion for executive teams planning capital allocation, supply-chain adjustments, product roadmaps, and M&A activity in 2026. We combine a multi‑year historical view (2020–2025) with a forward-looking forecast (2026–2032) to surface practical signals, vendor dynamics, and operational priorities — while reserving the full segment-level intelligence for the complete report.
Hardening Machines Market
Market snapshot: trajectory and scale
-
Base year and scope: The report uses 2025 as the base year and traces historical performance from 2020–2025, with a forecast window spanning 2026–2032.
Hardening Machines Market -
Absolute scale: The Hardening Machines Market recorded meaningful expansion over the historical window and stood at approximately USD 215.0 Million (revenue unit: Million) in 2025 according to our consolidated model.
Hardening Machines Market -
Growth outlook: The market is projected to grow at a compound annual growth rate (CAGR) of about 6.98% through the forecast period, driving the market to a mid‑to‑high‑hundreds million USD opportunity by 2032 under our central scenario.
-
Concentration: Competitive concentration is relatively low, with the top three and five players together accounting for single‑digit to low‑twenty percent ranges, reflecting a fragmented landscape that favors both specialized suppliers and regional champions.
Why the 2026 planning cycle matters
2026 will be a pivot year for organizations that depend on advanced hardening technologies — from automotive powertrain suppliers to precision component shops serving semiconductor and industrial OEMs. Several concurrent forces make this planning cycle distinct:
-
Capital intensity meets tightened energy economics. Buyers are re-evaluating CapEx payback horizons in light of rising energy scrutiny and decarbonization targets; energy-efficient induction systems are increasingly assessed not only for throughput and quality but as instruments of energy security and emissions reduction.
-
Standards and process assurance. Formal standards (for example, industry specs that govern induction hardening practices) are tightening qualification criteria for outsourced heat treatment and in‑house equipment procurement. Compliance risk now factors into supplier selection and capital approvals.
-
Modularization and automation. Vendors are accelerating modular and cell-based hardening architectures that integrate seamlessly with CNC machining and automated material handling — changing TCO and creating new retrofit opportunities.
-
Raw-material and input cost volatility. Steel feedstock and coil prices remain a direct input to the economics of component manufacture and, by extension, to demand for hardening services and equipment replacement cycles.
Strategic implications for enterprises
-
Investment timing: Locking in projects in 2026 should consider mid‑cycle availability of modular induction solutions that shorten installation and qualification time. For firms with aggressive decarbonization targets, prioritize units with clear energy-intensity and emissions reporting capabilities to accelerate regulatory and ESG approvals.
-
Technology choice: Induction hardening continues to displace older fuel‑based furnaces where cycle time, repeatability, and footprint matter. However, application-specific tradeoffs remain (penetration depth, part geometry, throughput), so product selection needs to be driven by a short list of in‑plant performance tests rather than vendor brochures alone.
-
Service and aftermarket as strategic lever: Given the fragmented vendor map, maintenance, sensorization, and digital service offerings are differentiators. Enterprises should procure with an eye toward lifecycle service contracts, remote diagnostics, and upgrade pathways that protect long-term productivity.
-
Supply-chain resilience: Component makers should hedge procurement by qualifying multiple vendors across geographies while ensuring compatibility of control systems and process recipes to avoid costly re‑qualification.
-
M&A and partnerships: Fragmentation creates opportunities for bolt‑on consolidation and strategic alliances — especially for companies seeking to combine induction expertise with automation and thermal-process controls.
Competitive landscape — profiles and positioning (select companies)
The vendor ecosystem is composed of specialized induction equipment suppliers, furnace manufacturers, machine-tool integrators, and turnkey system builders. Below are concise strategic profiles illustrating capability clusters and how incumbents are positioning themselves:
-
SECO/WARWICK (Poland) — Offers vacuum furnaces and induction technologies; positions around full-system heat treatment solutions for industrial customers seeking process integration. ( https://www.secowarwick.com)
-
Nabertherm (Germany) — Electric furnaces and heat-treatment platforms; appeals to customers needing standardised thermal-process equipment with proven reliability. ( https://www.nabertherm-furnaces.com)
-
EMA Indutec (Germany) — Focused on induction hardening for automotive and industrial components, emphasizing repeatability at scale. ( https://www.ema-indutec.de)
-
EMAG Machine Tools (Germany) — Integrates hardening into machine-tool platforms, targeting firms that need tight upstream-downstream process coupling. ( https://www.emag.com)
-
Aages SA (Switzerland) — Induction hardening specialists for precision applications. ( https://www.aages.com)
-
Interpower Induction (UK) — Known for induction heating systems tuned to hardening use cases. ( https://www.interpowerinduction.com)
-
Maschinenfabrik Alfing Kessler (Germany) — Offers grinding-plus-hardening systems—appeals to integrated finishing workflows. ( https://www.alfing-essler.de)
-
GH Induction Atmospheres (Spain) — Focus on flexible induction solutions across multiple part families. ( https://www.gh-ia.com)
-
EFD Induction (Norway) — Vertical hardening machine lines designed for high‑consistency production, including the HardLine series. ( https://www.enrx.com)
-
Inductotherm Group / Inductotherm (US) — Global presence in induction heating systems; strong in aftermarket and service networks. ( https://www.inductotherm.com)
-
Ajax Tocco Magnethermic (US) — Emphasizes energy-efficient induction solutions and custom hardening cells. ( https://www.ajaxtocco.com)
-
SMS Elotherm, eldec Induction, SAET EMMEDI, Electroheat Technologies, Canroon, ULTRAFLEX, Ambrell — These firms represent a mix of modular systems, high‑volume production equipment, and innovative induction power electronics; their product choices and geographic focus create pockets of competitive advantage.
Collectively, the landscape rewards vendors that combine deep process know‑how, local service capabilities, and modular automation. The relatively low CR3/CR5 concentration underscores both the opportunity for consolidation and the advantage of nimble niche players.
Recent signals and external drivers to monitor
-
Exhibitions and product launches: Market signals from industry trade shows remain reliable leading indicators of product trajectories — for example, recent demonstrations of high‑throughput induction lines and large‑part vertical hardening solutions at European and North American trade events.
- Regulatory and standards movement: Standards that formalize requirements for induction hardening processes are influencing OEM supplier qualification and should be monitored closely as they can extend supplier qualification timelines and affect procurement contracts.
- Raw-material and energy context: Input-cost dynamics — such as European hot‑rolled coil steel prices — and energy policies are materially relevant to end customers’ demand timing and to vendors’ cost-of-goods assumptions.
- Decarbonization and energy security: Industry initiatives toward lower CO2 footprints favor induction technologies over fossil‑fuel furnaces, creating an operational and procurement rationale to prioritize modern induction systems in 2026 investments.
What PW Consulting’s full report delivers (high‑level)
The complete study is operational in design and intended for corporate strategy, procurement, and engineering leaders. Key inclusions are:
- Validated market sizing and forward projections (2026–2032) with scenario analysis and sensitivity to energy and raw‑material price paths.
- Technology deep dives that decode induction vs. furnace tradeoffs, control architectures, and retrofit pathways.
- Vendor landscape with comparative capability matrices, total cost of ownership templates, and aftermarket/service scoring.
- Procurement playbooks and qualification checklists, plus CapEx/Opex modeling tools to align procurement decisions with ESG and payback constraints.
- M&A and partnership playbooks identifying consolidation targets, integration risks, and revenue‑synergy estimates.
- Practical case studies capturing implementation pitfalls and success factors across representative end‑markets.
To respect the “trailer” objective of this preview, we intentionally withhold the full segmentation tables, granular regional and application shares, and the transaction‑level vendor benchmarking data — all of which are available in the full research package on our web portal.
Action recommendations for 2026
-
Align procurement cycles with energy and standards roadmaps: Prioritize units that demonstrably lower energy intensity and support emissions reporting to ensure faster internal approvals.
-
Buy modularity: Where feasible, favor modular or cell‑based hardening solutions to reduce installation time and to retain flexibility for future capacity or process changes.
-
Lock service agreements early: Given the fragmented supply base, secure multi‑year service contracts and spare‑parts terms at the point of purchase to mitigate downtime risk.
-
Pursue partnership pilots: Manufacturers should run short, rigorously instrumented pilot programs with selected vendors to validate process recipes before full‑scale procurement.
For executives preparing 2026 capital plans and strategic roadmaps, this preview should help prioritize questions, scenarios, and procurement criteria. PW Consulting’s full Hardening Machines Market report contains the detailed segmental data, vendor scorecards, and executable templates that will convert these insights into procurement-ready decisions. Reach out via our research portal to access the complete dataset and customized advisory engagement options.
For detailed analysis of this topic, please visit the official page: Hardening Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


