



PW Consulting: Albumin (as Excipient) Market Poised for 5.92% CAGR (2026–2032)

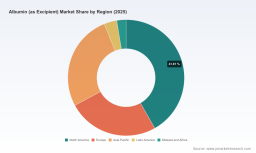
Albumin (as Excipient) Market — Strategic Briefing for 2026 Decision-Makers
As pharmaceutical and biopharmaceutical product portfolios expand in complexity, the role of albumin as an excipient has moved from a niche stabilizer to a strategic ingredient influencing formulation reliability, supply-chain resilience, and regulatory positioning. This PW Consulting briefing previews our full Albumin (as Excipient) Market study (base year 2025, historical 2020–2025, forecast 2026–2032) and explains why this analysis should sit on the desk of every executive making 2026 investment, sourcing, or M&A decisions.
Albumin (as Excipient) Market
Market snapshot — what the headline numbers tell you
-
Market trajectory: The albumin excipient market has expanded steadily, rising from approximately USD 747 million in 2020 to about USD 979 million in 2025. Our modelling projects a continuation of this expansion into 2026 and beyond, with the market passing the USD 1.04 billion mark in 2026 and reaching roughly USD 1.45 billion by 2032.
Albumin (as Excipient) Market -
Growth pace: A compound annual growth rate (CAGR) of ~5.9% across the 2026–2032 forecast window signals structural growth driven by biologics maturation, vaccine manufacturing scale-up, and increasing adoption of recombinant alternatives.
Albumin (as Excipient) Market -
Market structure: The sector is moderately concentrated — the top three suppliers account for roughly one third of the market, and the top five near half — creating a competitive environment where scale, regulatory credentials, and supply reliability materially affect pricing and access.
Why this report matters for 2026 strategic choices
-
Sourcing and procurement: Our analysis deciphers the trade-offs between plasma-derived and recombinant albumin in terms of availability, cost volatility, and supplier risk. This is essential for procurement teams designing multi-tier sourcing strategies or negotiating long-term offtakes.
-
Capacity and capex planning: For manufacturers and investors contemplating brownfield or greenfield builds, the report provides a decision framework that links expected product pipeline cadence with realistic lead times for albumin capacity expansion.
-
Formulation and product differentiation: R&D and CMC teams will find targeted guidance on when albumin inclusion delivers meaningful stability or delivery advantages versus alternative excipients — informing go/no-go formulation trade-offs ahead of pivotal trials.
-
Regulatory & market access: Policymakers and market-access teams get an evidence-backed roadmap for engaging regulators on sourcing constraints and substitution strategies, helping preserve launch timelines in jurisdictions sensitive to plasma supply disruptions.
-
M&A and partnership diligence: Our benchmarking, supplier scorecards, and scenario valuations sharpen acquirers’ ability to price targets that own plasma fractionation assets, recombinant platforms, or excipient-grade processing lines.
What you’ll find inside — practical, transaction-ready deliverables
-
Proprietary demand model (by therapeutic application and end-market scenarios) with sensitivity levers you can re-run under custom hypotheses.
-
Supply-side maps and capacity timelines highlighting chokepoints (plasma collection, fractionation throughput, recombinant bioprocess scale-up) and practical mitigation playbooks.
-
Supplier scorecards that synthesize GMP credentials, regulatory approvals, geographic resilience, and commercial readiness — arranged to support fast vendor selection without divulging confidential volumes.
-
Regulatory risk matrix and engagement templates designed to support dossiers and pre-submission interactions focused on excipient sourcing transparency.
-
Commercial scenarios and price-elasticity guidance calibrated to real-world procurement contracts, enabling sales and pricing teams to model margin impacts of supplier concentration and substitution.
-
Actionable playbooks for three archetypal buyers: (1) large integrated biopharma, (2) mid-sized biologics/contract developers, and (3) contract manufacturers / CDMOs — each with recommended near-term moves for 2026.
Competitive landscape — what the major players are doing and why it matters
-
Large plasma integrators (examples: CSL Behring, Grifols, Octapharma) retain advantage through integrated plasmapheresis networks and fractionation capacity. Recent public investments — including facility upgrades and capacity expansions — underscore the premium consumers place on supply assurance. For buyers, this translates into negotiating bandwidth: premium for guaranteed supply, or risk of exposure to substitution if premiums are declined.
-
Recombinant specialists and reagent suppliers (examples: InVitria/Ventria, Merck/Sigma-Aldrich, Sartorius, Albumedix) are accelerating adoption by providing animal- and blood-free alternatives with lower ethical and sourcing friction. These players have seen increasing acceptance in vaccines, gene therapies, and high-value biologic formulations — notably, recombinant albumin products have been dosed in the hundreds of millions of administrations and already support a substantial portion of the leading pharma cohort.
-
Regional producers and plasma product firms (examples: Baxter, Kedrion, Biotest, LFB, select Chinese producers) compete on cost, proximity, and regulatory alignment. Their role is pivotal in regional continuity plans, though they must continue investing in cGMP upgrades and traceability to win global contracts.
-
Market moves to watch (recent developments): Grifols’ announced production facility investment, Baxter’s digital supply-chain platform launch, and Octapharma’s strategic alliance to develop albumin-based therapies all highlight three near-term themes — capacity expansion, digitalization of logistics and traceability, and upstream product innovation via collaboration.
Industry dynamics and risk vectors — what keeps CFOs and CMC heads awake
-
Raw material & throughput constraints: Plasma availability and fractionation throughput materially constrain conventional Human Serum Albumin (HSA) manufacturing capacity. These constraints support resilient pricing and underline why buyers face a supply/price trade-off through the next decade.
-
Regulatory & geopolitical noise: Historical and ongoing plasma shortages in parts of Europe and elsewhere reinforce the need for contingency planning. Regulatory scrutiny focused on supply integrity and donor-sourced materials adds both cost and time to market for plasma-derived solutions.
-
Cost structure hurdles: High fixed and variable costs for both plasma-derived and recombinant manufacturing remain a headwind. This factor favors players with scale, vertical integration, or novel process economics that can compress costs without sacrificing compliance.
-
Recombinant adoption as a strategic lever: Recombinant albumin addresses ethical sourcing concerns and supply constraints, offering a credible substitution path in many use-cases. However, transition timelines, CMC comparability demands, and payer recognition vary by application, requiring bespoke migration plans.
Using this analysis to set 2026 priorities — recommended actions
-
Establish a dual-track sourcing policy: Combine long-term volumes under contract with plasma-integrated suppliers while qualifying recombinant alternatives as second-source or phased substitutes. Documentation and comparability studies should be initiated in 2026 if substitution is strategic.
-
Prioritize supply-chain digitization: Invest in visibility tools (lot-level traceability, predictive lead-time dashboards) to reduce contingency buffers without increasing stockholding costs. Early pilots with suppliers’ digital platforms can yield outsized resilience gains.
-
Targeted capex or M&A: If vertical integration into plasma collection or recombinant capacity aligns with your risk appetite, the next 12–24 months present acquisition windows where assets can be priced with clear upside from contracted demand assumptions.
-
Embed regulatory engagement early: Proactively align with regulators on substitution pathways for recombinant albumin and on excipient traceability standards — these dialogues shorten approval cycles and de-risk launches.
-
Advance formulation strategies: R&D and CMC should map which programs materially benefit from albumin inclusion and run accelerated stability comparability packages to lock excipient choices ahead of pivotal studies.
How PW Consulting’s study supports execution
-
Our full report supplies the granular datasets, scenario models, supplier scoring outputs, and commercial templates needed to operationalize the strategic moves above. The public brief you are reading intentionally omits confidential segmentation detail to protect client value — the full dataset unlocks the precise levers used in our client engagements.
-
For teams preparing procurement RFPs, M&A diligence, or CMC comparability plans in 2026, the study acts as a single-source-of-truth that combines macro forecasts with tactical playbooks, cutting due diligence timelines by weeks.
Concluding perspective — why act now
By 2026, albumin as an excipient will be more than a formulation choice — it will be a strategic axis for supply resiliency, regulatory positioning, and product differentiation. The moderate-growth trajectory (near 6% CAGR in our central forecast) masks meaningful asymmetries: capacity constraints, regulatory pressure, and recombinant adoption create pockets of acute risk and opportunity. Companies that define sourcing duality, invest selectively in traceable supply-chains, and engage regulators proactively will convert this structural change into competitive advantage.
PW Consulting’s full Albumin (as Excipient) Market report provides the data, scenarios, and executable playbooks required to make those 2026 decisions with confidence. For clients and shortlisted partners, we also offer bespoke workshops that translate the report’s insights into tailored procurement and R&D roadmaps. Contact the PW Consulting team to access the complete study and unlock the granular market segmentation, supplier analytics, and model-enabled scenarios underpinning these conclusions.
For detailed analysis of this topic, please visit the official page: Albumin (as Excipient) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


