



Trisenox Market to Hit USD 382 Million by 2032 at 8.5% CAGR — PW Consulting Insights

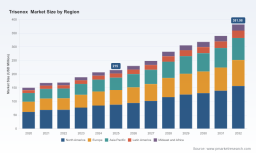
Trisenox Market 2026: Strategic Imperatives from PW Consulting’s Market Overview
As pharma and biotech leaders plan budgets and launches for 2026, a nuanced understanding of the Trisenox (arsenic trioxide) market is no longer optional — it is strategic. PW Consulting’s latest Trisenox Market study synthesizes historical performance, driver-level dynamics, competitive posture and forward-looking scenarios to convert macro signals into actionable choices. This preview outlines the report’s value to decision-makers, highlights the critical market dynamics through 2032, and signals where first-mover advantage will accrue — while intentionally withholding proprietary segment tables to encourage direct access to the full report.
Trisenox Market
Market trajectory: clarity where it counts
Fundamental market metrics show a resilient growth path. Using 2025 as the base year, the Trisenox market expanded from an estimated USD 150 million in 2020 to approximately USD 215 million by 2025, and our modeling projects continued expansion through the 2026–2032 forecast period at a compound annual growth rate (CAGR) of roughly 8.5%. By the end of the forecast horizon, the global market is projected to approach the high hundreds of millions (USD ~382 million in 2032 under the base scenario). Near-term momentum is visible in 2026 estimates that place the market north of USD 230 million, reflecting both durable clinical demand and ongoing shifts across pricing, manufacturing and therapeutic paradigms.
Trisenox Market
What these macro numbers mean for 2026 decision-making
- Revenue planning must account for divergent forces. Base growth is solid, but upside and downside scenarios diverge depending on competitive entry (generics and novel oral formulations), payer stance and manufacturing continuity. Financial plans that assume linear growth will misestimate both upside opportunity and downside risk.
- Margin compression is a credible near-term threat. The emergence and market penetration of lower-priced generics, which industry trackers indicate are materially discounted versus branded Trisenox, increases the probability of pricing-led share shifts and squeezes realized prices unless differentiated value is demonstrable to payers and providers.
- Lifecycle innovations can swing category economics. Oral arsenic formulations advancing through expedited regulatory pathways represent a classic disruption vector: easier administration plus improved patient convenience can re-reference standard-of-care economics and channel dynamics.
Competitive landscape: fragmented, competitive, and strategically active
The Trisenox market is characterized by a modest concentration profile — the leading firms do not dominate in the way seen in some specialty biologics. This fragmentation creates both opportunities and operational headaches:
Trisenox Market
- Incumbent brand holders retain label clarity and manufacturing provenance — Teva Pharmaceuticals remains the named manufacturer for the branded Trisenox product, which supports brand recognition and established formulary positions.
- Multiple generic manufacturers have active arsenic trioxide injection introductions, increasing pricing pressure and channel complexity. Large contract manufacturers and specialty injectables players supply clinically equivalent presentations, and some producers market multiple concentration formats, which matters for hospital procurement and dosing logistics.
- Low aggregate concentration (a CR3 in the low double digits and a CR5 only marginally higher) signals a marketplace where competitive tendering, volume-based contracting and localized sourcing decisions are routine. For commercial teams, that environment necessitates playbooks tailored to both national procurement and institutional formulary processes.
Regulatory, reimbursement and manufacturing dynamics to watch
- Regulatory acceleration for oral arsenic: An oral arsenic trioxide candidate received Fast Track designation in early 2026 and has advanced into late-stage testing. If approved, an oral option could reshape outpatient administration patterns and exert pricing pressure on intravenous presentations.
- Reimbursement backbone: Medicare-level coverage policies have been updated to include Trisenox and approved generics, reducing payer uncertainty in key markets. This coverage clarity is a double-edged sword: it supports baseline demand but also enables aggressive formulary competition among suppliers.
- Manufacturing and supply resilience: Leading suppliers produce multiple concentration formats, which influences hospital purchasing and cold-chain logistics. Continuity of API supply and validated manufacturing lines are immediate risk points for any player relying on tight inventory turns.
- Pricing delta between brand and generics: Market intelligence consistently shows generics priced substantially below the branded product. For branded owners and originators, this implies that commercial strategies must shift from price-based defense to outcomes and access-based differentiation.
Strategic playbook: five near-term priorities for 2026
PW Consulting’s scenario work and stakeholder interviews point to five imperatives that should inform boardroom decisions in 2026:
- Reframe value beyond price. Invest in real-world evidence (RWE) initiatives that demonstrate downstream cost offsets — e.g., shorter hospital stays, reduced infusion-related resource use, or improved adherence in specific regimens — to underpin higher net prices or preferred formulary placement.
- Hedge supply via dual-sourcing and fill-finish flexibility. Given the concentration of small manufacturers and the operational complexity of injectables, establish backup API agreements and secondary fill-finish relationships to minimize disruption risk.
- Prepare for oral competition with differentiated clinical narratives. Model adoption curves for a potential oral entrant and build contingency plans (e.g., bundled services, patient support programs) that can blunt outpatient migration.
- Segment go-to-market by decision-maker. Hospitals, oncology networks and national payers make different trade-offs. Tailored engagement — from tender tactics for procurement teams to outcomes contracts for payers — will outperform one-size-fits-all approaches.
- Pursue selective inorganic moves. M&A and licensing can be efficient ways to secure scale, API access or novel formulations. Target assets that fill delivery or cost gaps rather than chasing marginal volume additions.
Report deliverables: what’s inside the full PW Consulting study
This market briefing is a condensed window into the full study, which provides the granular deliverables executives need for decision-making in 2026:
- Comprehensive market sizing and a year-by-year forecast (2026–2032) with scenario-specific runways and sensitivity testing.
- Competitive intelligence dossiers on branded and generic manufacturers, including capability maps, commercial footprints and manufacturing capacity assessments.
- Payer and reimbursement mapping at national and institutional levels, with negotiation playbooks and modeled reimbursement outcomes under alternative contracting strategies.
- Supply chain and API risk-maps: single-point-of-failure identification, mitigation options and cost-to-implement estimates.
- Regulatory and pipeline tracker, integrating expedited pathways, trial milestones and potential market-access timing for oral and novel formulations.
- Commercial readiness checklists, launch playbooks and payer contracting templates designed for rapid operationalization.
- Appendices containing the underlying datasets, modeling assumptions, and detailed scenario outputs for internal stress-testing.
How competitors are likely to act — and how you should respond
Given the mix of branded incumbency and broad generics supply, the next 12–18 months are likely to see:
- broader tender activity and price-led contracting in hospitals;
- continued margin pressure on IV presentations as generics expand penetration; and
- early adopters evaluating oral arsenic options if phase outcomes validate non-inferiority plus convenience benefits.
For organisations with branded exposure, the recommended response package combines evidence-generation (to protect price), targeted contracting (to secure preferred access) and operational resiliency (to guarantee supply). For generics suppliers, scale and service differentiation — such as consistent multi-dose presentations and institutional logistics support — will be decisive.
Final strategic takeaway
The Trisenox category will not be static in 2026: it sits at the intersection of clinical innovation, pricing friction and manufacturing complexity. The market’s steady baseline growth (an 8.5% CAGR over the forecast window, with the global market growing from a mid-three-figure USD million base in 2025 to materially higher levels by 2032) hides important structural choices for companies. Firms that translate the macro trajectory into operational priorities — RWE investment, supply redundancy, payer-centered contracting and preparation for oral competition — will shape who captures disproportionate value.
This article is a concise executive preview. PW Consulting’s full Trisenox Market report contains the detailed breakdowns, scenario models, competitor scorecards and operational templates that boards and commercial teams require to convert insight into execution. Accessing the full dataset and confidential annexes will allow you to move from strategic intent to tactical commitment with confidence.
For detailed analysis of this topic, please visit the official page: Trisenox Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


