



PW Consulting: Infant Incubator Market at USD 674.62M in 2025, Poised for 6.08% CAGR

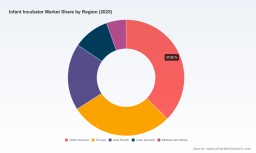
Infant Incubator Market: Strategic Intelligence for 2026 Decision-Making
As health systems, device manufacturers, and investors plan for the post‑pandemic reconfiguration of perinatal care, the infant incubator market presents a stable, mid‑growth opportunity anchored in clinical necessity and regulatory modernization. Our PW Consulting market study — grounded in a 2025 base year and covering historical trends from 2020–2025 with forecasts to 2032 — quantifies that trajectory and, more importantly for 2026 planning horizons, translates it into actionable choices. The global market size at the 2025 base is a robust indicator of installed demand, and our scenario workpoints show the market growing at a compound annual growth rate (CAGR) of approximately 6.08% into the forecast period, with a clear pathway toward a billion‑dollar market by the early 2030s.
Infant Incubator Market
Why this research matters for 2026
-
Timing: Regulatory milestones and public capital allocations in 2024–2026 create procurement windows and replacement cycles that will shape ordering patterns for the next 24 months.
Infant Incubator Market -
Margin levers: Device manufacturers face concentrated buyer power in high‑income markets, but there is significant room to capture value through service, software, and hybrid product strategies.
Infant Incubator Market -
Investment clarity: For private equity and strategic investors, the market’s stable CAGR and moderate concentration profile suggest predictable returns when coupled with disciplined commercial execution.
Market at a glance
Our base‑year analysis synthesizes historical demand (2020–2025) and quantitative forecasts (2026–2032). The market recorded steady recovery through 2024–2025 as elective maternity services stabilized and capital budgets normalized. Under our central scenario — incorporating regulatory-driven replacement cycles and incremental adoption of advanced monitoring — the market expands at ~6.08% CAGR across the forecast horizon. From a practical planning perspective, that means procurement teams and OEMs should expect consistent year‑on‑year demand growth rather than sporadic spikes, enabling multi‑year contracting and predictable manufacturing ramp plans.
Key dynamics shaping 2026 decisions
-
Regulatory clarifications reduce operational friction. In the U.S., a November 2025 FDA determination removed a prior practical barrier by confirming that new incubators in current supply do not require a week‑long pre‑use airing protocol, shortening the time to clinical deployment.
-
National standards and replacement mandates accelerate turnover in developed markets. Several European and North American directives and national policies enacted between 2023 and 2026 are driving replacement of legacy units, particularly where integrated monitoring and data export are now mandatory in high‑acuity NICUs.
-
Public investments and infrastructure funds are increasing capital availability for neonatal care upgrades. Hospital modernization programs in multiple jurisdictions have prioritized neonatal units, improving the probability of funded capital cycles in the immediate term.
-
Product diversification: the competitive mix spans conventional closed incubators, hybrid designs with integrated monitoring, and transport‑grade devices. Manufacturers that combine clinical ergonomics with connectivity and low lifecycle cost are positioned to outpace product‑only competitors.
Regulatory and market events to watch
-
Recent regulatory events have direct procurement implications: national health agencies and regulators have published guidance and post‑market reviews that identify cleared device lines and set safety expectations. This includes high‑visibility reviews by regulatory bodies in 2024–2025 that list devices from major vendors and, in early 2026, a significant 510(k) clearance for a portable thermoregulation device that reinforces the demand for mother‑centered, bedside‑friendly solutions.
-
Infrastructure grants and mandates are creating concentrated windows where hospitals must align purchases with updated safety standards — a strategic lever for vendors who can demonstrate compliance and fast delivery.
Pricing and procurement realities
Unit pricing remains an important determinant of adoption paths. Typical neonatal incubator list prices fall into an accessible mid‑market range (broadly characterized between low five figures and upper five figures in USD), but total cost of ownership (TCO) — including service, consumables, software subscriptions, and training — is where procurement negotiates meaningful value. Our study provides procurement playbooks and TCO models designed to help hospital systems structure multi‑year agreements that mitigate obsolescence risk while aligning vendor incentives toward uptime and outcomes.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three manufacturers represent a substantial share of market revenues, and the top five control a clear majority. That structure rewards scale in regulatory compliance, global distribution, and clinical evidence generation, while leaving niches for agile players who can innovate on portability, maternal‑infant bonding features, or low‑resource suitability.
-
GE HealthCare (Chicago) — recognized for integrated incubator‑carestation solutions emphasizing thermal performance and monitoring.
-
Drägerwerk AG & Co. KGaA (Lübeck) — offers the Babyleo series, notable for ergonomic neonatal designs and clinical workflows.
-
Koninklijke Philips N.V. (Amsterdam) — brings neonatal incubators as part of broader neonatal care ecosystems and patient monitoring platforms.
-
Atom Medical (Tokyo), Bistos (Seoul), International Biomedical (Hong Kong), mOm Incubators (UK), and several Chinese OEMs (including CNMEDITECH, YSENMED, WEGO) — together these firms compete across price, portability, and regional distribution vectors.
-
Natus Medical (San Carlos) — known for neonatal care solutions with a focus on clinical accuracy and integration with diagnostic systems.
Each competitor brings distinct advantages — from channel reach and clinical relationships to specific product innovations. Our vendor scorecards evaluate these dimensions across regulatory footprint, product breadth, service network, and interoperability capabilities, enabling buyers to shortlist partners for fast‑track procurement or long‑term strategic sourcing.
What the PW Consulting report delivers (practical outputs)
-
Market sizing with scenario modeling: baseline and upside/downside scenarios through 2032 with sensitivity to replacement mandates and capital fund disbursements.
-
Commercial playbooks: go‑to‑market strategies by segment (hospital procurement, private clinics, low‑resource settings), pricing tactics, and channel optimization recommendations.
-
Procurement toolkits: RFP templates, TCO calculators, and upgrade/retirement decision matrices hospitals can deploy immediately.
-
Vendor scorecards and negotiation levers: comparative profiles of the market’s leading suppliers with documented strengths, risks, and partnership archetypes.
-
Clinical adoption roadmaps: evidence generation and change management plans for integrating incubator upgrades into neonatal workflows while minimizing service downtime.
Strategic implications and recommended actions for 2026
-
For device manufacturers: prioritize modularity and data export features to align with regulatory replacement requirements in high‑income markets. Invest selectively in service networks and remote diagnostics to shift revenue mix toward higher‑margin recurring services.
-
For hospital systems and group buyers: exploit predictable growth and regulatory windows to negotiate volume agreements that include upgrade credits and outcome‑based service clauses. Use our TCO tools to compare long‑term value, not just list price.
-
For investors: target bolt‑on acquisitions that add connectivity, consumables, or aftermarket services to an OEM’s portfolio. The market’s moderate concentration creates opportunities for consolidation with clear operational synergies.
-
For policymakers and funders: align capital disbursements with clinical training and maintenance funding to ensure that new acquisitions translate into improved neonatal outcomes rather than under‑utilized assets.
How to use this research in your 90–180 day plan
-
Operational leaders: deploy the procurement RFP templates in Q1 and leverage the vendor scorecards to reduce shortlist time by up to 40%.
-
Commercial teams at OEMs: run the report’s scenario playbooks through your sales forecasting to adjust production planning and spare‑parts inventory levels for 2026.
-
Investors and M&A teams: apply the market concentration analysis and company profiles to refine target screening and valuation models before committing to diligence.
Final note — what we deliberately withhold here (and why)
In this introduction we have highlighted the strategic contours, regulatory triggers, and competitive dynamics that will govern buying and investment decisions in 2026. Consistent with our “trailer” approach, we have intentionally not published the report’s granular regional and application split tables or the full vendor scoring matrices in this summary. These detailed segmentations, price‑benchmark tables, and procurement playbooks are included in the full study and are the actionable assets your team will need to execute contracts, align manufacturing, or structure investments.
To convert the macro insights above into deal‑ready tactics — specific regional demand forecasts, product‑level revenue breakdowns, procurement templates, and vendor negotiation scripts — consult the full PW Consulting Infant Incubator Market report. It contains the operative detail that procurement officers, commercial leaders, and investors require to move from strategy to execution in 2026.
For detailed analysis of this topic, please visit the official page: Infant Incubator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


