



PW Consulting: Soy Protein Market to Reach USD 344.8 Million by 2032 at 6.7% CAGR

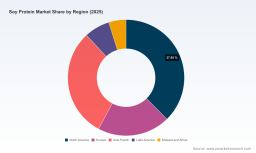
Soy Protein Market 2026: Strategic Preview for Executive Decision-Making
Executive snapshot
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a strategic preview of our comprehensive Soy Protein Market study — a decision-grade briefing designed for commercial leaders preparing plans in 2026. Anchored to a 2025 base year (with historical context from 2020–2025 and forward-looking projections through 2032), the market demonstrates sustained expansion at a mid-single-digit compound annual growth rate (CAGR) of 6.7%. Our topline model places the global soy protein market on a growth trajectory from a 2025 baseline to materially higher values by 2032, a trajectory that creates discrete windows for capacity investment, product innovation, and supply-chain repositioning.
Soy Protein Market
Why this matters for 2026 planning
2026 will be a pivot year for many players in the soy protein ecosystem: ingredient buyers, co-manufacturers, branded food companies, and feed formulators. The market’s steady CAGR signals durable demand, but the near-term landscape is characterized by structural supply dynamics, regulatory shifts, and concentrated industry power. Companies that treat 2026 as a year to operationalize resilience — through diversified sourcing, targeted partnerships, and flexible product platforms — will materially improve their competitive positioning as the cycle progresses toward 2032.
Soy Protein Market
Market trajectory — the headline view
Our longitudinal analysis (2020–2025) and scenario-driven forecasts (2026–2032) show a consistent expansion in aggregate market value, underpinned by three durable demand themes: protein-forward human nutrition, growth in formulated animal feeds, and the accelerating adoption of plant-based alternatives. The market’s underlying momentum is captured by the 6.7% CAGR embedded in our forecast framework and reinforced by reported capacity investments and strategic moves among major producers throughout 2024–2025.
Soy Protein Market
Supply-side dynamics and risk vectors
-
Raw material volatility: Soybean meal price swings in early 2025 — driven by uneven demand and macroeconomic uncertainty — translated immediately into cost pressure for isolate producers. Procurement teams should expect episodic pricing dislocations rather than a smooth cost curve.
-
Agronomic base and trade policy: The U.S. harvest footprint reported in 2025 provided a stabilizing supply signal for processors, and the October 2025 trade framework eased certain tariff frictions that had elevated import risk. Nonetheless, trade policy will remain a tactical variable for global sourcing strategies.
-
Alternative demand on co-products: Continued increases in biodiesel blending under renewable fuel mandates have tightened meal availability for protein extraction in some markets, creating periodic upstream supply compression that can amplify lead times and margins.
-
Regulatory shifts in key consuming markets: Policy moves to moderate soybean meal inclusion rates in certain feed markets are altering the composition of downstream demand and accelerating interest in concentrated, functional protein ingredients for human and pet nutrition applications.
Competitive landscape — who matters and why
The soy protein market exhibits meaningful concentration at the top: our concentration metrics indicate that the largest three suppliers account for a majority share, and the top five increase that dominance further. For incumbents and challengers alike, this creates a two-track reality — global scale matters for raw-material integration and logistics, while niche specialization wins in high-growth formulated segments.
-
Archer Daniels Midland Company (ADM) — With a recent major expansion to consolidate crush and extraction operations, ADM is prioritizing integrated scale and margin control. Their portfolio depth and channel reach make them a default partner for food manufacturers seeking secure, large-volume supply and broad functional variants.
-
Bunge Global SA — Bunge’s new large-scale concentrate facility inaugurated in late 2025 underscores a strategy focused on premium concentrate supply and geographical flexibility. Investment in scalable plants tightens competition for spot supply and enables branded customers to lock in longer-term offtake arrangements.
-
International Flavors & Fragrances (IFF) — As a supplier with specialty brands geared toward beverage and alternative-protein applications, IFF competes on formulation expertise and ingredient systems rather than purely on commodity scale. This positioning is attractive to CPG teams seeking tailored sensory and stability outcomes.
-
Cargill — Cargill’s bulk distribution network and experience in textured proteins make them a go-to for industrial food manufacturers and large feed formulators. Their strength lies in logistics and broad application support.
-
Regional and specialty manufacturers — Companies based in Asia, India, Brazil, and elsewhere (including Solbar Ningbo, AOS Products, Wilmar, and select Chinese manufacturers) remain critical to regional supply chains and niche product innovation. These players often offer competitive cost structures and faster time-to-market for localized applications.
Strategic implications by function
-
Procurement and supply management: Move beyond single-source contracting. Where possible, secure staggered capacity through blended contracts (strategic + spot) and include cost-pass-through or indexation clauses tied to feedstock indices to reduce margin erosion during raw-material volatility.
-
R&D and product development: Prioritize formulation platforms that exploit functional attributes (solubility, emulsification, texture) rather than competing on raw protein content alone. Investment in co-processing and co-blend capabilities will unlock adjacent applications, particularly in plant-based meat and nutrition bars.
-
M&A and partnership strategy: Given the market concentration and the ongoing capacity additions by large players, selective bolt-on acquisitions — targeting specialty ingredient lines, regional processing footprints, or formulation IP — can accelerate market entry without bearing the full cost of greenfield builds.
-
Commercial go-to-market: Differentiate on application know-how and co-creation, especially in higher-margin beverage and premium nutrition segments. For commodity channels, favor longer-term supply agreements that include technical service and quality guarantees.
What our full report delivers (operationally focused)
PW Consulting’s full Soy Protein Market study provides a toolkit tailored for 2026 decision cycles, combining rigorous forecasting with execution-ready deliverables. Highlights include:
-
Proprietary market model (2020–2032) with scenario branches for supply shock, accelerated demand, and policy disruption; configurable for client-specific volume and price inputs.
-
Supplier scorecards and heatmaps evaluating scale, product breadth, geographic exposure, and margin sensitivity — enabling rapid shortlist creation for procurement teams.
-
Workbooks and playbooks for procurement clauses, hedging approaches, and dual-sourcing designs — built to be embedded into 2026 sourcing RFQs.
-
Go-to-market frameworks for ingredient manufacturers and co-packers, including customer-segmentation matrices, value-proposition templates, and sample commercialization timelines.
-
Risk register and mitigation matrix covering raw-material, regulatory, logistical, and climate-related vectors with prioritized actions and estimated lead times to implement.
Scenarios to stress-test strategy in 2026
We recommend clients run three pragmatic scenarios during 2026 planning:
-
Base case: Markets expand in line with our central 6.7% CAGR forecast — use this to size optimal production and inventory buffers.
-
Upside case: Faster adoption of plant-based foods and premium nutritional formulations accelerates demand, favoring specialty isolates and branded ingredient strategies.
-
Stress case: Raw-material diversion to biofuels and episodic trade disruptions compress availability, creating short-term premiums; companies with flexible sourcing and integration capture outsized margins.
Final recommendations — a 90-day action agenda for C-suite teams
-
Immediate (0–30 days): Map contracted supply versus forecasted demand through 2027; activate alternative supplier dialogues where single-sourced dependencies exist.
-
Near-term (30–90 days): Finalize one pilot co-development with a specialty supplier focused on functional improvement (e.g., solubility, clean label) and run a commercial viability assessment for premium pricing tiers.
-
Strategic (90+ days): Re-evaluate capital allocation against potential M&A or JV opportunities, particularly where regional players provide faster access to growth markets or distinct product IP.
Closing note — the value of granular intelligence
The summary above provides a curated strategic orientation — enough to inform immediate planning choices and to surface priority questions for leadership. Our full Soy Protein Market report contains the granular segment breakdowns, regional and application level modeling, supplier-level financials, and price-volume tables that procurement and strategy teams need to operationalize the recommendations. In a market where scale, specialty, and supply resilience intersect, that granular intelligence converts insight into measurable advantage.
To access the full dataset, detailed segment analysis, and the decision playbooks designed for 2026 implementation, please refer to the PW Consulting Soy Protein Market report landing page.
For detailed analysis of this topic, please visit the official page: Soy Protein Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


