



PW Consulting: IoT Sensors Market to Hit USD 1,154.0 Million by 2032 at 28.9% CAGR

IoT Sensors Market — Strategic Preview for 2026 Decision-Making
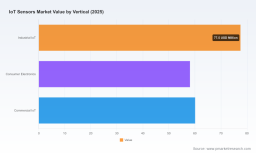
By the close of our base year (2025), the IoT sensors market had evolved from a niche instrumentation play into a broad platform opportunity. Measured on the same revenue unit basis used throughout this study, the sector expanded from roughly USD 110.2 million in 2020 to USD 195.7 million in 2025. Our forecast shows the market accelerating into the next decade — an anticipated rise to approximately USD 256.9 million in 2026 with a compounded annual growth rate (CAGR) of 28.9% over the 2026–2032 period and a projected market size nearing USD 1,154.0 million by 2032. These headline numbers frame a classic scale inflection: rapid adoption, widening use cases, and a shift from point sensors to sensor-driven business models.
IoT Sensors Market
Why this study matters for 2026 strategy
-
Timing: 2026 is the first full post-policy year where new reimbursement and regulatory expectations materially change commercial economics. Leaders who reposition now capture outsized share when market adoption accelerates.
IoT Sensors Market -
Risk management: The recent regulatory focus on device cybersecurity and AI/algorithm transparency creates both compliance costs and differentiation opportunities. Our analysis quantifies likely remediation effort and maps it to product roadmaps.
IoT Sensors Market -
Commercial models: With sensor data increasingly billable and platform-enabled services gaining traction, product teams must decide whether to compete on hardware, software, connectivity, or bundled services. The study lays out revenue implications for each choice.
-
Competitive posture: Fragmentation at the vendor level creates buy/rent/partner dilemmas. We translate market concentration metrics into practical M&A and partnership scenarios for 2026 planning.
Key macro forces that will shape boardroom decisions in 2026
-
Regulatory tightening on cybersecurity and AI: The U.S. FDA’s 2025 cybersecurity guidance and subsequent safety communications heightened expectations for threat modeling, vulnerability management, and secure update mechanisms in connected devices. In early 2026 the agency updated guidance for digital health and AI-enabled devices, increasing requirements around transparency, validation, and post-market performance surveillance for sensor-based systems. Executives must budget for continuous security and validation workstreams rather than one-time certification projects.
-
Reimbursement becomes a practical accelerator: The 2026 CPT updates (notably the addition of codes for remote physiologic monitoring and interactive management) materially improve the commercial viability of sensor-driven remote monitoring services. These codes create an immediate pathway to monetization for products that can demonstrate clinical utility and billing-compliant data pipelines.
-
Platform commoditization vs. value capture: As connectivity modules, edge compute, and low-power sensors mature, margins on commodity components compress. Value shifts to clinical validation, data orchestration, and decision-support algorithms — areas where regulatory scrutiny is also increasing.
-
Convergence of verticals: Healthcare, industrial, and consumer use cases are sharing common technology building blocks (low-power wireless, federated learning, secure OTA). Cross-industry incumbents have a chance to repurpose assets — but only if they can meet domain-specific compliance hurdles.
Competitive landscape — who’s shaping the market and how
-
Medtronic (Dublin) — With deep experience in implantables and clinical workflows, Medtronic’s IoT strategy centers on tightly integrated device-cloud-clinician pathways. Strengths: clinical credibility, installed base, regulatory sophistication. Risks: device lifecycle complexity and the need to retrofit legacy products to newer cybersecurity and AI-validation standards.
-
Abbott Laboratories (Chicago area) — Abbott’s leadership in continuous glucose monitoring and wearable biosensors positions it to monetize chronic care pathways. Strengths: clear reimbursement pathways and real-world evidence. Risks: competition on data platforms and margin pressure as hardware matures.
-
Dexcom (San Diego) — A specialist in sensor-to-cloud glucose monitoring, Dexcom illustrates the pure-play advantage: rapid iteration, tight clinical feedback loops, and a software-driven revenue mix. Strategic challenge: expanding beyond core indications without diluting clinical focus.
-
Koninklijke Philips N.V. (Eindhoven) — Philips’ breadth across hospital and home-care monitoring gives it an integrator role. Its playbook emphasizes system-level partnerships with providers and payers. Execution depends on demonstrating end-to-end security and AI explainability at scale.
-
OMRON Healthcare (Kyoto) — OMRON’s patient-facing monitoring devices and remote connectivity highlight the consumer-to-clinic transition. Opportunities lie in hybrid reimbursement models and partnerships with telehealth platforms.
-
Boston Scientific (Marlborough) — Implantable sensors and cardiac monitors are a high-barrier niche where Boston Scientific competes on long-term safety data and integration into clinical decision pathways.
-
iRhythm Technologies (San Francisco) — Focused on patch-based cardiac event detection, iRhythm exemplifies a subscription-based analytics model tied to a diagnostic sensor. Key to scale: demonstrating superior diagnostic yield and efficient reimbursement workflows.
-
Vital Connect (San Jose) — Body-area sensor networks for continuous vital monitoring present opportunities in acute-care settings. Adoption will depend on interoperability with hospital systems and meeting stringent device security requirements.
-
Sensirion (Stafa) — As a medical-grade sensor IP provider, Sensirion’s role is upstream but strategic — supplying sensors validated for clinical use in ventilators, inhalers, and infusion systems. Suppliers like Sensirion will be pivotal partners for device OEMs facing accelerated compliance requirements.
-
Telit (Trieste) — Specializing in connectivity modules and IoT platforms, Telit’s differentiation is enabling data transport and lifecycle management. The company is essential to go-to-market speed for vendors lacking in-house connectivity expertise.
Market concentration is informative: our CR3 and CR5 metrics indicate a market that remains relatively unconsolidated (CR3 ~25.5%; CR5 ~29.8%). That fragmentation suggests continued opportunity for specialized challengers, vertical integrators, and roll-up strategies — provided they can meet regulatory and reimbursement barbs.
What the full report contains — practical deliverables
-
Actionable market-sizing and three scenario forecasts (base, upside, downside) with sensitivity analysis to regulatory and reimbursement shocks.
-
Technology deep-dives covering sensing modalities, power-management trade-offs, edge vs. cloud processing, and data annotation practices required for clinical-grade AI.
-
Regulatory & reimbursement playbook mapping requirements by jurisdiction and product archetype (including impacts from recent FDA and CMS updates).
-
Competitive intelligence dossiers for leading and emerging vendors, with capability matrices and likely near-term moves.
-
Go-to-market roadmaps: partner vs. build decision frameworks, pricing archetypes (hardware, software, subscription), and sample contract models aligned to CPT-based reimbursement.
-
M&A and partnership candidate list, including acquisition price heuristics, integration risk checklists, and synergies modeling.
-
Playbooks for clinicians, payers, and procurement teams to accelerate adoption and to measure clinical-economic outcomes.
Practical strategic moves for executives in 2026
-
Recalibrate R&D budgets to include continuous security and AI-validation pipelines. Treat these as product features with scheduled investment, not one-off compliance costs.
-
Map product roadmaps to the new reimbursement codes: prioritize early wins where clinical workflows and billing pathways already exist.
-
Pursue platform partnerships: pair sensor hardware with proven connectivity and analytics providers to shorten time-to-billable-service.
-
Consider hybrid commercial models (hardware subsidy + data subscription) to lower customer acquisition friction while building recurring revenue.
-
Invest in real-world evidence generation to meet payer and regulator expectations — digital trials and pragmatic studies will unlock coverage faster than bench data alone.
-
Develop a targeted M&A playbook: prioritize capabilities that mitigate regulatory burden (secure OTA, validated AI modules) or accelerate access to payers and provider channels.
How to use this preview and next steps
This article is a strategic preview designed to frame 2026 decisions. The full PW Consulting study provides the granular segmentation, vendor scorecards, and financial models that senior teams use to finalize budgets, prioritize product roadmaps, and structure deals. If your organization is defining 2026 resource allocation, product-market fit, or M&A strategy, the full report and follow-on briefings will convert the macro trends outlined here into executable steps tailored to your capability set and risk appetite.
Execution windows are short. The intersection of new reimbursement mechanics and tightening regulatory expectations creates a narrow period where early movers can set standards, lock in provider relationships, and define payer-accepted value. For executive teams willing to operationalize the changes above, 2026 is not just another planning year — it is a platform-defining year.
For detailed analysis of this topic, please visit the official page: IoT Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


