



PW Consulting: DBM Market Set to Expand at 6.6% CAGR to 2032

Demineralized Bone Matrix (DBM) Market: Strategic Intelligence for 2026 Decision-Making
As healthcare systems recalibrate after a period of procedural disruption, the Demineralized Bone Matrix (DBM) market is entering a phase of sustained, clinically driven expansion. Our PW Consulting market model—anchored to 2025 as the base year—estimates the global DBM market at approximately USD 1,540 Million in 2025, growing at a compound annual growth rate (CAGR) of 6.6% across the 2026–2032 forecast window, and reaching an anticipated market size near USD 2,400 Million by 2032. For leaders preparing capital allocation, product roadmaps, and go-to-market plays in 2026, these headline metrics are a starting point; the decisive competitive moves will be made on the basis of segmentation, channel economics, regulatory posture, and clinical evidence—areas we analyze in depth in the full report.
Demineralized Bone Matrix (DBM) Market
Why this market matters for 2026 strategy
-
Clinical momentum: DBM’s biological profile—osteoconductivity with retained osteoinductive proteins—continues to support broader adoption across spine, dental, trauma, and reconstructive indications. Incremental gains in procedural volumes, coupled with refinements in carrier systems and handling formats, are expanding clinical use-cases beyond traditional niches.
Demineralized Bone Matrix (DBM) Market -
Product-format differentiation: Putty, gels, fibers and composite constructs are no longer interchangeable commodities. Surgeon preference, handling characteristics, and evidence for fusion and defect-healing outcomes distinguish winners from laggards.
Demineralized Bone Matrix (DBM) Market -
Concentration and competitive dynamics: The DBM landscape exhibits meaningful concentration—our competitive analysis shows that the top three and top five suppliers capture a substantial portion of market volumes—creating both barriers and opportunities for scale players and focused challengers.
What the PW Consulting report delivers (practical, transaction-ready content)
-
Validated market size and forward-looking forecast model (2020–2032) with scenario toggles for reimbursement sensitivity and regulatory shocks.
-
Segmentation granularity by product format, clinical application, and geography, linked to price/volume drivers and margin benchmarks (note: segment-level tables and modeled revenue streams are available in the full deliverable).
-
Competitive intelligence dossiers for leading suppliers, including product portfolios, manufacturing footprint, tissue-bank partnerships, and near-term strategic options.
-
Regulatory and reimbursement maps outlining device versus 361 pathways, payer landscape, and coding/reimbursement risk assessments tailored for the U.S., Europe, and select APAC markets.
-
Clinical evidence compendium and HEOR templates to support value dossiers, coverage submissions, and hospital contracting conversations.
-
Commercial playbooks: channel segmentation, KOL engagement frameworks, pricing and tendering tactics, and capability-building checklists for clinical education and sales operations.
-
M&A and partnership screening tool: acquisition targets across the value chain (tissue processors, niche innovators in 3D/bioprinting, carrier technology developers) prioritized by strategic fit and integration risk.
Competitive landscape — what to watch from leading players
-
AlloSource — A primary producer with an established DBM portfolio and deep tissue-bank integration. Strengths include established clinical relationships and product breadth that facilitate hospital formularies; watch for vertical integration moves or OEM partnerships that extend reach into regional accounts.
-
LifeNet Health — Technological differentiation via proprietary processing technologies (e.g., PAD demineralization) and a long track record of allograft processing. Their scale in tissue processing and claims of robust safety outcomes create barriers for competitors that lack similar supply-chain control.
-
Musculoskeletal Transplant Foundation (MTF) — Positioning emphasizes reliability and legacy processing for spine and extremity uses. MTF’s strengths are trust and clinical adoption in institution-level purchasing; strategic options include co-development with OEMs to broaden product form factors.
-
ZimVie — Focused capability in dental and orthopedic particulate DBM via controlled manufacturing processes. Dental channel specialization is a differentiator and a model for targeted commercial segmentation.
-
SeaSpine — Fiber and strand technologies positioned for spine fusion. Product engineering and clinical evidence at the surgeon level underpin adoption in specialty practices.
-
Arthrex — Broad format portfolio (putty, gel, paste, fibers, sponges) coupled with global commercial reach. Arthrex’s advantage is the combination of product breadth and deep clinician training channels.
-
NuVasive & Globus Medical — OEMs integrating DBM into system-level spine solutions; their strategic play is embedding biologics inside broader implant ecosystems to secure share-of-procedure economics.
-
Ossifix, Essent Biologics, Orthofix — Niche and innovation-oriented challengers: from advanced formulations for orthopedic repair to DBM tailored for 3D bioprinting and tissue engineering. These firms are high-priority M&A or licensing targets for incumbents seeking next‑generation assets.
Regulatory, compliance and reimbursement dynamics
-
Regulatory distinction: Products combining DBM with certain carriers may be regulated as devices by the FDA’s CDRH, while pure DBM commonly follows section 361 tissue regulation. This bifurcation materially influences development timelines, clinical data requirements, and labeling claims.
-
Tissue-bank standards: The American Association of Tissue Banks (AATB) standards remain the baseline for donor eligibility, processing validation, and communicable disease controls. Compliance is table stakes for market access and institutional procurement.
-
Reimbursement constraints: Payer coverage—particularly Medicare—remains selective for DBM in various spinal and orthopedic indications. Organizations should model reimbursement risk into pricing and contracting strategies and invest in HEOR evidence that links DBM use to reduced OR time, shorter recovery, and fewer revisions.
Supply chain and manufacturing considerations
-
Raw material stewardship: Access to screened allograft tissue is a strategic asset. LifeNet Health’s reporting of large-scale allograft processing without disease transmission illustrates how processing technology and donor-sourcing scale reduce clinical and reputational risk.
-
Operational resilience: Tissue procurement, processing validation, and cold-chain logistics are critical nodes. Operational failures impair adoption and can trigger payer and hospital pushback.
-
Cost structure: Manufacturing scale, yield efficiency, and contamination controls drive gross margins. Contract manufacturing vs. owning processing capacity is a strategic lever—our models evaluate the trade-offs for both options.
Clinical and economic outcomes — the business case
Clinical outcomes remain the single most persuasive argument for DBM deployment. Recent retrospective clinical evidence reported a 97% healing rate in a tibial nonunion cohort treated with DBM and an average time-to-heal of 4.2 months—data that imply measurable labor and resource savings in surgical pathways. For procurement committees, translating such clinical endpoints into hospital-level cost avoidance and throughput uplift is the decisive step to secure contracts and favorable positioning on product formularies.
Recommended 2026 actions for executives and investors
-
Prioritize evidence and HEOR investments now: Fund prospective, indication-focused studies and build cost-per-case models that tie DBM use to OR time, LOS, and readmission reductions.
-
Differentiate via product-format strategy: Concentrate R&D and commercialization efforts on formats that match the target surgeon segment (e.g., spine fiber constructs vs. dental particulates) and on handling benefits that reduce OR time.
-
Design a clear regulatory playbook: Early decisions on whether to pursue device pathways or rely on section 361 status will shape clinical claims and market-entry timing; build regulatory milestones into your investment case.
-
Secure upstream supply: Evaluate strategic partnerships or acquisitions of tissue-processing capacity to control quality, capacity, and cost.
-
Use commercial segmentation: Deploy dedicated field teams for high-value spine and dental accounts, supported by robust surgeon training and case data capture.
-
Pursue targeted partnerships and tuck-ins: Identify niche innovators (bioprinting materials, cellularized constructs) for licensing or minority investments to hedge against technology disruption.
-
Model reimbursement variability: Build scenario-based pricing and contracting models to stress-test payor coverage fluctuations and guide negotiation tactics with health systems.
How to use this intelligence in boardroom debates
Boards and investment committees need actionable scenarios: What happens to revenue and margin if Medicare tightens coverage? How much does owning a processing facility improve long-term gross margins? Which product formats can be profitably scaled in three years? Our report provides the quantitative and qualitative inputs—forecast permutations, acquisition target scoring, commercial roll-out timelines, and regulatory milestone charts—necessary to answer these questions and convert strategic direction into executable 18-month plans.
Final note — teaser for the full report
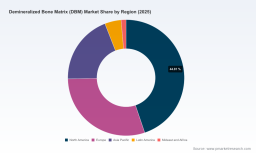
This briefing is intended as a high-value executive preview. In keeping with our “trailer” approach, we have intentionally withheld segment-level revenue tables and regional/application percentage splits from this summary, as those detailed datasets and the underlying modeling files are included exclusively in the full report. Senior leaders and investors evaluating DBM opportunities in 2026 will benefit from the full suite of deliverables: granular segmentation, price-by-format curves, payer-policy overlays, and a live model that can be customized to your strategic assumptions.
For decision-makers preparing to allocate capital, pursue M&A, or refine clinical commercialization strategies in 2026, the full PW Consulting DBM Market Report provides the evidence base, scenario tools, and competitive intelligence required to act with speed and confidence.
For detailed analysis of this topic, please visit the official page: Demineralized Bone Matrix (DBM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


