



PW Consulting: Mineral Insulated Cables Market to Reach USD 2,351.8M by 2032

Mineral Insulated Cables Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
The mineral insulated (MI) cables market has transitioned from a niche safety- and performance-driven technology to a strategic component in critical infrastructure, industrial process control, and hazardous-area electrification. Using 2025 as the base year and a forecast window that extends through 2032, PW Consulting’s proprietary model shows steady, above-market expansion driven by regulatory tightening, material innovation, and selective demand pockets across energy and built-environment applications. The global market expanded from approximately USD 1,314.15 Million in 2020 to USD 1,654.0 Million in 2025, and — under our central scenario — reaches roughly USD 2,351.8 Million by 2032, reflecting a 2026–2032 compounded annual growth rate of about 5.1%.
Mineral Insulated Cables Market
Why our 2026 intelligence changes decisions
- Time-to-certification and supplier qualification are the new strategic gates. With regulatory updates and more demanding project specifications, procurement timelines now extend by quarters unless suppliers and manufacturers pre-emptively align to new standards.
- Material upgrades are creating product differentiation. High-temperature, corrosion-resistant alloy tubing and new sheath/cladding options are changing both longevity and qualification cost curves for MI cable assemblies.
- Supply-chain resilience is a commercial lever. Manufacturers that control upstream metallurgy and tube production can de-risk lead times and command margin premiums; conversely, buyers that lock strategic supply agreements can protect project schedules and total cost of ownership.
What the full report delivers (practical highlights)
PW Consulting’s Mineral Insulated Cables Market study is intentionally action-oriented. Clients can expect deliverables that translate immediately into procurement, product, and investment choices:
Mineral Insulated Cables Market
- Market sizing and forecasting framework (base year 2025; historical analysis 2020–2025; forward view 2026–2032) with scenario-based sensitivities for commodity shocks and regulatory adoption rates.
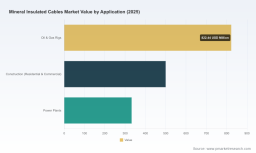
- Segment-level demand drivers and margin dynamics across type, application, and region — with quantification of installed-base replacement cycles and new-build demand triggers. Note: this preview omits core segment splits to protect analytical IP; the full dataset includes the granular breakout.
- Supply-chain mapping and raw-material risk assessment, including alloy tubing supply, copper and stainless-steel feedstocks, and the manufacturers that internalize these capabilities.
- Regulatory and standards compass — implications of recent and emerging standards for product testing, certification timelines, and aftermarket liabilities.
- Competitive benchmark and playbook — deep profiles on leading suppliers, capability matrices, and vendor scorecards to guide sourcing and JV/M&A diligence.
- Go-to-market and product strategy recommendations tailored for OEMs, EPCs, and distributors, together with prioritized near-term tactical moves for 2026.
- Excel deliverables and model access for client-specific scenario runs (price escalators, order-book phasing, volume thresholds for vertical integration).
Market dynamics: what’s moving the needle
Several concurrent dynamics are shaping near-term choices:
Mineral Insulated Cables Market
- Regulatory acceleration. New standards and certification expectations are tightening the barrier-to-entry for unqualified suppliers. Case in point: recent standardization activity published in 2025 has redefined material and testing criteria for a range of MI constructions, affecting qualification scopes and lab testing programs.
- Material innovation. The introduction and commercial ramp of high-temperature, corrosion-resistant alloy tubing fundamentally shift performance benchmarks for MI cables, enabling higher operating temperatures and longer service life in aggressive environments.
- Supplier integration and capacity. The economics of MI cable production favor suppliers that internalize upstream processes — from tube forming to cladding — because they can shorten lead times, reduce quality variance, and protect margins.
- End-market concentration of demand. Demand is increasingly project-driven (e.g., energy projects, safety-critical circuits in the built environment, and process industries) which leads to pronounced peaks and troughs in order books that manufacturers must plan for.
Competitive landscape — capability and strategic posture
The market displays a mix of specialized manufacturers, material suppliers, and assembly-focused players. Rather than enumerate share by segment in this preview, we highlight strategic positioning and what it means for purchasers and investors.
- MI Cable Co. (United States) — Operates with a strong assembly and customer-specific orientation, offering precision cut-to-length assemblies and accessory engineering (e.g., braised pigtails, threaded compression glands) tailored for industrial applications. Strategic implication: attractive as a responsive manufacturing partner for project-centric buyers who prioritize configurability and short lead times.
- MICC Corporation (United States) — Known for breadth of MI cable variety and fire-survival wiring offerings. Strategic implication: strong candidate for buyers seeking a single-source multi-technology supplier, particularly for cross-application projects requiring consistent performance standards.
- M.I. Cable Technologies Inc. (Canada) — Focused on bulk supply to OEM thermocouple manufacturers and backed by ISO17025-certified quality systems. Strategic implication: a go-to partner when calibration, traceability, and lab-backed quality assurance are procurement requirements.
- Wrexham Mineral Cables (UK) — Emphasizes MICC products engineered for safety-critical circuits with long service-life claims. Strategic implication: preferred for lifecycle-sensitive projects where replacement windows are multi-decade and end-of-life costs dominate selection criteria.
- KME Italy S.p.A. (Italy) — Combines mineral-insulated cable production with recognized EU certifications for ATEX/CPR, supporting deployment in regulated European markets. Strategic implication: certification-ready supplier for projects where European regulatory acceptance and conformity documentation accelerate approvals.
- Alleima (Sweden) — Supplies high-temperature, corrosion-resistant alloy tubing used in MI cable applications. Recent product and commercial milestones indicate accelerating adoption of advanced alloys in MI constructions, enabling new operating envelopes. Strategic implication: buyers should consider qualifying advanced tubing suppliers early to capture performance advantages and secure long-term pricing.
- Okazaki Manufacturing Company (Japan) — Differentiates through in-house raw material processing and unique manufacturing techniques, enabling scale and consistency. Strategic implication: a resilient source in procurement strategies that prioritize vertical integration and long-run capacity.
Recent developments that matter for 2026 planning
- Alleima launched a high-temperature alloy tubing product engineered to extend MI cable performance at extreme temperatures and secured initial European orders and North American deliveries in early 2025. Shortly thereafter, Alleima was awarded a North American tubing supply contract to a Canadian MI cable supplier following successful trials.
- Regulatory updates in 2025 have clarified material and testing requirements for MI cable constructions, raising the practical cost of entry for non-certified suppliers and tightening buyer specifications.
- Several manufacturers are publicly emphasizing in-house raw-material processing and certification credentials as a means to shorten qualification cycles and to provide traceability across safety-critical projects.
Strategic playbook for 2026 (recommended actions)
For leadership teams—procurement, product, and corporate development—PW Consulting recommends an evidence-based sequence of actions to capture upside and mitigate risk in 2026:
- Prioritize supplier qualification now, not later. Start cross-qualification programs that align with updated standards and include material suppliers as part of the scope (tube suppliers, alloy houses).
- Negotiate conditional long-term supply contracts with tier-1 tubing suppliers to stabilize input pricing and delivery windows; include performance-based clauses tied to qualification outcomes.
- Segment your sourcing strategy: treat high-criticality circuits and long-life installations differently from commoditized assemblies. Use multi-sourcing where failure carries asymmetric cost implications.
- Invest in certification and traceability. Certifications (ISO, ATEX/IMQ/CPR, and equivalent national standards) materially shorten approval cycles for critical projects.
- Evaluate vertical integration selectively—particularly for OEMs that can justify the capital expenditure through recurring, high-margin demand streams or integration synergies.
- Use scenario modeling to stress-test procurement under commodity shock, regional regulation adoption, and accelerated electrification in adjacent industries.
- Build a vendor-sourced innovation pipeline. Engage suppliers on co-development for advanced alloys and sheath/cladding combinations to de-risk first-of-kind projects.
What’s behind the paywall — and why it matters
This preview intentionally demonstrates the analytical depth PW Consulting deploys while withholding core subsegment matrices, granular regional/application splits, company-level revenue breakdowns, and the Excel model that links demand drivers to supplier capacity constraints. Those elements are included in the full report and are essential for transaction due diligence, supplier RFPs, and product roadmapping. In practice, clients who obtain the full dataset are able to:
- Quantify break-even volumes for vertical integration decisions;
- Prioritize candidate suppliers for qualification based on lead-time risk and technology fit;
- Calibrate procurement hedges against material price stress scenarios; and
- Identify near-term M&A targets whose capability sets unlock new applications or geographies.
Closing — how PW Consulting can help
As organizations set budgets and make sourcing commitments in 2026, the MI cables market presents both incremental opportunity and structural risk. Whether you are an OEM designing next-generation thermocouples, an EPC specifying fire-survival power, a distributor optimizing inventory, or a private-equity sponsor assessing consolidation plays, the choices you make now about supplier qualification, material commitments, and technology roadmaps will determine cost and delivery outcomes for years.
PW Consulting’s full Mineral Insulated Cables Market study provides the datasets, vendor scorecards, and scenario models necessary to convert market insight into executable strategy. Contact our team for a briefing or to license the complete report and Excel model.
For detailed analysis of this topic, please visit the official page: Mineral Insulated Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


