



PW Consulting: PBI Market to Hit USD 77.78 Million by 2032 (13.67% CAGR)

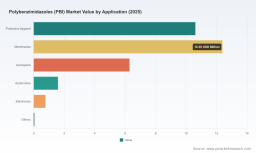
Polybenzimidazoles (PBI) Market: Strategic Briefing for 2026 Decision-Makers
Executive summary
Polybenzimidazoles (PBI) occupy a niche at the intersection of extreme-environment materials, membrane science, and safety-critical textiles. Between 2020 and 2025 the industry recorded modest but resilient demand, with the market moving from the high‑20s (USD Million) range into the low‑30s (USD Million) by the report base year of 2025. From 2026 onward our forecast shows a pronounced acceleration, driven by hydrogen and carbon‑handling membrane opportunities, next‑generation protective apparel, and select industrial high‑temperature applications — the global market is projected to expand at a compounded annual growth rate (CAGR) of 13.67%, reaching roughly USD 77.8 Million by 2032.
Polybenzimidazoles (PBI) Market
This briefing distils the strategic value of our full Polybenzimidazoles Market research for corporate decision‑makers planning 2026 priorities. It demonstrates actionable lines of enquiry and decision frameworks while intentionally withholding granular segment breakdowns to invite access to the full report for transaction‑grade intelligence.
Polybenzimidazoles (PBI) Market
Why this matters for 2026 strategy
-
Timing: 2026 is the inflection point. The modeled expansion from the 2025 base accelerates materially thereafter — presenting a narrow window to secure feedstock, capacity, and strategic partnerships before competition compresses margins.
Polybenzimidazoles (PBI) Market -
Value migration: PBI is transitioning from specialty textiles into membrane and electrochemical applications (e.g., H2/CO2 separation, proton exchange). This moves value upstream toward polymer producers and vertically integrated membrane suppliers.
-
Capital intensity and scarcity: Production requires complex synthesis and high‑temperature spinning, resulting in high capital and operating costs. Early investments in scalable production or licensing can create durable cost advantages.
Market trajectory & implications (data‑driven view)
Observed market behavior from 2020–2025 shows resilience through cyclical pressures; the 2025 market sits at approximately USD 31.7 Million. Under conservative to disruptive policy and technology scenarios we project a multi‑year expansion at a 13.67% CAGR across 2026–2032, with nominal market size approaching USD 77.8 Million by 2032. This trajectory implies:
-
Rapid capacity scaling needs for membrane manufacturing and specialty fiber production — OEMs and converters face a classic "build vs. buy" choice.
-
Commercialization windows that reward first movers in targeted sub‑applications (e.g., industrial H2 separation, advanced firefighter shells, aerospace thermal protection).
-
Margin pressure for undifferentiated commodity resin; premium extraction possible through integrated membrane systems, branded protective fabrics, and service‑embedded offerings.
Competitive landscape — what the leading players signal
The PBI landscape is shaped by a small set of technology‑intensive suppliers, with differentiated positions along the value chain rather than broad horizontal competition. Key incumbents include a sole specialty fiber/polymer producer with established proprietary brands and deeply integrated fabric partnerships, large chemical groups offering engineering PBI grades for high‑temperature components, and regional specialists focused on niche engineering applications.
-
PBI Performance Products, Inc. — A vertically integrated nameplate in PBI polymer and fiber, positioned around its Celazole® brand and long‑standing relationships in protective apparel and high‑temperature specialty markets. Their product family and ongoing marketing initiatives make them the logical anchor partner for apparel OEMs and safety fabric innovators.
-
Mitsubishi Chemical Advanced Materials — A global chemical heavyweight offering high‑performance PBI resin grades engineered for mechanical stability at elevated temperatures. Their strengths are material science depth, scale, and distribution to engineering OEMs requiring predictable thermo‑mechanical performance.
-
Polymics Ltd. — Smaller, agile supplier focused on Celazole® portfolio distribution and engineered thermoplastic applications. Their niche focus enables faster application trials and customized grade development for wear‑resistant, high‑heat components.
Recent industry moves are illustrative rather than exhaustive: strategic product launches for ultra‑lightweight PBI outer shells in protective gear, continued marketing and product support by incumbent polymer houses, and trade show visibility for advanced flame‑resistant fabrics. Collectively these activities indicate a market moving from product proof to commercialization scale‑up.
Technology & application dynamics
Two technical themes dominate the near‑term value creation:
-
Membranes for gas separation and electrochemical devices: PBI membranes have demonstrated commercially attractive H2/CO2 selectivity and operational tolerance to contaminants (H2S, CO, steam) in extended high‑temperature testing. That opens commercial routes into pre‑combustion decarbonization, hydrogen purification, and certain fuel cell PEM applications — creating large addressable markets where polymer performance can substitute or complement inorganic alternatives.
-
Protective textiles and high‑temperature components: PBI fiber and fabric continue to command premium positions in firefighter turnout gear, aerospace thermal protection, and niche industrial safety applications. The emergence of ultra‑lightweight outer shells suggests product innovation can materially expand use cases (improved firefighter ergonomics, reduced heat stress).
These technology pathways imply distinct commercial plays: membrane value accrues with integrated system providers and licensers, while textile value accrues with fabric integrators and branded PPE companies. Strategy must therefore align to the target capture point along the value chain.
Operational and regulatory considerations
-
Production economics: High‑temperature synthesis and spinning processes require specialized equipment and skilled operators. For new entrants, build‑out timelines and capex recovery must be stress‑tested across multiple price and adoption scenarios.
-
Raw material & supplier risk: Feedstock complexity and constrained supplier pools can create single‑point vulnerabilities. Procurement strategies should combine long‑lead supplier contracts, dual sourcing, and inventory buffers.
-
Regulatory posture: Reputation and regulatory compliance matter: notable supplier declarations indicate no use of PFOA in fiber manufacture, and membrane test results support high‑temperature performance claims. Still, environmental and end‑of‑life considerations for specialty polymers are evolving; proactive engagement with regulators and standards bodies is advised.
Practical uses of the full report for 2026 decisions
Executives and investment teams will find the report directly applicable to these priority actions in 2026:
-
Capex & capacity planning: Use scenario forecasts to size greenfield or retrofit investments, evaluate utilization break‑even, and set staged commissioning triggers.
-
Supply chain resilience programs: Identify critical suppliers, quantify inventory needs under stress scenarios, and prioritize contracting or backward integration options.
-
Product & market prioritization: Allocate R&D and commercialization budgets across membranes, textiles, and engineering resins using demand elasticity and margin maps provided in the report.
-
M&A and partnering screen: Shortlists and valuation sensitives for tuck‑ins, licensing, and joint ventures enable target prioritization without overpaying for near‑term optionality.
-
Commercial strategy: Channel segmentation, customer willingness‑to‑pay matrices, and distributor economics inform pricing and promotional tactics for a 2026 go‑to‑market push.
Risks, mitigations and decision checkpoints
Key risks include technological substitution, feedstock scarcity, and slower than expected membrane adoption. The full analysis layers quantitative sensitivity testing (price, adoption, regulation) against a set of mitigation actions:
-
Hedging and supplier contracting to blunt feedstock shocks;
-
Staged capital deployment tied to adoption milestones for membrane pilots;
-
Partnerships with established fabric OEMs to accelerate certification and procurement cycles for protective apparel;
-
Active participation in standards working groups to shape membrane testing protocols and fuel‑cell acceptance criteria.
What the full report contains (practical deliverables)
-
Transparent market sizing methodology and historical audit trail (2020–2025) plus granular forecasting (2026–2032) with scenario overlays.
-
Segmented demand models by application and product form (fiber, film, resin), with sensitivity tables you can adapt to your internal assumptions.
-
Supply chain maps, cost stacks, and unit economics for greenfield vs. contract manufacturing approaches.
-
Competitive benchmarking, capability matrices, and go‑to‑market playbooks tailored for upstream producers, converters, and OEMs.
-
M&A shortlists, due‑diligence templates, and valuation levers specific to PBI technologies and adjacent membrane platforms.
-
Regulatory and standards tracker, including verified supplier declarations and material test outcomes relevant to fuel‑cell and gas‑separation applications.
Closing — strategic posture for 2026
For leaders preparing 2026 roadmaps, PBI represents a high‑value, capital‑intensive segment with asymmetric upside for correctly timed moves. The market’s projected compounded growth from the 2025 base through 2032 creates windows to capture premium margins via vertical integration, performance branding, or targeted licensing. The right playbook blends defensive supply‑chain actions with offensive commercialization and technology partnerships.
Our full market study translates these insights into executable workstreams — from capex decision trees and supplier scorecards to M&A target dossiers. The briefing here highlights the strategic contours; the full report supplies the guarded segmentation and model outputs required to operationalize 2026 decisions. Access to the complete dataset and scenario models will materially reduce execution risk and accelerate value capture.
For detailed analysis of this topic, please visit the official page: Polybenzimidazoles (PBI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


