



Directional Drilling Market Poised for 6.65% CAGR Through 2032 — PW Consulting

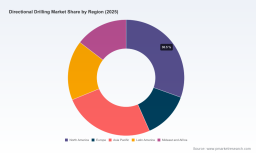
Directional Drilling Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s senior industry analysts, we present a focused, decision-grade introduction to our Directional Drilling Market study — timed to inform capital allocation, procurement, and M&A choices in 2026. This preview is designed as a “trailer”: it demonstrates the analytical depth and practical frameworks that underpin our full report while intentionally withholding granular subsegment tables and proprietary scoring so senior teams are compelled to consult the full deliverable for transaction- or budget-level actions.
Directional Drilling Market
Market Trajectory: What the headline numbers mean for strategy
The directional drilling market has moved from post‑pandemic recovery into a sustained growth phase. Using 2025 as our base year, the global market is estimated at approximately USD 13.9 billion and is forecast to expand to roughly USD 21.8 billion by 2032, reflecting a compound annual growth rate (CAGR) of 6.65% over the forecast horizon (2026–2032). The historical window (2020–2025) captures early volatility and an inflection toward higher-tech drilling solutions; the forecast reflects both continued demand for conventional HDD capacity and accelerated adoption of premium directional and rotary steerable systems.
Directional Drilling Market
For corporate decision-makers in 2026 this trajectory implies three immediate imperatives: preserve optionality in capital plans to capture upside demand, lock in supply‑chain resilience for critical drill‑bit materials, and prioritize technology investments that shorten time‑to‑production and reduce per‑meter costs.
Directional Drilling Market
Why this study is strategically valuable in 2026
- Actionable capital allocation guidance: We translate market growth and technology adoption curves into recommended capex phasing, ROI thresholds and unit economics for utility, pipeline and energy-sector projects.
- Procurement risk-to-opportunity mapping: The study identifies where raw‑material volatility and supplier concentration translate into real price and lead‑time risk for drill bits, reamers and HDD rigs — and prescribes hedging, dual‑sourcing and design‑substitution tactics.
- M&A and partnership signal framework: We convert competitive concentration and capability gaps into a prioritized list of acquisition targets, JV structures and technology partnerships for both incumbents and private equity entrants.
- Regulatory stress-testing: The report models regional regulatory and labor cost shocks against project economics to identify tipping points where previously viable projects become marginal.
What the full report contains (practical modules)
- Executive summary with board‑level recommendations, investment heat maps and three forward scenarios (base, upside and downside) tailored to 2026 planning cycles.
- Market sizing and growth model (2020–2032) with downloadable assumptions, sensitivity tables and a unit economics calculator for client projects.
- Detailed competitive benchmarking: product portfolios, automation stacks, service models and aftermarket economics for leading vendors.
- Supplier risk dashboard: raw material exposures, lead‑time analytics and a recommended supplier diversification playbook.
- Regulatory and labor impact analysis with playbooks for compliance, labor cost mitigation and community‑engagement strategies.
- M&A playbook and valuation multipliers based on segment positioning, marginal cost improvement potential and cross‑sell synergies.
- Contracting and tender strategy templates for contractors and owners to optimize price, schedule and warranty terms.
Competitive landscape — reading the core vendor moves
The directional drilling market shows elevated concentration. The top three firms capture the majority share of revenue, and the top five broaden that dominance further. For executives evaluating competitors, partners or targets, our full study dissects where each firm generates its strategic margin — equipment design, systems automation, aftermarket consumables, or integrated services — and how that maps to future value creation.
Key players examined in the study include:
- Vermeer Corporation (Pella, Iowa) — A market leader in utility and pipeline horizontal directional drills. Vermeer’s strength is its breadth of platform offerings from compact to heavy‑duty rigs and a clear push into machine automation and integrated fluid management. For customers, Vermeer’s installed base offers predictable lifecycle economics and strong dealer networks, but the company faces pressure to continue delivering software‑enabled uptime and remote diagnostics.
- Charles Machine Works / Ditch Witch (Perry, Oklahoma) — Ditch Witch’s product lineup targets both compact urban utility work and heavier pipeline deployments. Its competitive edge lies in robust field support and tailored machine configurations. Strategic choices for Ditch Witch include accelerating digital services and expanding aftermarket parts availability to defend margins under pricing pressure.
- Ulterra Drilling Technologies — A premium supplier of PDC drill bits and downhole tools for oil and gas directional drilling. Ulterra’s R&D focus on bit life and rate‑of‑penetration is critical as operators push to extend laterals and reduce trip time. However, rising PDC production costs and supply constraints (noted below) force product and sourcing adjustments.
- Melfred Borzall, Inc. — A specialist in HDD tooling and reamers, Melfred is an OEM‑preferred supplier whose niche expertise makes it an attractive acquisition target for firms seeking to fill tooling gaps or integrate reamer technologies into a broader service offering.
Materials, manufacturing and the new cost structure
Raw‑material dynamics are reshaping product economics across the value chain. A steep surge in tungsten carbide pricing and tighter export controls has pushed many drill‑bit makers to re‑evaluate material mixes and production geographies. Concurrently, delays and cost increases in synthetic diamond supply have added margin pressure to PDC tool producers. Some U.S. manufacturers are already shifting toward steel‑based designs to maintain price competitiveness; others are investing in alternative cutter geometries and coatings to preserve performance while reducing dependence on volatile commodities.
For procurement and engineering teams, the implication is clear: assume higher base costs for premium cutting elements and embed material‑price escalation clauses, secondary sourcing, and design‑to‑cost initiatives into all three‑year procurement plans. The full report includes a supplier cost‑curve model and recommended bill‑of‑materials sensitivities for common HDD and directional tool sets.
Regulatory and labor dynamics — immediate considerations
Two regulatory developments deserve operational attention. First, regional prevailing‑wage determinations — exemplified by a recent ruling setting elevated wage rates for HDD labor groups in a U.S. state through mid‑2026 — materially affect labor budgets on urban and state‑funded infrastructure projects. Second, industry bodies continue to refine safety standards; active advocacy from trade associations means compliance requirements are likely to become more prescriptive in the near term.
Project sponsors and contractors must re‑price labor contingencies, accelerate productivity programs that lower per‑meter labor exposure, and engage proactively with regulators and associations to shape practical standards. Our modeling shows that in higher‑cost labor jurisdictions, technology that reduces crew size or shortens project duration produces outsized economic benefits.
Scenario planning: triggers and strategic responses
- Base case (our central forecast): Growth continues in line with a 6.65% CAGR as oil & gas lateral extension, utilities modernization and pipeline replacement demand reinforce equipment replacement cycles and premium tool uptake.
- Upside case: Accelerated infrastructure spending and faster fleet electrification/digital upgrades push adoption of higher‑margin rotary steerable systems and automation features, increasing total addressable service revenue beyond base estimates.
- Downside case: Prolonged raw‑material supply constraints and adverse regional regulatory shocks lead to project deferrals and compression of aftermarket margins; smaller contractors bear disproportionate impacts.
How executives should use this preview today
- Use the market trajectory and concentration metrics in corporate planning to set realistic growth targets and to stress‑test current market share assumptions for 2026 board plans.
- Prioritize supply‑chain actions: immediate steps include opening secondary sourcing lanes, negotiating longer lead‑time contracts for high‑risk consumables, and initiating design‑for‑cost projects where tungsten or synthetic diamond exposures are material.
- Review contractual templates to introduce escalation mechanisms and performance‑based warranty language that protect margins when material costs or labor rates spike.
- For M&A teams, apply the competitive profiling here to refine target screening — look for tooling specialists or digital service providers that either complement fleet capabilities or unlock aftermarket revenue streams.
Next step — access the full intelligence
This preview surfaces the analytical frameworks, headline market trajectory and the primary strategic implications you need for 2026 planning. To execute on procurement actions, sanction targeted capex, or begin disciplinary M&A activity you will need the full subsegment tables, regional and application breakouts, supplier scorecards and downloadable model files that are intentionally excluded from this trailer. Access to that granular intelligence and our proprietary scoring methodology is available through the PW Consulting Directional Drilling Market full report package.
Contact PW Consulting to obtain the complete dataset, scenario models and a bespoke briefing that maps these findings to your portfolio and 2026 decision calendar.
For detailed analysis of this topic, please visit the official page: Directional Drilling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


