



PW Consulting: Metal Powder AM Market to Reach USD 1,055M by 2032 (15.4% CAGR)

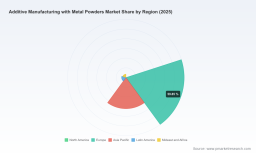
Additive Manufacturing with Metal Powders: 2026 Strategic Briefing
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, decision-focused briefing to orient corporate leaders on where the Additive Manufacturing (AM) with metal powders market stands at the start of 2026 — and what that means for near‑term strategy. This briefing synthesizes the full market study (base year 2025) to expose the structural shifts, competitive battlefield, and the practical levers executives must pull this year. It intentionally surfaces analytical depth while preserving the granular segment tables in the full report — consider this a strategic trailer designed to prompt action.
Additive Manufacturing with Metal Powders Market
Where the market stands: macro trajectory and what it signals
The market for additive manufacturing using metal powders has moved from a specialized, capitalization‑led niche into a predictable growth corridor. By the base year 2025, the market reached roughly USD 390 million (USD Million, base year 2025). Our forecast models project sustained, high‑teens growth through the coming decade, with a compound annual growth rate of 15.4% and a market approaching the USD 1.06 billion mark by 2032. That trajectory reflects a shift from early adopter projects toward production‑scale deployment across targeted verticals and materials systems.
Additive Manufacturing with Metal Powders Market
For executives, three macro takeaways matter: (1) the scale is now large enough to justify dedicated supply‑chain investments and industrialization roadmaps; (2) growth is not uniform — winning positions will be created at the intersection of material innovation, qualification of production processes, and localized supply resilience; and (3) timing matters: capability investments made in 2026–2028 will determine leadership in the 2028–2032 commercial wave.
Additive Manufacturing with Metal Powders Market
Immediate strategic imperatives for 2026
- Secure diversified powder supply and materials roadmaps. Rising tariffs and supply‑chain pressure have made localized production and multi‑sourcing more than risk management — they are value drivers. Firms should map critical metal exposure, qualify at least two powder providers for each strategic alloy, and budget for buffer inventories while conversion and qualification cycles are underway.
- Prioritize qualification and certification as strategic moat builders. The path to volume production is governed less by machine throughput and more by material/process qualification, standards compliance, and validated supply chains. Allocate cross‑functional capital to accelerate qualification campaigns that shorten time‑to‑revenue.
- Embed materials strategy into product design early. Material decisions now dictate manufacturability, cost, and long‑term serviceability. Create a materials decision framework that balances performance, cost, recyclability, and geopolitical supply risk.
- Consider targeted vertical plays rather than broad coverage. The economics and qualification timelines vary sharply by application (e.g., aerospace vs. high‑volume auto components). A focused vertical approach — pairing materials, machine architecture, and aftermarket ecosystems — increases win rates.
- Build partnerships across the value chain. Successful market entrants in 2026 will be those who co‑invest with powder producers, machine vendors, and end customers to de‑risk qualification and scale trials.
Competitive landscape: who matters and why
The market exhibits meaningful concentration among established machine suppliers and leading powder producers. The top domestic and international incumbents control a sizable share of installed capacity and maintain deep integration into qualification and certification pipelines. This concentrated structure creates both barriers and partnership opportunities.
- EOS GmbH (Krailling, Germany) — known for DMLS® laser powder bed fusion systems and an extensive alloy and certified powder portfolio. EOS remains a reference supplier for high‑end production parts where material traceability and system certification are critical.
- Nikon SLM Solutions AG (Lübeck, Germany) — offers large‑format selective laser melting systems and emphasizes integrated materials/process support. Nikon’s play is to enable scale by combining machine capability with system‑level process control.
- GE Additive / Colibrium Additive (Cincinnati, USA) — integrates both laser and electron beam powder bed fusion technologies with in‑house metal powder production. Their vertical approach is designed to shorten qualification cycles for OEMs shifting to AM production.
- 3D Systems Corporation (Rock Hill, USA) — delivers metal powder bed fusion and direct metal printing platforms plus a materials portfolio. 3D Systems positions itself around end‑to‑end solutions tied to application engineering services.
- Xi’an Bright Laser Technologies (Xi’an, China) — focuses on high‑performance laser powder bed fusion systems and end‑to‑end powder solutions, increasingly relevant in cost‑sensitive and large‑format deployments.
- Höganäs AB (Höganäs, Sweden) — longstanding powder producer with a broad portfolio of spherical metal powders optimized for AM. Their strength is in material consistency and global distribution capability.
- Equispheres (Boston, USA) — specializes in engineered aluminum and copper alloy powders crafted for high‑speed, cost‑competitive production. Notably, in April 2026 they showcased new aluminum and copper solutions aimed at thermal and electrical performance in production contexts.
- 6K Additive (Lancaster, USA) — a differentiated entrant producing metal powders from recycled feedstock. 6K announced a marked capacity expansion (a fivefold increase targeting ~1,000 metric tons per year, with the majority brought online by end‑2026), shifting competitive dynamics around sustainable sourcing and cost profiles.
Strategically, incumbents are converging on two plays: (a) verticalization — pooling machines, powders, and qualification to sell validated system outcomes rather than components; and (b) materials differentiation — offering purpose‑built powders (e.g., copper and specialized aluminum alloys) that unlock new applications. New entrants that can demonstrably reduce cost, improve throughput, or shorten qualification time will attract premium partner interest or M&A attention.
Regulatory, supply and materials dynamics shaping strategy
Three structural dynamics deserve explicit attention in 2026 planning:
- Tariffs and localization pressures. Rising global tariffs and logistics friction are accelerating proposals to localize powder production and AM cell deployment. This strengthens business cases for regional powder plants and intra‑company material programs.
- Critical metals concentration remains a vulnerability. Nickel, cobalt and several specialty alloys are geographically concentrated; this risk influences sourcing strategies, contract length, and stockpiling decisions.
- Material innovation is unlocking new economics. Recent introductions — such as copper and specialized aluminum powders engineered for high‑speed production — are removing prior constraints around thermal management, conductivity, and cycle time. These powders change unit economics and open new application windows.
What the PW Consulting report delivers — operational, actionable content
Our full study translates the above dynamics into pragmatic tools executives can use immediately:
- Forward‑looking demand curves to 2032 (by technology class and material family) with scenario sensitivity to tariffs, raw‑material shocks, and adoption rates.
- Supplier and capability maps that identify manufacturing clusters, qualification centers, and critical single‑source exposures.
- Cost models and unit economics templates that quantify break‑even thresholds for part substitution versus conventional manufacturing.
- Risk heatmaps and mitigation playbooks for critical metals, logistics, and regulatory risk.
- Commercial due‑diligence scorecards and an M&A screening list that ranks targets by strategic fit, IP strength, and margin accretion potential.
- Go‑to‑market playbooks and sample qualification roadmaps tailored to aerospace, medical, and high‑throughput industrial applications.
- Templates for in‑house pilot programs and supplier co‑development agreements to accelerate material and process validation.
Each deliverable is accompanied by Excel models and decision matrices so your team can run “what‑if” scenarios in hours rather than weeks. The full report contains the granular segmentation tables and regional/application splits that are essential for execution — these are intentionally withheld from this briefing to centralize access on our platform.
How to use this analysis in your 2026 planning cycle
- Procurement leaders: initiate multi‑year supply contracts with tier‑1 powder producers, and secure options with second‑source suppliers for critical alloys.
- R&D and product teams: prioritize two‑material qualification tracks for strategic product lines and budget for accelerated process validation.
- Operations and plant planning: evaluate localized AM cell pilots in tariff‑sensitive markets and run cost‑sensitivity analyses on onshore vs. offshore powder sourcing.
- Corporate development: use our M&A screening to identify tuck‑ins that deliver near‑term margin improvement or vertical integration benefits (e.g., powder capability, post‑processing, or digital quality platforms).
- Sales and commercial: align go‑to‑market propositions around validated materials and demonstrate total cost of ownership improvements to target OEM buyers.
Final word — timing and next steps
2026 is a pivot year. The industry is transitioning from learning and prototyping to scaled, qualified production—and that transition rewards firms that act now to secure materials, streamline qualification paths, and partner with specialized powder and machine suppliers. PW Consulting’s full Additive Manufacturing with Metal Powders study provides the layered, executable intelligence required to convert strategic intent into measurable commercial outcomes. For teams planning investments, partnerships, or M&A in 2026, this research is the playbook to shorten time‑to‑value.
Access to the detailed segment tables, supplier rankings, and downloadable financial models is available through our report portal — our team stands ready to run a tailored briefing that maps these insights directly to your product lines and markets.
For detailed analysis of this topic, please visit the official page: Additive Manufacturing with Metal Powders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


