



PW Consulting: Gravity Energy Storage Market to Surge 19.8% CAGR, Reach USD 2,460.7M by 2032

Gravity Energy Storage Systems: Strategic Imperatives for 2026 — A PW Consulting Preview
As global power systems accelerate their shift to variable renewables and decarbonize legacy dispatchable capacity, gravity-based energy storage has moved from niche demonstration projects into the cross‑hairs of utility planners, project developers, and strategic investors. This preview synthesizes the PW Consulting Gravity Energy Storage System Market study (base year 2025; historical 2020–2025; forecast 2026–2032) and explains why the report is an operationally critical input for 2026 corporate decision-making.
Gravity Energy Storage System Market
Market at a Glance: Momentum and Scale
The gravity energy storage market has shown rapid expansion in the historical window. Measured in USD Million revenue terms, the market grew from an estimated ~281.6 in 2020 to ~694.8 in 2025. Our forecast work (2026–2032) projects a continued acceleration driven by system deployments and commercial validation, with the market reaching approximately 2,460.7 by 2032. This trajectory implies a compound annual growth rate (CAGR) of 19.8% over the 2026–2032 forecast period — a growth profile that places gravity storage among the faster-scaling long-duration options in the energy storage ecosystem.
Gravity Energy Storage System Market
These topline figures are directional and intentionally headline-focused in this preview. The full PW Consulting study contains the project-level models, regional deployment curves, and sensitivity scenarios that underpin these aggregate numbers — critical inputs for capital budgeting, M&A screening, and portfolio stress-testing.
Gravity Energy Storage System Market
Why Gravity Storage Matters for 2026 Decisions
- Long-duration, merchant-capable value: Gravity systems promise multi-hour to multi-day discharge profiles without chemical degradation pathways that challenge battery alternatives. For firms evaluating capacity expansion, this shifts the economics around firm renewable integration, peak-shaving, and capacity market participation.
- Deployment diversity reduces siting friction: Unlike pumped hydro, modern gravity concepts can be adapted to a wider range of topographies and use-cases — from tower-based and rail-based systems to repurposed underground wells. This flexibility shortens the project development timeline and widens potential asset portfolios.
- Strategic optionality for grids and IPPs: Gravity systems can be configured for strict grid services (frequency regulation, spinning/non-spinning reserve) or for energy arbitrage and renewable firming. For 2026 resource plans, this versatility enables value‑stack optimization across markets with evolving ancillary service frameworks.
- Capital allocation and timing: The market’s high growth rate creates a “first-mover versus scale” trade-off. Early entrants benefit from preferential sites, offtake relationships, and intellectual property advantages — while later entrants can leverage falling unit costs and standardized procurement. Our report outlines timing heuristics tailored to corporate risk appetite and balance-sheet strength.
What the Report Delivers: Practical, Transaction-Ready Insight
PW Consulting designed this report to be operationally actionable for executives and project teams. Key deliverables include:
- Validated market sizing and a three‑scenario deployment model (base, accelerated, conservative) with revenue and capacity forecasts through 2032.
- Technology deep dives comparing structural approaches (tower systems, rail/mass-moving concepts, underground/repurposed-well solutions) on capital intensity, lifecycle maintenance profiles, round‑trip efficiency drivers, and site adaptability.
- Project finance templates and LCOE-style comparators that let you plug in localized CAPEX/OPEX inputs and revenue-stack assumptions to generate deal IRR and payback visuals.
- Procurement playbook and sample contract terms (EPC, O&M, spare parts, performance guarantees) tuned to gravity‑specific risk vectors.
- Regulatory and incentives mapping for major markets, and an assessment framework for revenue certainty mechanisms (capacity markets, contracts-for-difference, ancillary service tariffs).
- Risk matrix and mitigation strategies covering permitting, environmental review, OEM concentration, supply chain bottlenecks, and technology failure modes.
- Vendor scorecards and go‑to‑market partner stratification — from integrators and OEMs to developer-contractor models — enabling rapid partner selection and due diligence checklists.
In short, the report bridges strategy and execution: it guides board-level allocation decisions and equips project teams with the spreadsheets, vendor evaluation tools, and contractual language to execute pilots or utility-scale rollouts in 2026.
Competitive Landscape: Consolidation and Strategic Profiles
The gravity storage space is market-concentrated, with a small number of technology incumbents commanding meaningful share and shaping technical standards and procurement norms. Our market concentration analysis indicates that the top three players account for the large majority of reported commercial activity, and the top five are dominant across project pipelines. This concentration amplifies supplier risk and creates negotiation dynamics that buyers must manage carefully.
Representative company profiles highlight strategic positioning:
- Energy Vault (United States) — Offers a modular, tower-based system family designed for long-duration grid-scale storage with high round‑trip efficiency and minimal topography constraints. Their approach focuses on standardization for rapid site replication and has attracted strategic partnerships to pilot multi-site deployments.
- Advanced Rail Energy Storage (ARES) (United States) — Delivers rail-based, mass-car systems that emphasize long asset life and non-flammable mechanical simplicity. Their solution targets utility-scale renewable integration and ancillary services with an emphasis on lifecycle cost competitiveness.
- Renewell Energy (United States) — Specializes in repurposing idle oil and gas wells into networked underground gravitational storage assets. Their strategy combines grid services testing, certification pathways, and environmental co‑benefits through the reuse of existing infrastructure.
Each profile in the full report contains capital cost benchmarks, engineering maturity assessments, reference projects, procurement-lead time estimates, and commercial terms observed in the market — indispensable for supplier selection and risk allocation during 2026 negotiations.
Policy, Funding & Market Design Dynamics
Public sector programs and grants are accelerating technology validation and derisking early projects. Federal and state energy agencies are explicitly funding gravity storage pilots and research initiatives aimed at grid resilience, repurposing existing infrastructure, and interoperability testing. In parallel, policy reports and pilot audits have begun to surface real-world cost observations and learning-curve evidence that materially influence procurement expectations and investment cases.
For corporate decision-makers, this means two things in 2026: (1) leverage public funding and demonstration programs to compress validation timelines and improve project economics; (2) design commercial structures that anticipate evolving market rules and possible retroactive changes to capacity/ancillary revenue frameworks. Our report provides an up-to-date map of the relevant programs and a practical checklist to capture funding without exposing balance-sheet risk.
Key Risks, Practical Mitigations
- Technology maturity risk: Mitigate with staged deployment (pilot → commercial tranche), acceptance testing thresholds, and performance guarantees.
- Permitting and environmental reviews: Use early engagement with regulators, benefit-from-repurposed-infrastructure arguments where applicable, and standardized environmental management plans.
- Supply chain and OEM concentration: Structure multi-supplier procurement, include serial spares in initial procurement, and negotiate vendor-exit clauses tied to performance milestones.
- Revenue and market design exposure: Build portfolio diversification across revenue stacks, pursue long-term offtake where available, and conduct sensitivity runs on ancillary vs. energy arbitrage revenue mixes.
How PW Consulting Supports Your 2026 Playbook
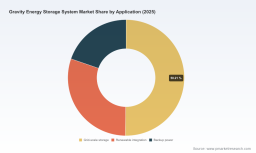
PW Consulting’s full Gravity Energy Storage System Market study goes beyond forecasting: it operationalizes the market for corporate teams. Clients receive actionable deliverables such as due diligence scorecards, project financing models, procurement templates, and a prioritized pipeline of sites based on technical suitability and market access. Where this preview outlines the strategic contours, the full report supplies the detailed inputs — including region-by-region deployment curves, application splits, and vendor-specific cost models — that procurement and investment committees require to greenlight programs in 2026.
We deliberately withheld granular segment tables and project-level financials from this preview to preserve the report’s utility as an executable decision tool. Accessing the full intelligence set will enable you to:
- Quantify expected returns under customizable market design and incentive assumptions;
- Compare vendor offers on a like-for-like technical and commercial basis;
- Design staged capital deployment strategies that balance first-mover advantages with learning-curve benefits;
- Structure O&M and performance contracts that transfer the right risks to OEMs while protecting asset uptime and revenue realization.
Next Steps for Executives in 2026
If your 2026 strategic plan includes long-duration storage exposure, prioritize the following actions:
- Commission a PW Consulting site suitability and business-case quickscan (4–6 weeks) to translate market-level forecasts into project-level economics aligned with your portfolio.
- Engage with a shortlist of gravity technology suppliers under an NDA to obtain indicative CAPEX/OPEX and commissioning timelines, then benchmark offers using our standardized templates.
- Map public funding and demonstration opportunities to your pilot timeline to reduce capital intensity and accelerate certification pathways.
- Align regulatory affairs and commercial teams to prepare tariff and market-access strategies that preserve optionality for multiple revenue streams.
Gravity energy storage is no longer a speculative subfield — it is a fast-growing segment with clear commercial pathways and strategic implications for generation owners, transmission operators, and large energy consumers. The 19.8% projected CAGR (2026–2032) and the multi-fold increase in market size from 2020 to 2032 indicate both opportunity and urgency.
For the detailed data, granular segmentation, vendor scorecards, and executable procurement materials that leaders need to act in 2026, download the full PW Consulting Gravity Energy Storage System Market report or contact our advisory team for a tailored briefing and implementation workshop.
For detailed analysis of this topic, please visit the official page: Gravity Energy Storage System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


