



PW Consulting: Thermal Transfer Ribbon Market to hit USD 2.66B by 2032 (6.15% CAGR)

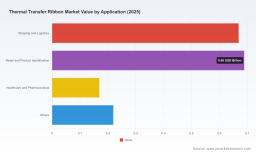
Thermal Transfer Ribbon Market 2026: Strategic Imperatives from PW Consulting
As organizations plan capital allocation, procurement strategies, and sustainability roadmaps for 2026, the Thermal Transfer Ribbon (TTR) market presents a distinctive combination of steady growth, structural consolidation, and technology-driven disruption. PW Consulting’s latest market study—anchored on a 2025 base year and covering historical performance (2020–2025) and a detailed forecast through 2032—translates raw market dynamics into decision-ready insight for C-suite and commercial leaders. This preview highlights the study’s strategic value, key directional findings, and the operational intelligence that will matter to buyers, manufacturers, and investors in 2026—while intentionally reserving the granular segment tables and bespoke numeric splits for the full report.
Thermal Transfer Ribbon Market
Macro view: growth trajectory that demands attention
Between 2020 and 2025, the global TTR market expanded meaningfully, moving from approximately USD 1.25 billion to USD 1.75 billion, reflecting resilient demand across logistics, retail, healthcare and industrial labeling. PW Consulting’s forecast extends this momentum: the market is projected to reach roughly USD 1.80 billion in 2026 and to grow to about USD 2.66 billion by 2032, representing a compound annual growth rate (CAGR) of approximately 6.15% over the forecast window. These figures underscore a market that is neither hyper-cyclical nor stagnant—making it suitable for strategic investment and operational optimization rather than speculative entry.
Thermal Transfer Ribbon Market
Why 2026 is a pivotal year for corporate decision-makers
- Procurement leverage. The market’s steady growth and moderate concentration create timing opportunities for buyers to renegotiate multi-year supplier agreements, lock in favorable raw-material pass-through terms, and pilot alternative supply sources before competition tightens in the latter part of the decade.
- Product and sustainability differentiation. Demand for lower-waste ribbon formats and solvent-free formulations is accelerating. Early movers who adopt validated low-waste ribbons can lower total cost of ownership at scale and meet increasingly strict extended-producer-responsibility (EPR) expectations in key markets.
- Regulatory alignment. Updated standards—such as the revised ISO/IEC quality and safety specifications—are raising the bar for product validation across logistics, healthcare and retail. Companies that integrate the new standard into qualification gates in 2026 will avoid costly requalification and market access delays.
- Supply-chain resilience. Volatility in petrochemical-derived feedstocks—polyester films, carbon black and specialty resins—means that sourcing strategies and inventory policies adopted in 2026 will materially affect cost and service through 2030.
What the PW Consulting report delivers (practical, action-oriented)
The full study moves beyond headline sizing to provide executable intelligence in eight operational modules designed for business leaders and functional owners:
Thermal Transfer Ribbon Market
- Market sizing and scenario model: base-case, upside, and stress scenarios with sensitivity levers for raw-material price shocks, adoption curves for eco-formulations, and printer hardware upgrades.
- Supply-chain heatmaps: supplier concentration, single-source risk nodes, logistics choke-points and contingency playbooks for near-term disruptions.
- Commercial playbooks: procurement negotiation tactics, framework agreement templates, and pricing-index architectures tailored to TTR product classes.
- Product roadmap and R&D implications: technology pathways for hybrid ribbons, near-edge/TTO innovations, and the cost-quality trade-offs of ultra-thin PET films.
- Sustainability benchmarking: comparative lifecycle analyses, waste reduction levers, and compliance checklists aligned to EPR and the newest ISO guidance.
- Competitive benchmarking and M&A screening: capability matrices, value-of-integration scoring, and a forward-looking shortlist of potential consolidation targets.
- Go-to-market and channel strategies: distributor segmentation, OEM-supply partnerships, and label converter collaboration models to accelerate adoption.
- KPIs and implementation roadmap: 90–180 day milestones with measurable targets for procurement, quality, and sustainability teams.
Competitive landscape: a pragmatic synthesis
The TTR vendor ecosystem exhibits a mix of global OEMs, specialty chemistries suppliers, and regional manufacturers. Market concentration is moderate-to-high: PW Consulting’s analysis shows the top three suppliers collectively account for a majority share, and the top five raise that concentration further. Practically, this means that while scale matters, niche capability—chemical formulation, ultra-thin film technology, and supply-chain reach—can still be decisive for differentiation.
Key strategic profiles emerging from our coverage:
- Zebra Technologies (U.S.). A channel-focused incumbent that pairs a broad ribbon portfolio (wax, wax/resin, resin) with strong industrial-printer compatibility. Its value lies in integrated hardware-supplies offerings and commercial channels that facilitate enterprise rollouts.
- ARMOR-IIMAK (France). An innovation-led supplier pushing solvent-free, ultra-thin PET film ribbons—which translate to longer roll life and lower waste. Recent product introductions make ARMOR a bellwether for sustainability-driven product design.
- Ricoh (Japan). Reliability-focused formulations and specialty receiving films that emphasize solvent and chemical resistance—positioned well for pharmaceutical and industrial customers requiring durable, certified performance.
- Dai Nippon Printing (Japan). A supplier with deep manufacturing-application expertise—electronics, food, medical—bringing high-durability ribbons that are tailored for production-line environments.
- ITW ShineMark (U.S.). Combines decorative and industrial ribbon capabilities, appealing to high-value packaging and branding use-cases where print quality and sustainability converge.
- Avery Dennison (U.S.). Leverages label substrate compatibility testing and broad packaging relationships to promote variable information printing with validated ribbon supplies.
- SATO, TSC, Toshiba, Todaytec (Japan/China). These OEM-aligned suppliers emphasize genuine supplies and broad compatibility; their strength is in high-volume, industrial-scale roll production and tight integration with printer ecosystems.
- Brady, Union Chemical, Mitsubishi Chemical, Honeywell. Focused offerings ranging from RFID-enabled ribbons and extreme-resistance chemistries to polyester film base technologies—these players are critical where specialized performance or upstream film supply matters.
Recent product and partnership activity further illustrates where competition will evolve in 2026: ARMOR-IIMAK’s late-2025 roll of an ultra-thin solvent-free product, Zebra’s eco-friendly line expansion, DNP’s targeted launches for electronics and pharma, and SATO’s strategic partnerships on hybrid ribbon development are all early indicators of a shift toward sustainability, hybrid materials and tighter OEM-supplier co-development.
Risks and cross-cutting industry dynamics
- Raw-material exposure. Polyester films and carbon black remain sourced from petrochemical feedstocks; material availability and oil-price swings directly affect cost curves. Companies that hedge or diversify film supply chains reduce margin volatility.
- Standards and certification. The revised ISO/IEC guidance requires updated labelling for performance and environmental claims. Non-compliance risks market access restrictions in regulated sectors.
- Labor and manufacturing skillsets. High-quality ribbon production requires skilled coating processes. Strategic investments in automation and workforce training are necessary to scale premium formulations without quality leakage.
- Regulatory pressure on recyclability. Extended producer responsibility in some regions is increasing demand for recyclable components; suppliers not prepared to demonstrate circularity will face procurement barriers.
Strategic recommendations for 2026
- Prioritize supplier pilots that de-risk sustainability transitions. Run controlled trials with solvent-free or ultra-thin PET products on high-volume SKUs to validate TCO and printer reliability before contract commitments.
- Integrate new ISO/IEC requirements into qualification gates. Update incoming inspection and supplier scorecards to include the revised standard—this reduces rework and ensures compliance in regulated verticals.
- Adopt a tiered sourcing model. Combine strategic agreements with leading suppliers (to secure capacity and validated performance) and smaller niche partners (for innovation and flexibility).
- Negotiate index-linked pricing. Where exposure to petrochemical feedstocks is material, build raw-material pass-through formulas and shared-savings clauses into multi-year contracts.
- Use concentration analytics to inform M&A and alliance strategies. Because the top vendors exert meaningful share, targeted acquisitions or exclusive partnerships—particularly in hybrid-ribbon technologies—can accelerate market entry and margin accretion.
Why PW Consulting’s report is decision-critical for 2026
The combination of a clear macro-growth path (from ~USD 1.75 billion in 2025 to an expected ~USD 2.66 billion by 2032 at a ~6.15% CAGR), concentrated supplier economics, and accelerating regulatory and sustainability drivers creates a narrow window in 2026 for firms to lock in advantaged positions. PW Consulting’s study distills these dynamics into executable, time-bound actions—covering procurement, R&D, channel, and M&A—that are calibrated to the specific inflection points we expect next year.
This preview is intentionally strategic: it demonstrates the depth of our primary research, the robustness of our scenario modeling, and the operational granularity included in the full deliverable. To access the proprietary segment-level matrices, supplier scorecards, scenario models and the full set of tactical playbooks that underpin the conclusions summarized here, please consult the complete PW Consulting Thermal Transfer Ribbon Market report.
For detailed analysis of this topic, please visit the official page: Thermal Transfer Ribbon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


