



PW Consulting: UVC LED Market to Reach USD 1,540.8M by 2032 at 29.5% CAGR

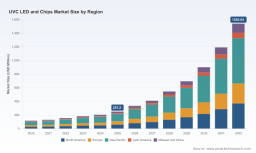
UVC LED and Chips Market — Strategic Imperatives for 2026
By PW Consulting — Senior Strategic Advisory and Industry Analysis. Base year: 2025. Forecast horizon: 2026–2032.
UVC LED and Chips Market
Between 2020 and 2025 the addressable UVC LED and chips market moved from an early-stage niche to a scale-up market, more than doubling in size over five years. Our base‑year estimate for 2025 places the market well into the mid‑hundreds of million USD, and our proprietary forecast projects continued hypergrowth through 2032 at a compound annual growth rate of 29.5%, taking the market to in excess of a billion USD. That velocity creates a strategic window: decisions taken in 2026 will lock in product roadmaps, manufacturing footprint, and partner ecosystems that determine competitive position for the decade.
UVC LED and Chips Market
Why 2026 Is an Inflection Point
Several converging forces make 2026 a pivotal year for corporate strategy in the UVC LED value chain:
UVC LED and Chips Market
- Technology breakthroughs are raising performance thresholds. Recent product announcements — including a validated device exceeding 10% wall‑plug efficiency and novel dual‑chip modules reporting significant photoelectric gains — materially increase system-level efficacy and reduce total cost of ownership.
- Packaging and integration innovations are lowering implementation friction. New TO-39 flat-window packages and higher-yield substrate processes enable designs for far‑UVC, compact water purifiers, and integrated air/surface units that were previously impractical or too costly.
- Regulatory and funding tailwinds are crystallizing. Mercury‑free UVC LED solutions are now explicitly eligible for certain public health incentives, and regulatory guidance (including minimum inactivation dose expectations and established NSF standards for point‑of‑use systems) is pushing buyers toward validated LED-based solutions rather than legacy lamp technologies.
- Supply-side realignment. Portfolio optimizations and capacity shifts among legacy players are already visible. Recent production discontinuations and selective product expansions have created short-term dislocations that materially affect sourcing strategies.
- Cost pressures are non-trivial. Upward movements in material and labor costs have translated into price increases in the first quarter of 2026, forcing both OEMs and systems integrators to re-evaluate margin structures and procurement cadence.
What the PW Consulting UVC LED and Chips Study Delivers
Our report is structured for corporate decision-makers who need actionable answers, not just descriptive market narrative. Key deliverables include:
- Robust market sizing and scenario-based forecasting (base year 2025; forecast 2026–2032) with sensitivity analysis to technology, regulatory, and supply shocks.
- Commercial roadmaps for four pragmatic go‑to‑market archetypes: platform OEMs, integrated systems providers, component suppliers, and public-sector procurement bodies.
- Technology heatmaps and valuation of R&D levers — including substrate choice, thermal architecture, emitter efficiency, and packaging tradeoffs — to prioritize engineering roadmaps and capex allocation.
- Regulatory compliance matrix that maps certification pathways (including US EPA and NSF frameworks) to product development timelines and validation costs.
- Supply‑chain playbook that prescribes mitigation routes for raw‑material constraints, contract manufacturing options, and inventory strategies aligned to lead-time volatility.
- Competitor dossiers and strategic scoring of >20 firms across capability, scale, IP position, and go‑to‑market reach, plus a short list of M&A and JV targets with estimated synergy profiles.
- Financial models and deal templates for strategic investments: sample capex schedules, unit economics for multiple power classes (low, medium, high) and payback analysis for upstream vs. downstream moves.
- Customer validation templates and hands-on pilot designs for water, air and surface disinfection programs that align to public health funding criteria.
Competitive Landscape — What To Watch
The vendor ecosystem combines established optoelectronics champions, specialized UVC innovators, and a fast‑growing cohort of systems integrators. Our qualitative mapping highlights several strategic archetypes:
- Specialist chip innovators with differentiated substrate or epitaxy technology — these firms compete on emitter efficiency and lifetime, and are central to upstream differentiation.
- Large LED platform players with scale manufacturing and thermal management IP — they accelerate commercial adoption by reducing cost-per-output and by offering validated modules with long lifetimes.
- Systems integrators and module houses that combine optics, driver electronics, and validation services — they shorten customer adoption cycles by delivering certified, turn‑key solutions.
- Regionally focused kit manufacturers that optimize for local market needs and cost structures, especially in water and portable device segments.
Recent industry developments are instructive. On the one hand, validation of higher-efficiency emitters and commercially viable dual‑chip modules compresses the technology adoption curve. On the other, corporate portfolio adjustments and production discontinuations have created near-term supply-side uncertainty, increasing the strategic value of diversified sourcing and strategic inventory. Overall, the market remains commercially fragmented: scale leadership is emergent but not yet monopolistic, creating opportunity for well-timed consolidation or focused capability investment.
Strategic Playbooks for 2026 Decision‑Makers
Below are high-impact, practical moves that should be considered this year. Each is tied to a clear decision horizon and expected outcome.
- Prioritize device efficiency and thermal management R&D (12–24 months): Investing in emitter efficacy and heat-sinking reduces system cost per log reduction and is the single largest lever to improve competitiveness in commercial water and HVAC applications.
- Lock critical materials via multi-sourcing agreements (6–12 months): Secure substrate and component supply (including high-yield AlN sources) with staggered contracts and contingency MOQs to reduce vulnerability to single‑supplier shocks.
- Design products around certification pathways (6–18 months): Engineer devices to meet EPA and NSF validation requirements from day one. Certificates reduce time-to-revenue, unlock public procurement channels, and enable access to funding for public health programs.
- Pursue selective M&A or JV to close capability gaps (6–15 months): Target module makers or validated systems integrators to accelerate route-to-market; pursue bolt-on acquisitions to gain immediate access to certification and distribution networks.
- Reconfigure pricing and channel incentives to reflect cost inflation (Q3–Q4 2026): Implement tiered pricing tied to volume and service bundles; introduce maintenance and replacement contracts to smooth revenue and improve installed-base economics.
- Launch pilot projects with public-sector partners (3–9 months): Use government-funded pilots to validate claims, collect field efficacy data, and create reference cases that de-risk commercial sales cycles.
- Build a modular product taxonomy (9–18 months): Create interchangeable modules for optics, drivers, and emitter arrays to speed customization and lower inventory complexity.
- Invest in verification & validation (12 months): In-house or partner-based testing facilities — including microbiological validation against EPA protocols — will shorten customer qualification timelines and reduce warranty exposure.
Who Should Read This Report
The study is designed as a decision tool for executives and managers who must convert market velocity into profitable growth:
- CEOs and Business Unit Heads planning market-entry, scale-up, or vertical integration strategies.
- R&D and Product leaders prioritizing efficiency, lifetime, and packaging roadmaps.
- Supply‑chain and procurement teams managing supplier risk and inventory policies.
- Corporate development and PE teams evaluating M&A, JV, and minority-investment opportunities.
- Public sector and NGO program directors designing procurement for water, healthcare, and HVAC disinfection initiatives.
Methodology and Confidence
PW Consulting’s analysis synthesizes bottom‑up build-up models, primary supplier interviews, validation-test datasets, and regulation-driven demand modeling. We combine quantitative market projection techniques with qualitative strategy workshops to produce scenario outputs intended for board-level deliberation. While the public summary highlights major trends and high‑level sizing, the full study includes granular models, segment-level demand matrices, and unit-cost stacks to support detailed due diligence.
Important note: this overview deliberately focuses on strategic narratives and directional metrics. For company valuation inputs, regional and application-level breakdowns, per‑firm revenue estimates, and downloadable financial models, consult the full report and our interactive dashboard.
Next Steps — How to Use the Intelligence
If you are preparing a board deck, evaluating R&D spend, negotiating supply contracts, or screening M&A targets, start with three practical steps this quarter:
- Request the full market model to run your sensitivity scenarios (price, efficiency, certification timelines).
- Commission a short supplier risk assessment scoped to your Bill of Materials to identify single‑point vulnerabilities.
- Initiate one pilot with a certified system partner that aligns to an identified public procurement opportunity.
In a market forecast to sustain near‑triple‑digit percentage growth over the next several years, 2026 is a year to act deliberately but with speed. PW Consulting’s UVC LED and Chips study is engineered to convert uncertainty into a prioritized, executable plan — balancing product, procurement, and partnership moves so you capture scale while managing technical and regulatory risk.
Access the full report for the detailed segmentation, per‑company profiles, validation datasets, and financial models that underpin these strategic recommendations.
For detailed analysis of this topic, please visit the official page: UVC LED and Chips Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


