



PW Consulting: Isotropic Graphite Market to Reach USD 344.8M by 2032 at 6.98% CAGR

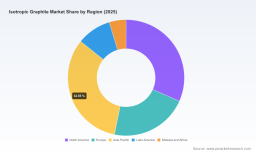
Isotropic Graphite Market: Strategic Imperatives for 2026
Executive snapshot
The isotropic graphite market is entering 2026 from a position of steady expansion. After recovering from mid-decade volatility, the industry baseline reached approximately USD 215.0 million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 6.98% through the 2026–2032 horizon, reaching an expected market size north of USD 340 million by 2032. This trajectory reflects persistent demand from high-precision industrial end markets and structural shifts in supply chains and raw-material inputs.
Isotropic Graphite Market
Why this study matters for 2026 corporate decisions
For senior executives, procurement leads, engineering heads and corporate development teams, 2026 will be a year to convert strategic intent into executable plans. The market’s mid-single-digit CAGR masks important asymmetries: demand for high-purity, fine-grain grades is concentrating around a handful of capital-intensive applications, while feedstock and trade policy fluctuations are compressing lead times and elevating supply risk. Our Isotropic Graphite Market research does more than report numbers — it provides the decision-support framework necessary to prioritize capital allocation, select partners, design resilient sourcing strategies, and size near-term investments that preserve optionality into the next decade.
Isotropic Graphite Market
Principal market dynamics
- Application-driven demand concentration: Precision applications — from semiconductor wafer processing to high-temperature industrial components — are driving an outsized share of near‑term demand growth, rewarding producers with advanced processing capabilities and stringent quality control.
- Raw material tightness and cost pass-through: Production is dependent on calcined petroleum coke and coal-tar pitch, with petroleum-based needle coke a critical upstream feedstock. Global needle coke supply dynamics and the broader synthetic graphite market (estimated in the low billions USD range in mid-decade industry estimates) create periodic pricing and availability shocks that affect margins and project timelines.
- Regulatory and trade intermittency: Recent trade policy shifts and export controls have created episodic market dislocations. Temporary suspensions and reinstatements of export verification regimes can rapidly alter supplier sourcing strategies and customer qualification pathways.
- Fragmented supplier landscape: The industry displays low concentration metrics — top-three and top-five concentration ratios are modest — which creates opportunities for nimble local players but also increases complexity for downstream buyers seeking standardized global supply.
Regulation and geopolitics — the 2026 decision edge
Regulatory developments in 2024–2025 have had outsized implications for 2026 planning. Policymaking on strategic materials in major jurisdictions has translated into investment incentives, import controls and shifting export verification procedures. Recent temporary policy relaxations in some exporting countries have provided short-term relief to buyers, but these remain episodic. Meanwhile, regional initiatives to classify graphite as a critical raw material are catalyzing domestic production and recycling investments in multiple geographies. Executives should treat policy volatility as a recurring scenario in procurement modeling rather than a one-off event.
Isotropic Graphite Market
Competitive landscape — capabilities that matter
The market includes a mix of long-established carbon-technology houses and agile regional producers. Leading players differentiate along three axes: precision manufacturing processes (cold isostatic pressing, fine‑grain molding), vertical integration into feedstock production or procurement, and downstream qualification pathways with strategic end markets (notably semiconductor fabs and nuclear OEMs).
- Toyo Tanso Co., Ltd. (Tokyo) — A pioneer in cold isostatic pressing and high-added-value processing; places emphasis on semiconductor etch components and high-purity grades for aerospace and nuclear users.
- Tokai Carbon Co., Ltd. (Tokyo) — Known for fine-grain isotropic grades and global production footprint supporting EDM and semiconductor processing needs.
- SGL Carbon SE (Wiesbaden) — Broad portfolio across isotropic and molded graphite; recent capacity utilization improvements and raw-material tailwinds enhanced margins in 2025.
- Mersen S.A. (Paris) — Focuses on isostatic graphite for thermal management, nuclear, and high-temperature furnace applications with strong engineering services.
- GrafTech International (USA) — Positions toward energy-storage and advanced manufacturing markets with high-purity product lines and global sales channels.
- HEG Ltd. (India), Showa Denko/Resonac (Japan), Superior Graphite (USA), Ibiden (Japan) — Each brings distinct regional strengths, product customization and market access, forming a competitive field where partnerships and niche specialization win.
Collectively, top-tier firms are expanding capacity and moving up the value chain, while numerous regional suppliers are competing on lead time and local certification. The result is a bimodal landscape of capital‑intensive global suppliers and fast-to-market local players.
What the PW Consulting report delivers — practical, transaction-ready tools
This research is structured to support boardroom decisions and front-line execution. Key deliverables include:
- Transparent market-sizing methodology and reconciled historical series (2020–2025) leading into a segmented forecast (2026–2032) with sensitivity scenarios.
- Supply-chain heatmaps that trace feedstock origin, processing choke points, and inventory lead-time implications for different product grades.
- Regulatory-risk playbooks mapping likely policy scenarios and their impact on sourcing, customer qualification and cross-border logistics.
- Raw-material stress tests and price elasticity models tied to needle-coke and calcined coke availability assumptions.
- Commercial playbooks: supplier scorecards, qualification timelines for semiconductor OEMs, contractual clauses for supply assurance, and negotiation templates for multi-year purchase agreements.
- M&A and partnership heatmaps identifying acquirable capabilities, integration pitfalls and expected payback horizons under multiple growth scenarios.
- CapEx and procurement decision matrices to align capacity investments with demand timing, payback tolerance and regulatory exposure.
Actionable recommendations for 2026
- Stress-test supply chains now: Model at least two disruption scenarios (short-term export control, medium-term feedstock shortage) and secure contingency contracts or buffer inventories for critical high‑purity grades.
- Prioritize qualification pipelines: For firms targeting semiconductor or nuclear demand, accelerate qualification and audit readiness; lead times to full qualification meaningfully exceed component manufacturing timelines.
- Evaluate vertical integration selectively: For larger players, partial upstream integration into needle‑coke procurement or long-term tolling agreements can stabilize margins. For mid-sized firms, strategic supply partnerships and offtake agreements are lower-capex alternatives.
- Localize where incentives align: Monitor incentives and build-versus-buy decision trees in jurisdictions offering support for critical material production and recycling; this will shorten qualification cycles for local customers.
- Use fragmentation to pursue bolt-on consolidation: Low concentration metrics indicate acquisitive opportunities for firms seeking scale in specialty grades, particularly those with complementary customer lists or processing technologies.
- Hedge raw-material exposure: Implement hedging frameworks and supplier scorecards that reward assured supply and technical cooperation, not just price.
- Embed regulatory monitoring into procurement KPIs: Make export-control and critical-materials watchlists part of monthly supplier reviews to avoid last-minute disruptions.
How to use this intelligence in board-level planning
Translate the report’s scenarios into three executable plans: defend (protect existing margins and customer relationships), expand (target new high-value end markets with clear qualification roadmaps), and hedge (secure feedstock and diversify supplier base). For boards and investment committees, this translates into a prioritized capital allocation schedule and a short list of M&A targets or strategic partnerships that can be executed within 12–24 months to capture forecasted growth while guarding against regulatory shocks.
Next steps — where the full intelligence is
This introduction outlines the strategic logic and tactical levers that PW Consulting’s full Isotropic Graphite Market report delivers. The complete study contains detailed segmentation tables, granular regional and application forecasts, vendor financial benchmarks, and downloadable decision-support models designed for immediate integration into 2026 planning cycles. Given the commercial sensitivity of segmentation and customer-level data, those specifics are available in the full report via the official release page.
For leadership teams preparing 2026 strategies, this research provides the evidence base and practical toolset to convert market growth into defensible commercial advantage while managing asymmetric regulatory and feedstock risks. PW Consulting stands ready to support scenario workshops, supplier negotiations, and M&A diligence informed by the dataset and tools embedded in the full study.
For detailed analysis of this topic, please visit the official page: Isotropic Graphite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


