



PW Consulting: Light Control Film Market to Reach USD 397M by 2032

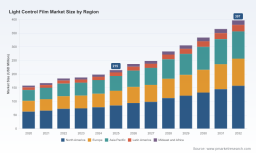
Light Control Film Market: Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s senior industry analysts, we present a focused strategic primer on the Light Control Film market to inform executive decision‑making in 2026. This brief situates the market’s growth trajectory, competitive dynamics, supply‑side pressures, regulatory inflection points, and practical levers companies should prioritize this year. It is intentionally composed as a “trailer”: we demonstrate analytic depth and actionable perspective while preserving proprietary sub‑segment detail to guide readers to the full report for transaction‑grade intelligence.
Light Control Film Market
Executive snapshot
The Light Control Film market is at a commercial and technological inflection. On a 2025 base year, the market totaled approximately USD 215 million (base year 2025, historical window 2020–2025). Our forecast projects continued expansion through 2032, with the market roughly doubling during the 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 9.24%, reaching an estimated USD 397 million by 2032. This trajectory reflects a convergence of retrofit demand, OEM adoption in automotive glazing, energy‑efficiency policy enforcement in building codes, and material and manufacturing innovations.
Light Control Film Market
Why 2026 is pivotal
- Policy and retrofits converge: Stricter energy‑efficiency targets and incentive programs in multiple jurisdictions are accelerating retrofit projects that can be served by film solutions as lower‑cost alternatives to full glazing replacement.
- Material innovation becomes a differentiator: Suppliers introducing circular‑material offerings and ceramic/infrared‑blocking technologies are shifting procurement criteria from purely optical performance to lifecycle emissions and embodied carbon.
- Supply‑chain fragility persists: 2025 disruptions in polyester substrate availability exposed vulnerabilities; manufacturers and buyers must decide whether to vertically integrate, dual‑source, or accept cadence risk for premium product lines.
- Market remains accessible to midsize players: Industry concentration is low enough (CR3 ≈ 24.6%, CR5 ≈ 26.2%) that nimble entrants and regional champions can capture specialty niches if they deploy disciplined go‑to‑market strategies.
What the PW Consulting report delivers (practical contents)
- Robust market sizing and scenario forecasts (historical series and three forecast scenarios through 2032), with sensitivity to raw‑material price and regulatory shifts.
- Demand maps and buyer personas for each major application channel—architectural retrofits, OEM automotive, and commercial/industrial installations—framed to inform product positioning and channel economics.
- Supply‑chain heatmaps identifying single‑point‑of‑failure suppliers, cost pools, and near‑term capacity bottlenecks, plus mitigation playbooks for procurement and inventory design.
- Competitive benchmarking: technology positioning, channel coverage, manufacturing footprint, and tactical growth moves for the industry’s active players.
- Commercialization templates—pricing ladders, specification‑to‑RFP playbooks, and installer incentive structures—that convert specification wins into profitable volume.
- Regulatory and certification matrix (ENERGY STAR, LEED, local VLT statutes), compliance roadmaps, and product labelling considerations that impact market access and tender eligibility.
- ESG and circularity assessment: lifecycle comparison models, supplier selection checklists, and investor‑grade sustainability claims guidance.
- Investment and M&A screeners: priority target profiles, valuation heuristics, and integration risk checklists for strategic acquirers.
Competitive landscape — what to watch in 2026
The competitive field is mixed: established chemical and materials majors, specialized film manufacturers, and regional players each play distinct roles. The report profiles core competitors and distills strategic implications for each class of market participant.
Light Control Film Market
- Large‑scale integrators and materials majors (example profiles): Global firms with integrated value chains supply both advanced substrates and finished films. Their advantages are R&D depth, broad distribution, and the capacity to support OEM qualification programs. Recent capacity expansions in ceramic film lines by large chemical producers improve availability for commercial retrofit demand, but create pressure on margins in commoditized segments.
- Specialized film manufacturers and technology pioneers: These players focus on high‑performance ceramic, nano‑ceramic, and privacy films that meet strict certification standards. Their differentiation is technology intensity and brand recognition among installers and architects; they remain attractive acquirers or partners for conglomerates seeking product laddering.
- Regional and value‑chain niche players: Firms supplying dyed polyester or coated thin films serve local OEMs and tuck into regional installer networks. They are often faster to market with localized product variants and can capitalize on lead‑time sensitivities during substrate supply shocks.
Recent company moves underscore strategic themes relevant to 2026 action plans:
- Product innovation aligned with circularity is marketable—suppliers launching films using 100% recycled PET facestock reduced CO2 intensity on a per‑product basis and opened up sustainability procurement conversations with building owners.
- Capacity investments in ceramic film production target retrofit and commercial retrofit backlogs; for buyers, this reduces lead‑time risk for high‑end films but also signals potential price competition as scale improves.
- Certification convergence (ENERGY STAR, LEED compliance) is migrating from a marketing advantage to a procurement precondition in certain commercial and public tenders.
Market dynamics and near‑term risks
- Raw‑material volatility: Polyester substrate production experienced slowdowns in early 2025 due to energy rationing in key producing countries. Buyers should stress‑test supply contracts and consider dual‑sourcing or local inventory nodes for critical SKUs.
- Regulatory patchwork: Visible light transmission (VLT) limits and tint regulations vary significantly across jurisdictions; OEMs and retrofit providers must embed local compliance checks into spec sheets to avoid rework costs.
- Standards and certification arms race: High UV/IR rejection and low visible light compromise tradeoffs drive a certification premium. Films that can demonstrate compliance with established green building standards secure higher acceptance in institutional procurement.
- Fragmented demand drivers: Demand mix between new construction, retrofit, and automotive glazing shifts with macro cycles. Firms overly dependent on any single channel risk cyclical exposure.
Strategic imperatives for 2026 decision‑makers
To convert market growth into defensible commercial advantage in 2026, executives should prioritize the following:
- Decide on a materials strategy now: Commit to either vertical integration (secure upstream substrates), strategic partnerships with recycled PET suppliers, or hedged purchasing. Each path has distinct CAPEX, margin, and speed‑to‑market tradeoffs.
- Productize sustainability: Move beyond marketing claims to verified lifecycle data. Films with demonstrable CO2 reductions and circular inputs will increasingly win institutional tenders and premium pricing.
- Operationalize certification: Route product development through certification gates early to avoid late‑stage redesigns and to fast‑track procurement eligibility in energy‑sensitive projects.
- Channel mastery: Build turnkey installer programs and OEM qualification toolkits. Margins in film are realized in the installation and warranty performance; controlling the installer experience improves both customer satisfaction and recurring revenue opportunities (service, replacement programs).
- M&A and partnerships: Target bolt‑on assets that provide either technology (ceramic coatings), channel reach (regional installer networks), or substrate security (recycled PET feedstock). The market’s current concentration profile makes sensible, lower‑cost consolidation plays available to disciplined acquirers.
- Scenario planning and pricing discipline: Embed multi‑scenario pricing models that reflect raw‑material shocks, certification cost adders, and retrofit conversion rates to avoid margin erosion during demand surges.
Short‑term playbook (6–12 months)
- Audit supplier contracts for lead‑time and force‑majeure clauses; establish second‑tier suppliers for critical substrates.
- Launch a pilot product line with recycled PET facestock tied to a verifiable emissions reduction claim (pilot scope and metrics available in the full report).
- Get one flagship product certified to key green building standards to use as a reference for institutional bids.
- Run a channel incentive experiment with top installers to reduce end‑customer friction and shorten the sales cycle.
Mid‑to‑longer term moves (12–36 months)
- Consider capacity investments in ceramic coating lines or strategic minority investments in substrate recyclers to lock in supply and green credentials.
- Pursue targeted M&A that adds either proprietary coatings, patented nano‑ceramic processes, or regional market access where installation economics are favorable.
- Develop a certified lifecycle product family to capture premium procurement segments and support corporate sustainability commitments.
How PW Consulting helps
Our full Light Control Film market study provides the transaction‑grade datasets, sub‑segment revenue splits, regional demand forecasts, and competitor share analysis required to make capital allocation, M&A, and GTM decisions in 2026. The accompanying operational playbooks and procurement stress‑tests translate market insight into implementable plans: supplier scorecards, scenario‑based pricing templates, and integration checklists for targets aligned to your strategic ambition.
If your 2026 strategic plan touches procurement, product development, channel economics, or M&A in the light control film space, the right move this year is to pair market foresight with execution templates. Visit our reference page to access the full study, granular splits, and bespoke consulting engagements that convert the market’s 9.24% CAGR opportunity into measurable value for your organization.
For detailed analysis of this topic, please visit the official page: Light Control Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


