



PW Consulting Abrasives Outlook: USD 48.6M in 2025, 4.67% CAGR (2026–2032)

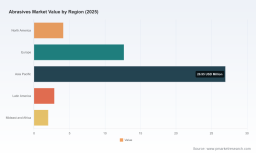
Abrasives Market — 2026 Strategic Outlook: Navigating a Consolidating, Resource‑Sensitive Landscape
As PW Consulting’s lead industry analyst, I present a focused strategic primer to guide executive decisions in 2026. Our latest Abrasives Market study synthesizes five years of observed dynamics (2020–2025) and a seven‑year forecast horizon (2026–2032). The market’s steady upward trajectory — underpinned by a compound annual growth rate (CAGR) of approximately 4.7% — is shaping a competitive and capital‑intensive environment where supply‑chain realism and product differentiation determine winners. This note highlights the study’s strategic value, summarizes critical dynamics, and signals where executives must act now. For full granular segment-level metrics and models, access to the complete report is required.
Abrasives Market
Why this study matters for 2026 decision cycles
-
Actionable visibility on market momentum: The abrasives market has demonstrably expanded since 2020, with an inflection through the mid‑2020s. Stakeholders planning procurement, capacity expansion, or M&A in 2026 need a quantitative baseline — our study provides exactly that, reporting market size progress through 2025 and point forecasts to 2032 in USD (millions) that underpin scenario testing and ROI timelines.
Abrasives Market -
Risk calibration for raw‑material exposure: As cost structures shift, executives must adjust sourcing strategies. The report converts macro supply signals into operational triggers — when to hedge, when to dual‑source, and when to localize — a practical input for 2026 budgeting and contract renegotiations.
Abrasives Market -
Competitive positioning and investment timing: With concentration metrics indicating significant share held by leading players, 2026 is a year to decide between organic capability build, targeted bolt‑on M&A, or strategic partnerships. The study highlights which plays make sense across different product families and end‑market linkages.
Market trajectory — what the numbers tell us
Between 2020 and 2025 the market recorded sustained growth, rising from the low‑forties to just under fifty million USD (base year 2025). Forecasts through 2032 indicate continued expansion, with the market surpassing mid‑sixty million USD by the end of the projection period, driven by steady demand in heavy industries, automotive refinements, and precision manufacturing. The ~4.7% CAGR embedded in our model reflects a balance of industrial capex recovery, productivity gains from higher‑performance abrasives, and gradual penetration of advanced materials and applications.
Importantly, market concentration is meaningful: the top three players capture a material share of the market, and the top five amplify that reach. This concentration creates both barriers and opportunities — for incumbents to leverage scale and for challengers to find tactical niches.
Key dynamics shaping strategy in 2026
-
Raw‑material pressure and cost structures: Silicon carbide and other abrasive raw materials continue to dominate operating costs. Our analysis shows raw inputs can account for a majority of production expenses in specific chemistries, making procurement strategy pivotal. Reduced U.S. imports of metallic abrasives in 2025 — with Canada emerging as a primary supplier — is a directional signal for North American sourcing strategies.
-
Regulatory and compliance overlay: Abrasive manufacturing and use remain tightly coupled with workplace and environmental rules. Compliance with OSHA standards and particulate/crystalline silica regulation, alongside state programs such as CARB certification windows, are non‑negotiable. Firms must map certifications to product roadmaps and aftermarket certification schedules to avoid market access gaps.
-
Capacity and infrastructure response: Producers are selectively expanding capacity to serve steel, construction, and industrial segments. These investments are creating pockets of oversupply risk in commoditized grades, while premium and specialty grades remain tight. Capital allocation decisions in 2026 should discriminate between commodity volume plays and higher‑margin specialized offerings.
-
Product and process innovation: Demonstrations and product launches at recent trade events underscore a shift: manufacturers increasingly pitch performance gains (e.g., precision‑shaped grains, improved bond systems, and ergonomic tool designs) that reduce cycle times and total cost of ownership. Winning commercial narratives will quantify system‑level savings, not just abrasive throughput.
-
Channel and aftersales economics: The interface between power‑tool OEMs, distributors, and industrial end users is evolving. Branded tools and consumables bundles are being used to lock in end‑user lifetime value; service models (tool diagnostics, consumable subscription) offer new margin pools.
Competitive landscape — how leading players are positioned
The competitive field combines broad global leaders, regional specialists, and niche technological players. Our study profiles each major participant and evaluates strategic levers — technology, distribution, vertical integration, and regional footprint — that matter for 2026.
-
Tyrolit Group (Austria) — A leader in grinding and dressing tools, Tyrolit’s strength is in engineered bonded systems and superabrasives tailored for metalworking and precision industries. Their engineering depth positions them well for industrial accounts prioritizing process optimization.
-
VSM AG (Germany) — VSM’s focus on high‑quality coated abrasives — belts, discs, and fiber products — makes them a preferred partner in industrial metal and composite processing where surface finish and repeatability are crucial.
-
3M Company (United States) — With advanced coated solutions such as precision‑shaped grains, 3M competes on system efficiency and brand trust. Their trade show demonstrations and application engineering capability accelerate adoption of higher‑value consumables.
-
Saint‑Gobain Abrasives (France) — As a global leader across bonded, coated, and superabrasives, Saint‑Gobain benefits from a broad product portfolio and deep channels into automotive, aerospace, and construction markets.
-
KWH Mirka Ltd. (Finland) — Mirka’s specialization in non‑woven sanding tools and polishing systems targets segments where finish quality is a premium, such as wood and automotive collision repair. Recent product updates extend their ergonomic and digital integration story.
-
PFERD, Klingspor, Hermes, and other European firms — These players are strong in metal deburring, flap discs, and flexible abrasives — areas where proximity to industrial customers and customization matter.
-
Asian manufacturers (CUMI, Noritake, Asahi Diamond, DEERFOS, Sankyo‑Rikagaku) — These firms combine cost competitiveness with growing technological capability, often integrating upstream supply (including mining) and targeting regional infrastructure growth.
-
OEM and tooling integrators (Bosch, Weiler) — By bundling abrasives with power tools and accessories, these companies capture aftermarket lock‑in and offer convenience to large construction and repair markets.
Competitive moves reported recently — from product showcases at global trade events to incremental product upgrades — signal that 2026 will reward incumbents who translate R&D into measurable productivity improvements and new go‑to‑market models.
What the report contains — practical deliverables for executives
-
Quantitative market model: Historical series (2020–2025) and detailed forecasts (2026–2032) in USD (million), enabling scenario analysis for top‑line planning.
-
Segment frameworks: Product family, application use‑cases, and regional demand drivers with qualitative and quantitative drivers mapped to innovation and regulation impacts (full segment tables and sensitivity inputs available in the full report).
-
Competitive heatmaps: Comparative capability assessment across technology, distribution reach, and vertical integration. This includes CR3/CR5 concentration metrics and implications for pricing pressure and consolidation risk.
-
Supply‑chain risk matrix: Raw‑material sourcing maps, cost‑penetration analyses, and supplier concentration indicators to prioritize mitigation actions.
-
Strategic options playbook: Decision frameworks for capex, sourcing, product portfolio rationalization, and M&A — with executable steps and ROI thresholds tailored to 2026 investment cycles.
Immediate strategic implications for 2026
-
Procurement leaders: Revisit raw‑material contracts with a focus on cost‑pass‑through clauses and dual‑sourcing for key chemistries. Plan supplier audits tied to regulatory compliance (OSHA, EPA) and regional certification windows.
-
R&D and product management: Prioritize developments that reduce end‑user cycle time or total cost of ownership. Demonstrable gains in productivity sell faster than marginal price improvements.
-
Commercial and channel strategy: Consider bundled service offers or subscription models for high‑usage industrial accounts. Strengthen distributor training to elevate technical selling.
-
M&A and partnerships: Use concentration metrics to identify attractive bolt‑on targets that deliver technology depth or regional distribution, rather than volume alone.
-
Compliance and operations: Map product portfolios against regulatory milestones (e.g., state certification end‑dates) to ensure market continuity and avoid costly product relaunches.
Final note — a trailer, not the script
This briefing is intentionally high‑signal and selectively withheld on segment‑level granularity so that executives access the full financials, breakouts, and downloadable modelling tools in PW Consulting’s full Abrasives Market report. The strategic directions and risk triggers above are directly traceable to our proprietary market model and qualitative interviews with industry participants. For procurement managers, business unit heads, and corporate development teams planning 2026 actions, this study is the operational playbook that turns market projection into deployed capital and measurable competitive advantage.
Contact PW Consulting to obtain the complete report, interactive forecast models, and an executive workshop to align your 2026 investment plan with market realities.
For detailed analysis of this topic, please visit the official page: Abrasives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


