



PW Consulting: Evaporative Cooler Market to Expand at 5.3% CAGR through 2032

Evaporative Cooler Market: Strategic Outlook for 2026 Decision-Makers (PW Consulting)
Executive snapshot
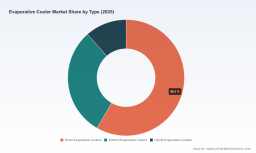
The global evaporative cooler market is at an inflection point. PW Consulting’s base-year assessment places the market at approximately USD 4,645 Million in 2025, having expanded materially since 2020, and our forecast model shows continued momentum through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 5.3%, lifting the market toward an estimated USD 6.6+ Billion by 2032. This briefing summarizes the strategic implications that should inform boardroom decisions, capital allocation and go-to-market plans in 2026 while withholding granular segment-level tables and proprietary split data — available in the full report.
Evaporative Cooler Market
Why this research matters in 2026
-
Decisive capital allocation: The market’s steady growth combined with pockets of technology-driven efficiency gains creates differentiated return profiles for product innovators, aftermarket service players and channel investors.
Evaporative Cooler Market -
Regulatory and ESG alignment: Water and energy use are near-term reputational and compliance vectors; companies that can demonstrate materially lower lifecycle water consumption and higher energy efficiency will capture premium access to public-sector tenders and sustainability-minded corporates.
Evaporative Cooler Market -
Channel reconfiguration: Distribution footprints, dealer economics and service networks are reshaping margins. 2026 is a pivotal year to test expanded distributor partnerships, particularly in fast-ramping subregions and verticals.
-
M&A and partnership timing: The market structure—characterized by regional leaders, specialist OEMs and a long tail of local players—creates windows for consolidation and bolt-on acquisitions to secure aftermarket services and proprietary media/adiabatic technologies.
Market dynamics shaping 2026 strategy
Three structural dynamics are driving the market’s trajectory and should be core to any strategic plan:
-
Energy efficiency as a commercial lever. Indirect evaporative solutions are delivering step-change energy savings versus conventional rooftop units in dry climates; published comparisons report energy advantages large enough to reframe lifecycle cost analyses for commercial and data-center buyers. Expect procurement specifications to increasingly favor systems that demonstrate high performance on standardized efficiency metrics.
-
Water and resource scrutiny. In water-constrained regions, residential units can represent a meaningful household-level water draw—public guidance and customer sentiment are pushing adoption of efficient media and smart controls that curtail annual usage. Efficient models now consume a fraction of average residential water use, a fact that will influence rebate programs and municipal adoption incentives.
-
Regulation and guidance are evolving. Recent guidance from the U.S. EPA elevated evaporative coolers’ role in ventilation strategies and conditioned the industry to integrate higher-efficiency filtration when outdoor air quality is a concern. Equally important are procurement and health-safety requirements for indoor deployment — a competitive advantage for vendors providing integrated IAQ solutions.
Technology and product shifts to watch
-
Pumpless and adiabatic advances. Product launches in 2026 introduced pumpless recirculation adiabatic technologies that materially simplify operation and reduce maintenance. Early adopters that integrate these systems into retrofit pathways can shorten payback timelines and lower total cost of ownership for end users.
-
Modularization and service monetization. Modular media packs, sensor-driven controls and subscription-based maintenance are emerging as margin-enhancing strategies—manufacturers that standardize modular service components will be able to scale aftermarket revenues faster than those relying purely on unit sales.
-
Pricing and input-cost pass-through. Several large vendors adjusted pricing in early 2026; manufacturers must balance short-term margin preservation against channel elasticity and tender competitiveness. Pricing strategy must be scenario-tested against supply-chain disruptions and raw-material volatility.
Competitive landscape — where value is created
The industry contains a mix of broad-line manufacturers, specialist industrial suppliers and regionally dominant portable-unit brands. Market concentration remains moderate: the combined share of the top three players is meaningful but far from monopolistic, and the top five account for only a modest uptick above that — a structure that favors strategic consolidation, niche differentiation and channel partnerships.
-
Phoenix Manufacturing Inc. (Phoenix, AZ) — Strengths: broad portfolio spanning residential to agricultural applications; active channel expansion and new mid-tier and specialty product introductions in 2026. Strategic implication: Phoenix’s dual focus on distribution growth and model refresh positions it to capture near-term residential and agricultural demand, but it must continue to invest in service infrastructure to convert market access into recurring revenue.
-
EVAPCO Inc. (Rockville, MD) — Strengths: recognized leader in indirect and large-scale industrial systems and a recent innovator with pumpless recirculation (PuRe-JET™). Strategic implication: EVAPCO’s technology orientation and industrial footprint make it a preferred partner for large commercial and data center projects; competitors should monitor cost-to-install and maintenance differentials when competing for institutional contracts.
-
Portacool (Ankeny, IA) — Strengths: market leader in portable coolers with strong brand recognition across residential and light-commercial segments. Strategic implication: Portacool’s brand equity and channel relationships create defensive moats in portable and seasonal deployments, but it faces pressure to add IoT-enabled controls and service offerings to maintain ASPs.
-
Champion Cooler Corporation (Denison, IA) — Strengths: product breadth in residential and portable categories with recognized series offerings. Strategic implication: Champion can scale by pursuing aftermarket service bundles and strategic distribution partnerships to increase lifetime customer value.
-
Hessaire Products Inc. (Fontana, CA) — Strengths: focused on home and light-commercial portable units with cost-sensitive positioning. Strategic implication: Hessaire is well-placed for price-driven market segments but will need to adopt higher-efficiency media and connectivity options to participate in rebate-driven and specification-heavy commercial tenders.
Recent market signals and competitive moves (implications)
-
Product innovation is accelerating: a major supplier announced pumpless adiabatic technology in mid-2026, simplifying operation and reducing maintenance. Early commercial deployments will serve as proof points for broader adoption in institutional tenders.
-
Distribution expansion continues: a leading manufacturer expanded its Western U.S. distributor footprint in 2026, signaling intensified competition for retrofit projects and localized seasonal demand. Market entrants should assess distributor economics aggressively before scaling.
-
Regulatory guidance is creating tender requirements: the EPA’s indoor air quality guidance in 2026 elevated filtration and ventilation roles for evaporative systems, which will change specification requirements for many public and private sector projects.
-
Price adjustments: headline price increases earlier in 2026 show vendors are testing cost pass-through; procurement teams should re-evaluate lifecycle cost models and contractors should reprice multi-year service agreements accordingly.
What the full PW Consulting report delivers (practical, action-oriented)
The full market study is built for executable decisions. Key deliverables include:
-
A validated market-sizing model with historical calibration and scenario-based forecasts through 2032, enabling sensitivity testing by macroeconomic and climate scenarios.
-
Demand-driver dashboards covering climate, construction activity and retrofit propensity by vertical — presented as decision matrices to prioritize go-to-market resource allocation.
-
Technology and product roadmaps that map performance attributes (energy, water, IAQ) to buyer value propositions and rebate eligibility criteria.
-
Channel and margin playbooks: distributor scorecards, dealer profitability models and three strategic channel expansion templates tailored for OEMs, private label players and aftermarket service providers.
-
Regulatory and compliance toolkit: a practical checklist for procurement clauses, filtration requirements and municipal rebate capture.
-
M&A screening matrix and 12–18 month integration plan for tuck-ins that accelerate service revenue or add proprietary media/adiabatic intellectual property.
-
Implementation checklists and pilot templates to validate new technologies (e.g., pumpless adiabatic systems) in controlled deployments before wide-scale roll-out.
How executives should use these insights in 2026
-
Prioritize pilots that prove operational savings. Short pilots for novel adiabatic/pumpless systems with clear measurement of energy, water and maintenance hours will accelerate specification wins.
-
Lock in distribution selectively. Target distributor partnerships that provide service capability and spare-parts logistics rather than only incremental SKU reach.
-
Design bundled service offers. Convert unit sales into longer-lived revenue by packaging media replacement, filtration upgrades and remote monitoring with multi-year contracts.
-
Embed regulatory readiness into RFP responses. Proactively address IAQ guidance and water-conservation criteria to shorten procurement cycles for public and institutional buyers.
-
Use the M&A playbook to identify regional service platforms or media/IP targets that accelerate access to aftercare revenues and proprietary efficiency tech.
Closing guidance and next steps
For companies deciding where to place bets in 2026, the evaporative cooler market presents a balanced set of opportunities: predictable mid-single-digit growth at the market level, rapid technology-driven differentiation in select verticals, and fragmented competitive dynamics that reward focused consolidation and service innovation. PW Consulting’s full report contains the proprietary segmentation, regional and application-level detail, supplier scorecards and financial models that will enable execution teams to convert strategy into measurable outcomes. Accessing the full dataset and appendices is the recommended next step for any executive preparing 2026 budgets, R&D roadmaps or M&A pipelines.
To obtain the complete study, including the full set of segment tables, scenario models and operational playbooks, please refer to the PW Consulting Evaporative Cooler Market page for purchasing and licensing options.
For detailed analysis of this topic, please visit the official page: Evaporative Cooler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


