



PW Consulting: Bancassurance Market at USD 1.27T in 2025, 5.17% CAGR (2026–2032)

Bancassurance Market 2026: Strategic Imperatives and What Leaders Must Act On
Executive snapshot
From a $950 billion industry at the start of the last decade to an estimated $1.27 trillion in our base year (2025), the bancassurance market is on a steady trajectory that demands boardroom attention. PW Consulting’s proprietary forecast (2026–2032) projects the market to grow at a 5.17% CAGR over the forecast period, resulting in a materially larger and structurally different market by 2032. For executives preparing budgets, partnership roadmaps, and M&A playbooks in 2026, this growth profile compresses the timeline for capability build and makes timing a strategic variable—not just an operational one.
Bancassurance Market
Why 2026 is a strategic inflection point
The coming year is not merely another data point on a growth curve. It is a confluence of regulatory change, digital resilience mandates, and shifting commercial economics for banks and insurers. Recent regulatory moves—ranging from national-level bancassurance directives to supranational digital and data laws—are recalibrating how bancassurance products can be marketed, sold, and technologically supported. Concurrently, capital treatment relaxations in certain jurisdictions and new digital operational resilience obligations increase both the opportunity set and the compliance bar for integrated models.
Bancassurance Market
- Regulatory momentum: New directives and amendments are formalizing bancassurance product definitions, licensing expectations, and marketing protocols in several jurisdictions, changing the threshold for market entry and partnership design.
- Digital resilience and data access: Cross-border regulatory frameworks now require banks and their insurance partners to harden operational resilience and to rethink customer data access models—creating both friction and fertile ground for differentiated product innovation.
- Capital and business-model incentives: Targeted easing of capital requirements in key markets is encouraging banks to consider deeper strategic investments with insurance partners, accelerating the move from distribution-only arrangements to hybrid ownership and captive-insurer structures.
Market dynamics: how growth is getting reshaped
Growth in bancassurance is less about raw demand than about distribution efficiency and the ability to convert banking customer relationships into insurance lifetime value. The market’s historical expansion reflects both product breadth and the widening remit of banks as embedded financial-services platforms. But the next phase of growth will be characterized by:
Bancassurance Market
- Platformization of distribution: Banks are investing to make insurance offerings part of everyday banking journeys via APIs, white-label products, and embedded-insurance models—shifting the economics from transactional commissions to lifetime revenue sharing.
- Data-driven product tailoring: With new data access rules, advanced insurers and progressive banks can design hyper-personalized protection and savings solutions—but only if they resolve consent, portability, and governance issues at scale.
- Operational resilience as a competitive moat: Compliance with digital operational resilience frameworks is becoming a market differentiator: firms that can demonstrate high uptime, secure integrations, and fast recovery will win distribution exclusivity and partner trust.
- Strategic capital allocation: As capital-treatment changes reduce barriers to deeper integration, expect a bifurcation between banks that remain pure-distributors and those that move to partial ownership or captive models to capture higher long-term margins.
Competitive landscape: who matters and why
The bancassurance field is populated by global banking groups that vary in strategy, scale, and market focus. Our analysis profiles leading institutions—ranging from full-service global banks to regionally dominant retail banks—and highlights the strategic approaches that differentiate winners from the rest:
- BNP Paribas (Paris): Uses its global banking network to position bancassurance as a core distribution channel for both life and non-life solutions. Strategic implication: BNP’s integrated approach favors insurers seeking broad, multi-jurisdictional reach.
- Crédit Agricole (Paris): Leverages a retail banking footprint and captive insurance capabilities, underlining a vertically integrated model. Strategic implication: Attractive for insurers seeking predictable scale and deep local distribution partnerships.
- Société Générale (Paris): Focuses on protection, investment, and savings via banking channels—emphasizing packaged customer journeys. Strategic implication: Its model favors product bundling and cross-sell optimization.
- Intesa Sanpaolo (Turin): Prioritizes an extensive domestic network with targeted international reach—ideal for insurers pursuing high-density market penetration.
- HSBC (London): Operates globally with capabilities across life, non-life, and wealth insurance—well-suited for insurers and reinsurers aiming for premium, cross-border products.
- Wells Fargo (San Francisco): Maintains a U.S.-focused distribution approach; useful partner for insurers seeking deep engagement in North American retail banking channels.
- Barclays, ING, ABN AMRO, Lloyds Banking Group: These institutions exhibit a mix of retail & corporate channel strategies, with strengths in regional execution and digital banking integrations.
Across the competitive set, market concentration remains modest—the top three and top five banking groups together capture under one-third of the market—indicating substantial opportunity for mid-sized banks, fintechs, and specialized insurers to carve differentiated niches through technology, product design, and local regulatory agility.
What this means for 2026 corporate decisions
Leaders should treat 2026 as a make-or-accelerate year. Decisions that can no longer wait include:
- Partnership architecture: Decide whether to pursue distribution-only agreements, bancassurance joint ventures, or partial ownership of insurance entities. Each route carries different capital, control, and compliance implications.
- Technology road map: Invest in modular, API-first platforms that allow rapid product rollouts, experiment with embedded insurance offers, and ensure compliance with digital resilience standards.
- Data governance: Implement consented data-sharing frameworks to monetize customer insights while remaining compliant with emerging data access laws; this is both a legal necessity and a commercial enabler.
- Operational risk posture: Align IT and third-party risk management to meet digital resilience mandates and to secure partner approvals—failure here will limit distribution options.
- M&A and inorganic options: Evaluate targeted acquisitions or minority stakes in specialty insurers to accelerate product capabilities or access proprietary underwriting data.
What PW Consulting’s full report delivers (practical, action-oriented)
Our full Bancassurance Market research goes beyond high-level forecasts to provide a practical toolkit senior leaders can deploy in 2026. Highlights include:
- Scenario-based financial models calibrated to different partnership archetypes (distribution-only, JV, partial ownership), enabling rapid valuation and ROI sensitivity analysis.
- Vendor and partner scorecards—standardized criteria for selecting insurance partners, tech vendors, and distribution integrators.
- Go-to-market playbooks for embedded insurance, cross-sell campaigns, and branch-digital integration, complete with KPI templates and pilot design checklists.
- Technology and security due-diligence checklists mapped to digital operational resilience requirements and third-party risk expectations.
- Regulatory tracker and compliance playbook—interpreting recent directives and major laws so you can fast-follow reforms across critical jurisdictions.
- Executive dashboards and interactive tables that break down historical performance (2020–2025), the 2026 inflection scenarios, and detailed forecasts through 2032—ready for board presentations.
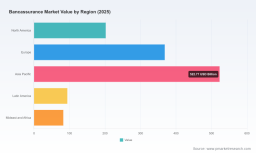
To respect competitive sensitivity and our “trailer” principle, the full report reserves granular regional and product-level split tables, detailed competitor market shares, and downloadable modeling templates for report subscribers and clients. These elements are the difference between a well-informed strategic discussion and a fully executable plan.
How to use the report to accelerate value capture in 2026
We advise clients to adopt a three-track approach this year:
- Protect: Shore up compliance and operational resilience to maintain current distribution agreements and avoid regulatory friction.
- Pilot: Launch 6–12 month embedded insurance pilots tied to discrete banking journeys (for example, lending or savings) to test pricing, underwriting, and consent mechanics.
- Scale or partner: Based on pilot outcomes and capital allocation choices, scale winners or fast-track M&A/partnerships to secure shelf space and exclusive distribution terms.
Each of these tracks requires different resource mixes and governance levels; our report provides templates to map those resource implications to expected revenue uplifts and capital needs under multiple scenarios.
Methodology and transparency
The analysis uses a base year of 2025 with historical context from 2020–2025 and a forecast horizon of 2026–2032. All values are presented in USD (Billion) and the market-level CAGR for the forecast window is 5.17%. Our methodology triangulates revenue reporting from banks and insurers, public filings, partner-disclosure data, and a bottoms-up model that accounts for distribution economics, retention rates, and pricing trends.
Next steps and how to access the full intelligence
For executives who must translate vision into validated action plans this year, the full PW Consulting Bancassurance Market report is built as your go-to strategic and operational manual. It contains the detailed regional and product splits, competitor market-share analytics, and downloadable playbooks that we have deliberately excluded from this primer to encourage direct engagement with the full intelligence package.
Visit our report page to access the comprehensive dataset, interactive forecasts, and client-only workshops that will help you convert 2026’s regulatory and digital disruption into durable market advantage.
For detailed analysis of this topic, please visit the official page: Bancassurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


