



PW Consulting: Crypto Hardware Wallet Market to Reach USD 344.8M by 2032 at 19.87% CAGR

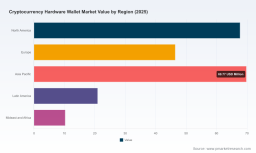
Cryptocurrency Hardware Wallet Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest industry briefing on the Cryptocurrency Hardware Wallet Market frames a decisive moment for enterprise strategy in 2026. After a steady recovery through 2020–2025, the market has entered a high-growth phase driven by regulatory mandates, insurance dynamics, and rapid product innovation. Our analysis projects that the market, which exceeded USD 200 million in 2025, will expand at a compound annual growth rate of roughly 19.9% through the 2026–2032 forecast window, creating new value pools and strategic inflection points for manufacturers, custody providers, retailers and enterprise security teams.
Cryptocurrency Hardware Wallet Market
Why this research matters for 2026 planning
-
Actionable foresight in a compliance-first era — Since late 2024, binding custody rules in major jurisdictions have redefined how client assets must be isolated and protected. This shifts demand from point solutions to certified, auditable hardware and changes procurement criteria for regulated entities.
Cryptocurrency Hardware Wallet Market -
Insurance and risk transfer dynamics — Insurers are increasingly linking coverage terms to specific device certifications and operational patterns. Access to underwritten custody solutions now requires visibility into device assurance levels and integration with institutional workflows.
Cryptocurrency Hardware Wallet Market -
Product and distribution bifurcation — Consumer convenience (mobile, NFC and retail availability) and institutional-grade assurances (secure elements, EAL certification, air-gapped workflows) are driving parallel product roadmaps and go-to-market plays. Understanding how these vectors evolve is critical to segment-level pricing, partnerships, and channel strategies.
-
Strategic timing — With the market poised to more than double over the decade at near-20% CAGR, 2026 is not a runway year but an execution year. Decisions made now on R&D allocation, certification roadmaps, and channel expansion will materially affect competitive positioning through 2032.
Market trajectory and macro numbers (what we disclose)
Our base-year reference is 2025. The market has grown from a low-mid-hundreds million-dollar base in 2020 to surpassing USD 200 million by 2025. From 2026 onward, PW Consulting models a robust expansion driven by enterprise adoption, regulatory compliance buys, and retail mainstreaming. Over the forecast period to 2032 the market is modeled to grow at a compound annual growth rate of approximately 19.87%, reflecting accelerating adoption curves as hardware wallets become integral to custody frameworks and personal custody solutions reach retail maturity.
We also assess market structure: concentration metrics indicate a moderately fragmented field with the top three and top five vendors controlling under one-third of market revenue — a dynamic that sustains opportunities for new entrants and niche innovators while allowing leading brands to leverage scale in certification and channel development.
Regulatory and institutional dynamics shaping demand
-
MiCA and custody segregation — The EU’s Markets in Crypto-Assets (MiCA) regime, and its Article 76 custody requirements that became fully binding in late 2024, have institutionalized the use of dedicated offline hardware wallets for client segregation. This regulatory baseline has served as a forcing function for European custodians and influenced global best-practice benchmarks.
-
US supervisory guidance and equivalence — Parallel guidance from US banking authorities and interpretations from the OCC have increased demand for hardware security modules or equivalent secure elements for qualified custody. Interpretation convergence between jurisdictions reduces cross-border uncertainty for global custody providers.
-
Certification, insurability and capital efficiency — Post-2024 changes have linked insurance terms to device-level certifications (e.g., EAL levels) and operational patterns such as multi-party control and air-gapped signing. This has both elevated engineering barriers to entry and created differentiation opportunities for certified vendors.
Competitive landscape — who’s moving the market
Our competitive mapping focuses on vendors that have combined product depth, certification progress and channel momentum to influence enterprise and retail roadmaps. The report provides deep vendor profiles, product positioning analyses and go-to-market intelligence for leading players including:
-
Ledger (Paris, France) — Known for the Nano series signers (now reframed with the “signer” nomenclature) and Flex/Stax lines, Ledger’s portfolio emphasizes broad cryptocurrency coverage and consumer-facing integration. Recent launches include a redesigned Nano Gen5 with Bluetooth Low Energy and customizable design features that increase retail appeal.
-
Trezor (Prague, Czech Republic) — A long-standing open-source player with the Trezor Safe 7 pushing into auditable secure element architectures and quantum-ready claims. Trezor’s positioning balances transparency and institutional-grade control tools.
-
Coinkite (Toronto, Canada) — A niche specialist with the Coldcard lineage focused on Bitcoin-only air-gapped signing devices. Recent product refreshes have reinforced UX and form-factor features favored by advanced users and certain institutional workflows.
-
Blockstream (San Francisco, USA) — Offers open-source, air-gapped devices geared to Bitcoin and Liquid asset workflows, emphasizing verifiable hardware provenance and developer transparency.
-
Tangem (Zurich, Switzerland) — Innovator in card-form, seedless NFC wallets targeting mass retail distribution; recent retail expansion has placed offline crypto wallets into major consumer outlets.
-
Keystone and Ellipal (Hong Kong) — Two players pursuing large touchscreen, fully air-gapped and multi-crypto approaches that speak to both retail and advanced custody use cases.
Recent product and channel moves to watch
-
Product cadence — October 2025 saw simultaneous flagship introductions from Ledger and Trezor, signaling that leading brands are racing on both hardware innovation and messaging (e.g., “signers” vs “quantum-ready”).
-
UX and form-factor differentiation — 2026 product updates show UX is increasingly a competitive frontier: larger screens, redesigned input methods, and NFC/air-gap hybrids are being prioritized to lower operational friction for both retail and enterprise operators.
-
Retail distribution and mainstreaming — Tangem’s expansion into major US retail channels highlights a pathway to consumer scale absent a pure-online model; expect more partnerships that blur retail and digital distribution.
What this report contains (practical utility)
The full PW Consulting market study is designed for executives who must transform market intelligence into strategy. It contains:
-
Quantitative market model — historic (2020–2025) and forecast (2026–2032) revenue scenarios, sensitivities and scenario-based outcomes tied to regulatory and adoption inflection points.
-
Segmentation intelligence — by region, connectivity (USB, Bluetooth, NFC and air-gapped variants) and application (retail/individual vs institutional custody). Note: core segmentation tables and granular splits are reserved for the full report to preserve competitive advantage and to enable detailed licensing.
-
Vendor dossiers — comparative product feature matrices, certification status, go-to-market channels and near-term roadmap signals for the major suppliers in the market.
-
Commercial playbooks — partner selection frameworks, certification prioritization roadmaps, pricing and margin benchmarks, and pocket-sized acquisition checklists for procurement teams.
-
Implementation guides — operational controls for custodians, integration checklists for security architects, and testing protocols aligned with EAL and secure element requirements.
-
Investment and M&A perspective — identification of value-accretive adjacencies, buy-build considerations, and an assessment of consolidation triggers given current concentration dynamics.
How enterprise leaders should use this briefing
-
CISOs and security architects — Use the report to define procurement specs that align device selection with insurer and regulator expectations. Prioritize devices with audited secure elements and documented EAL certifications where insurability is a factor.
-
Product and R&D heads — Map feature investments (e.g., air-gap UX, secure element provenance, operator tooling) to indicated demand pockets and certification pathways that unlock institutional contracts.
-
Channel and distribution teams — Determine whether to pursue mass retail playbooks, white-label OEM partnerships, or institutional partnerships with custody providers based on forecasted revenue profiles and channel economics.
-
Investors and corporate development — Leverage our scenario analysis to appraise target valuations and identify tranche-based investment strategies tied to certification milestones and go-to-market execution.
Trailer principle and next step
This preview surfaces the market drivers, regulatory inflection points, vendor dynamics and the high-level numbers that matter for 2026 planning — including a near-20% CAGR projection and a clear path toward several hundred million dollars of market opportunity by the end of the decade. To preserve the competitive value of the deep, modelled segmentation and the full set of tactical recommendations, the granular regional and application splits, price curves, and device-level revenue shares are provided exclusively in the full PW Consulting report.
Conclusion
For 2026, the Cryptocurrency Hardware Wallet Market is no longer an early-adopter niche but an operational imperative in regulated custody and a consumer product category moving toward mainstream retail presence. The convergence of regulatory requirements, insurer conditions, and product innovation creates a compressed window where decisive moves — certification investments, channel partnerships, or targeted M&A — can secure long-term positioning. PW Consulting’s full study translates the market’s macro momentum into executable steps for leaders who need to act now. Access the complete research to see the segment-level analytics, device-level comparisons and the tactical playbooks that will guide profitable decisions through 2032.
Contact PW Consulting to obtain the full report, request a tailored briefing, or license our vendor and device model for internal use.
For detailed analysis of this topic, please visit the official page: Cryptocurrency Hardware Wallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


