



PW Consulting: Oxycodone Hydrochloride Market to Hit USD 595.6M by 2032 (4.65% CAGR)

Oxycodone Hydrochloride Market — Strategic Outlook for 2026
Executive preview
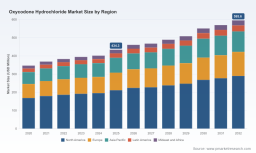
PW Consulting’s latest Oxycodone Hydrochloride Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) provides a decision-grade synthesis for executives planning resource allocation, manufacturing posture, and regulatory engagement in 2026. The global market reached USD 434.3 Million in 2025, up from USD 346.8 Million in 2020, and the study models a compound annual growth rate (CAGR) of 4.65% across the 2026–2032 forecast window, culminating in an overall market projection approaching USD 595.6 Million by 2032. These headline dynamics capture both underlying demand resilience in core therapeutic settings and structural supply-side friction that will shape strategic choices this year.
Oxycodone Hydrochloride Market
Why this study matters for 2026 decision-making
-
Timeliness: 2026 is a pivotal year — production quotas, regulatory actions and an uneven supply landscape are converging to create asymmetric risks and opportunities.
Oxycodone Hydrochloride Market -
Actionability: the report distills market evolution into operational workstreams (sourcing, manufacturing, contracting, regulatory strategy) so leaders can convert insight into execution within 90–180 day timeframes.
Oxycodone Hydrochloride Market -
Competitive posture: with a concentrated supplier base and high vulnerability for certain dosage forms, competitive moves (capacity expansions, targeted M&A, specialty partnerships) will materially affect access and margin profiles.
-
Scenario readiness: our scenario models quantify the impact of supply shocks, regulatory delistings and quota shifts on revenue, inventory days, and service levels — enabling stress-tested planning rather than intuition-driven responses.
Market dynamics: drivers, constraints and inflection points
Two themes dominate the near-term narrative. First, demand remains stable across core clinical applications, underpinned by a baseline of legitimate medical need and an aging patient demographic in developed markets. Second, supply-side complexity is intensifying: API quotas, regulatory withdrawals, and episodic product discontinuations are compressing available inventory and raising execution risk for manufacturers and distributors alike.
-
Regulatory/Quota environment: the DEA’s 2026 aggregate production quota for oxycodone establishes the production envelope for the calendar year and has immediate operational implications for API procurement and contract manufacturing scheduling.
-
Regulatory delistings and approvals: recent administrative actions — including withdrawals of specific approvals for certain oral solutions — demonstrate that approval status can change rapidly and should be continuously monitored as an operational risk.
-
Structural shortages: independent vulnerability listings and shortage databases continue to flag oxycodone tablets as structurally at risk. That status increases the premium on redundancy and validated second-source suppliers for customers and payors.
Collectively, these forces mean that 2026 planning must prioritize supply assurance and regulatory agility as much as market-share plays.
Competitive landscape — what leaders should know
The market remains moderately concentrated: the top three players account for a significant portion of market supply, and the top five increase that concentration further. This concentration creates both bargaining power for incumbent suppliers and systemic vulnerability when one or more large manufacturers change capacity or product availability.
-
Endo USA, Inc. (Malvern, PA) — A primary manufacturer and marketer of branded oxycodone/acetaminophen formulations; maintains production capabilities for immediate‑release forms. Recent discontinuations underscore how portfolio decisions by a single incumbent can affect market availability for specific dosage strengths.
-
Par Health (Malvern, PA) — An active generics and API-capable supplier evolving through portfolio restructuring; retains manufacturing operations previously associated with legacy companies. The rebranding and consolidation activities indicate a strategic focus on integrated supply solutions.
-
KVK‑Tech, Inc. (Somerset, NJ) — A supplier noted in shortage monitors for immediate‑release oral tablets; represents a valuable short‑term capacity node but also exemplifies the fragile nature of distributed generic production.
-
Rhodes Pharmaceuticals L.P. (Columbia, MO) — A generics manufacturer supplying standard oral tablet strengths; its role illustrates the importance of commercial distribution networks in maintaining on‑market availability.
-
Amneal Pharmaceuticals (Bridgewater, NJ) — Active in immediate‑release generics and listed as an available supplier in shortage tracking; its continued participation is a stabilizing factor for purchasers.
-
Elite Pharmaceuticals, Inc. (Fort Lauderdale, FL) — Recently launched generic oxycodone/acetaminophen products and represents new entrant competition that can reshuffle short‑term supply dynamics and pricing.
These firm-level vignettes in the report are paired with a proprietary competitive map and supplier-risk scoring. The full analysis draws on manufacturing footprints, regulatory event histories, and shortage-data correlations to indicate which supplier disruptions would have system‑wide consequences versus localized impacts.
What the full report contains (operational, not just descriptive)
-
Top-line market sizing and growth trajectories (2020–2025 history; 2026–2032 forecast). Our models show the market scaling from recent base to projected mid‑cycle levels under multiple scenarios.
-
Demand segmentation and end‑use dynamics with granular scenarios for chronic vs. acute care demand shifts (note: granular segment tables are intentionally withheld from this preview to preserve proprietary modeling value).
-
Supply‑chain topology and single‑point‑of‑failure mapping across API, formulation, and distribution layers.
-
Regulatory event tracker and timeline: continuous monitoring templates for quota announcements, ANDA outcomes, and shortage-list movements.
-
Financial impact matrices: EBITDA sensitivity to price moves, capacity outages, and payer contracting changes.
-
Scenario suite (mild disruption, moderate shortage, severe supply shock) with tactical playbooks for procurement, inventory, and commercial response.
-
M&A and partnership shortlists: prioritized targets and value levers for firms seeking to secure capacity or accelerate market entry.
-
Executive decision dashboards and 90/180/360‑day action roadmaps tailored for manufacturers, wholesalers, and payer procurement teams.
Strategic imperatives for 2026 (prioritized)
-
Lock in supply via diversified API contracts: Given the fixed annual production envelope established by quota authorities, buyers should secure multi‑tier API contracts with clear ramp provisions and fallback sourcing to mitigate allocation risk.
-
Build validated secondary manufacturing paths: Manufacturers and large wholesalers must prioritize validation of secondary CMOs for core strengths to reduce patient impact in case of primary plant downtime or product discontinuation.
-
Embed regulatory monitoring into operations: Maintain a real‑time regulatory feed (approvals/withdrawals, quota notices, shortage lists) integrated into supply‑planning systems so capacity plans can be reweighted within days rather than weeks.
-
Adopt scenario-based contracting: Use contingent contracts and staggered purchasing mechanisms that account for shortage states while preserving price discipline in normal markets.
-
Prioritize portfolio resilience over marginal share gains: Tactical launches or incremental contract wins that rely on fragile single-source supply are high risk; prioritize sustainable, contractible volumes backed by validated capacity.
-
Evaluate M&A and partnership options selectively: Target assets that provide API vertical integration, niche dosage form capabilities, or flexible manufacturing lines that can be retooled quickly.
-
Engage payers and health systems proactively: Work with purchasers to design substitution protocols and shortage contingencies that protect therapeutic continuity without eroding margins unnecessarily.
Implications and next steps
2026 will reward organizations that translate market visibility into operational resilience. The convergence of a fixed production envelope, active shortage listings, and discrete regulatory actions means that the marginal value of reliable supply and regulatory intelligence is higher than in prior cycles. Tactical measures taken in the first half of 2026 — securing diversified API supply, validating secondary manufacturing partners, and embedding real‑time regulatory feeds into operations — will materially reduce downside revenue volatility and reputational risk.
PW Consulting’s full study provides the granular, downloadable models, supplier scoring, and contract templates necessary to operationalize these recommendations. The report is expressly structured to help C‑suite leaders and operational heads create a 90–180 day mitigation plan and a 3‑year strategic playbook for sustained performance.
How to use this preview
Consider this piece a curated executive trailer: it outlines the market architecture, the levers that matter in 2026, and the prioritized actions to reduce exposure. If your team must decide on capital allocation, contract negotiations, or M&A moves before Q3 2026, the full study contains the proprietary segmentation, supplier-level exposures, and financial sensitivity tables you will need to convert strategy into implemented outcomes.
For detailed analysis of this topic, please visit the official page: Oxycodone Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


