



PW Consulting: PSPI Market to Surge to USD 590.2M by 2032 at 21.8% CAGR

Photosensitive Polyimide (PSPI) Market — Strategic Briefing for 2026 Decisions
PW Consulting presents a targeted industry briefing designed to equip corporate leadership and strategy teams with the high-level intelligence required to make decisive moves in 2026. This note synthesizes our latest market sizing, structural dynamics, competitor posture, and regulatory risk map for Photosensitive Polyimide (PSPI) — while intentionally reserving the detailed segmentation tables, pricing curves, and supplier scorecards for the full report.
Photosensitive Polyimide (PSPI) Market
Market at a glance — the big-picture metrics that matter
- Historical momentum: PSPI moved from approximately USD 55.2 Million (2020) to USD 150.0 Million (2025), reflecting rapid adoption across advanced packaging and display processes.
- Near-term trajectory: our base year is 2025; the market is projected to continue strong expansion into the forecast window. The first full forecast year (2026) is projected at roughly USD 179.0 Million.
- Longer-term scale: by the end of the forecast period, the PSPI market is projected to reach approximately USD 590.2 Million (2032).
- Growth intensity: the compound annual growth rate (CAGR) for the forecast window (2026–2032) is 21.8%, signaling an industry moving from niche specialty-chemical status to strategically significant materials for semiconductor and display ecosystems.
- Market concentration: the industry exhibits a relatively consolidated supplier base (top-3 firms control a dominant share, and the top-5 further consolidate scale), underscoring the strategic impact of capacity moves and customer qualification timelines.
Why 2026 is a strategic inflection point
Several concurrent vectors make 2026 an actionable year for executives: capacity additions announced in 2024–2025 begin commissioning, regulatory transition timelines around certain solvent systems accelerate, and end-market demand (driven by advanced packaging, wafer-level processes, and flexible display lamination) enters a steeper adoption curve. These forces compress decision windows: ordering and qualification lead times for new PSPI grades, long-cycle capital investments by suppliers, and multi-year supply agreements all require clarity from buyers and strategic planners now.
Photosensitive Polyimide (PSPI) Market
From a capital-allocation perspective, the combination of high CAGR and concentrated supply means that first-mover advantage in securing qualified supply or owning differentiated chemistries can materially affect cost-of-goods and time-to-market for advanced packaging and display OEMs.
Photosensitive Polyimide (PSPI) Market
Competitive landscape — who to watch (and why)
The PSPI supplier layer is populated by long-established polymer houses and specialty-chemical players that combine deep formulation know-how with semiconductor qualification capabilities. Our qualitative assessment of the competitive set highlights three tiers:
- Global leaders with scale and integration advantages: companies that have invested in purpose-built PSPI capacity and maintain close relationships with semiconductor foundries and OSATs. Recent capacity programs and customer awards validate their strategic alignment with advanced packaging roadmaps.
- Regional specialists with targeted propositions: players focusing on particular end-markets (e.g., DRAM/logic packaging clusters or OLED panel supply chains) who leverage proximity and co-development to win design-ins.
- Technology differentiators and niche formulators: smaller firms focused on specialized chemistries (e.g., radiation-hardened PSPI, solvent-free formulations, or sub-5 nm optimized materials) that address specific technical windows of opportunity.
Representative firms that appear across our competitive matrix include manufacturers that have publicly announced capacity or product initiatives in 2024–2025 and early 2026. Examples of recent strategic moves that shaped vendor dynamics:
- A major Japanese supplier announced a multi-year capacity expansion program at a flagship facility and received customer recognition for its PSPI grades in late 2025 — a move that materially improves its ability to serve advanced packaging demand.
- A specialist materials vendor launched enhanced PSPI formulations optimized for sub-5 nanometer packaging in 2025, signaling a race to align chemistries with shrinking design rules.
- Regional producers in South Korea and Taiwan expanded electronic-materials production footprints in 2025 to capture demand from leading memory and OSAT clusters.
These public actions underscore an important strategic reality: capacity and qualification cycles now overlap with product-cycle windows in semiconductor roadmaps. Market share gains will therefore accrue to suppliers that align production ramp timing with customer qualification schedules and regulatory-compliant formulations.
Dynamics and risk matrix — the practical headwinds
- Raw material pressure: precursors for PSPI (for example, polyamic acid and certain diamines/dianhydrides) experienced material cost increases in recent years. These input cost shifts have compressed supplier margins and are being managed through a mix of price pass-throughs, formulary reformulation, and efficiency programs.
- Regulatory transition: solvent systems used in some PSPI processes face increasing regulatory scrutiny. The European REACH designation of certain solvents as high-concern substances, coupled with evolving EPA guidance, is accelerating reformulation programs and increasing product development costs for compliant aqueous or alternative-developer chemistries.
- Supply-chain fragility: geopolitical friction and logistics constraints have extended lead times in some geographies by multiple weeks. For buyers with just-in-time inventory models, this creates operational vulnerability during ramp periods.
- Qualification latency: semiconductor-grade PSPI qualification cycles are lengthy and multi-staged. Customers contemplating supplier changes must factor in several quarters (or more) of co-development, reliability testing, and process integration.
In short: margin, compliance, and lead-time pressure converge. Firms that proactively hedge input exposure, accelerate REACH/EPA-compliant reformulations, and secure multi-sourcing or strategic supply partnerships will materially reduce execution risk.
What our full report delivers — practical assets for 2026 execution
The full PW Consulting PSPI Market Report combines rigorous market sizing with operational playbooks. Key deliverables that strategy and procurement teams will find immediately actionable include:
- Validated market-sizing model (historical 2020–2025 and forecast 2026–2032) with sensitivity scenarios tied to packaging nodes and display adoption curves.
- Demand-driver decomposition and event calendar that maps customer qualification windows, key foundry/OSAT milestones, and anticipated ordering cliffs.
- Supplier capacity-mapping and utilization model that highlights near-term bottlenecks and probabilistic timing for incremental tonnage availability.
- Cost-of-supply and input-cost passthrough analysis with scenario-level margin impact for manufacturers and buyers.
- Regulatory-compliance matrix: solvent-phase-out timelines, reformulation cost estimates, and recommended control points for internal product teams.
- Competitive benchmarking: product-positioning scorecards, innovation vectors (e.g., solvent-free PSPI, radiation-hardened variants), and supplier readiness assessments.
- Commercial playbooks: supplier selection criteria, negotiation levers (e.g., co-investment, exclusive supply windows, dual-sourcing triggers), and RFP templates aligned to semiconductor qualification cadence.
- M&A and partnership targets: a prioritised list of tuck-in candidates and joint-development partners, with rationale and three execution pathways (minority investment, JV, full acquisition).
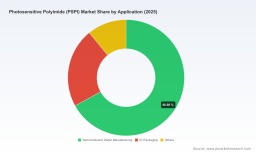
Note: the report intentionally excludes publicly reproducing granular regional and application split percentages in this briefing. Those discrete segmentation layers — central to procurement and investment decisions — are accessible in the full intelligence package.
A prioritized 6–12 month action agenda for 2026
- Immediate (0–3 months): Run a rapid supplier health check — validate lead times, confirm reformulation roadmaps for regulatory compliance, and map qualification timelines for critical PSPI grades.
- Short term (3–6 months): Secure conditional capacity through supply agreements or co-investment structures tied to milestone-based take-or-pay terms; accelerate internal material-substitution pilots where solvent exposure is a compliance risk.
- Medium term (6–12 months): Align product roadmaps with qualified PSPI suppliers and lock integrated process windows (Cpk, thermal budgets) into development milestones; build scenario models for inventory and hedging that reflect lead-time variability.
- Strategic: Evaluate M&A or JV opportunities to internalize critical chemistry capabilities if your roadmap requires differentiated PSPI formulations that are unlikely to be served by commodity suppliers.
Concluding perspective — why our intelligence matters for your 2026 choice
PSPI is transitioning from a specialty niche to a strategic materials category for a wide set of semiconductor and display applications. The combination of rapid demand growth (projected CAGR of 21.8% in the forecast window), concentrated supply, and regulatory shift creates both asymmetric upside for first movers and downside for firms that delay qualification or securement actions.
PW Consulting’s report is designed to be directly operational: not a descriptive industry primer but a decision support toolkit for procurement chiefs, product leaders, and M&A teams. Our objective is to shorten your risk-adjusted time-to-decision by providing validated market math, supplier-readiness diagnostics, and executable commercial templates.
To access the full dataset, the supplier-by-supplier scorecards, the detailed regional and application splits, and the workbook models that underpin the scenarios summarized here, please visit the PW Consulting report page. The full intelligence contains the granular inputs you will need to finalize 2026 capital allocations, supplier agreements, and product qualification plans.
For detailed analysis of this topic, please visit the official page: Photosensitive Polyimide (PSPI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


