



PW Consulting: Medical Tapes Market to Expand at a 6.1% CAGR Through 2032

Medical Tapes Market — Strategic Outlook to 2032 (PW Consulting Preview)
Executive snapshot
This preview introduces PW Consulting’s forthcoming Market Research on the Medical Tapes sector. It synthesizes the top-line market trajectory and the practical implications for executive decision-making in 2026, while deliberately withholding full segment-level tables and granular regional splits to preserve the “trailer” purpose of this note. Our full intelligence pack includes the complete dataset, scenario models and supplier scorecards available on the report landing page.
Medical Tapes Market
Macro trajectory: what the numbers imply for strategy
Between 2020 and the report base year of 2025 the medical tapes market registered steady expansion, and our forecasting model projects continued growth through 2032 at a compound annual growth rate (CAGR) of 6.1%. In revenue terms (USD, Million), the market is modeled from the 2025 baseline and is expected to approach the high‑two‑hundreds by 2032. This pace of growth is meaningful for prioritization: a mid-single-digit CAGR in a global medical-device-adjacent category supports disciplined reinvestment in product development, clinical evidence generation and commercial expansion without requiring the kind of hyper-scale investments seen in high-growth platform plays.
Medical Tapes Market
Why this research matters to 2026 decision-makers
- Portfolio prioritization: Understand which tape types and clinical use-cases are structurally attractive and merit R&D or commercialization resources in the next 18–36 months.
- Regulatory planning: Align 510(k) submission sequencing and ISO 10993 testing strategy with market-entry timelines to avoid costly launch delays.
- Procurement & pricing: Prepare tender responses and pricing models that reflect payer preferences for validated wear performance and low-trauma materials.
- M&A and partnership screening: Identify capability gaps where bolt-on acquisitions or co-development agreements can accelerate market entry (materials science, adhesive technology, patient-centric securement devices).
- Supply chain and sourcing: Quantify the resilience and cost exposure of key substrates and adhesives to material price volatility.
Demand-side drivers and clinical dynamics
Multiple structural forces are converging to sustain demand for medical tapes through the forecast horizon. Demographic trends and the global burden of chronic wounds remain core, while the increasing frequency of ambulatory procedures and expansion of home healthcare and remote monitoring are creating new use-cases for securement and gentle-skin adhesion. The rise of wearable medical devices and continuous monitoring systems has also elevated the commercial value of tapes that combine strong securement with low-skin trauma.
Medical Tapes Market
Clinical preferences are shifting too. Silicone-based low-trauma adhesives are increasingly accepted as the clinical standard in many care settings due to reduced epidermal injury compared with traditional acrylates. Procurement teams and hospital formularies are placing higher emphasis on products backed by formal wear-time data; reimbursement and tender outcomes are being influenced accordingly. These dynamics mean that material innovation and clinical validation are not just technical priorities, they are commercial imperatives.
Supply-side dynamics and competitive landscape
The market structure is best described as competitive with room for scale advantages but no single dominant incumbent. The top manufacturers collectively capture less than half of total market value, leaving meaningful share and margin opportunities for focused entrants and specialist players. Competing firms distinguish themselves through adhesive chemistry, substrate engineering, clinical evidence and go-to-market reach.
- 3M Company – Large global portfolio spanning surgical and securement tapes; leverages brand, distribution and breadth of product families to hold an advantaged commercial position in institutional channels.
- Avery Dennison Medical – Focused on pressure-sensitive adhesive films and skin-friendly constructions; active in industry forums and trade shows to showcase innovations for clinical and wearable applications.
- Solventum Corporation – Specialized in patient monitoring securement and management solutions; differentiation through integrated securement devices and adhesive systems.
- Paul Hartmann AG – European-based strength in adhesive fixation and elastic tapes with a clinical orientation toward wound management and compression applications.
Recent corporate activity signals the ongoing importance of product demonstration and clinician engagement. For example, Avery Dennison amplified its market-facing presence at major trade events in consecutive years, underscoring an active commercialization and product-awareness strategy that competitors should monitor.
Regulatory & procurement environment — timing matters
Regulatory pathways and procurement rules have direct commercial consequences. FDA 510(k) clearances remain a common route for market access in the U.S.; average review times reached approximately 140–175 days in 2025 for device submissions in adjacent categories, which should be factored into launch calendars and inventory planning. Equally, ISO 10993 biocompatibility testing is a decisive procurement requirement in many hospital tenders—suppliers without robust biocompatibility documentation face systemic disadvantages.
Procurement bodies are also incorporating objective wear-performance and skin-compatibility data into evaluation criteria. Reimbursement policies increasingly favor products with validated clinical and wear outcomes, which raises the bar for entrants relying solely on price competition.
Materials, costs and supply resilience
Material choice drives both clinical differentiation and exposure to commodity swings. Silicone adhesives command a price premium relative to traditional acrylics, but they deliver demonstrable reductions in skin trauma and an increasingly accepted clinical value proposition. Manufacturers and buyers must balance cost pressures against clinical outcomes—decisions that will influence margin dynamics across the value chain. For risk-averse purchasers, supplier resilience and documented quality (including ISO and biocompatibility certifications) have become procurement filters as important as unit price.
Report deliverables — practical tools inside the full study
The full PW Consulting report converts insight into execution with an emphasis on tools executives can use immediately:
- Market model (2020–2032) with base, upside and downside scenarios and sensitivity levers for material cost and reimbursement shifts (USD, Million).
- Opportunity maps by product type and clinical use-case, highlighting addressable revenue pockets and margin bands.
- Supplier benchmarking templates and a procurement scorecard that weights clinical evidence, regulatory readiness and supply resilience.
- Regulatory roadmap matrix (ISO 10993 requirements, 510(k) sequencing and typical dossier timelines) with recommended testing budgets and milestone gates.
- Commercial playbook for launch sequencing, tender strategies and clinician engagement programs designed for 2026 market entry windows.
- M&A screening filters and a short-list of capability gaps where strategic acquisitions deliver immediate route-to-market or technology lift.
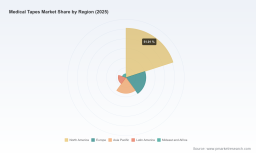
Note: this preview omits the detailed regional, type and application-level breakout tables included in the full study—those datasets and manipulable spreadsheets are accessible only through the full report package.
Actionable strategic priorities for 2026
- Prioritize development and commercialization of silicone low‑trauma tape variants where clinical preference and tender scoring favor validated wear performance; allocate budget to comparative wear studies early.
- Secure ISO 10993 and other relevant certifications as a near-term gating item for institutional procurement; align testing timelines with projected launch dates to avoid market lag.
- Design go-to-market pilots focused on ambulatory surgery centers and remote-monitoring device OEMs to capture growing demand outside traditional inpatient channels.
- Hedge material cost exposure via diversified supply agreements and indexed contracts for key substrates and adhesives; model margin impacts under multiple commodity price scenarios.
- Consider bolt-on acquisitions to acquire niche adhesive chemistry, device securement expertise or regional distribution where inorganic routes accelerate scale more efficiently than organic investment.
Risks and upside to monitor
Primary downside risks include slower-than-expected adoption of premium adhesives due to cost pressure, regulatory delays in key markets, and raw material inflation. Upside scenarios hinge on rapid clinical acceptance of low‑trauma adhesives, successful integration of tapes with digital monitoring devices, and accelerated procurement reforms that recognize total cost of care benefits from superior products.
Conclusion — why now
An orderly but purposeful investment approach is the dominant recommendation for 2026. The market’s mid-single-digit CAGR supports selective R&D and commercialization spending while preserving optionality for consolidation moves. PW Consulting’s full report converts the macro trajectory, supplier dynamics and regulatory nuance described here into a prioritized set of decisions, timelines and investment estimates tailored to executive and commercial teams planning activity in 2026.
To access the complete dataset, segment-level analysis, and the practical toolset (including the editable financial model and supplier scorecards), visit the full report page. The full pack is structured to guide immediate 90‑ to 180‑day planning for product launches, procurement bids and M&A screening.
For detailed analysis of this topic, please visit the official page: Medical Tapes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


