



PW Consulting: Oncology Drugs Market to Hit USD 395,000M by 2032 at 10.5% CAGR

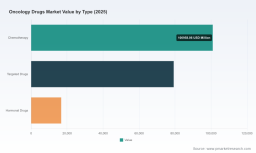
Oncology Drugs Market: Strategic Insight Briefing for 2026 Decision‑Making
Executive overview
By 2025 the global oncology drugs market had reached a new scale, and our base-year assessment (2025) confirms a trajectory that will reshape commercial priorities across R&D, market access, manufacturing and M&A. PW Consulting’s market model—built on a historical window (2020–2025) and a forward forecast horizon (2026–2032)—projects a compound annual growth rate (CAGR) of 10.5%. Under the central scenario, the market expands from the 2025 baseline to reach the order‑of‑magnitude endpoint set for 2032, reflecting persistent volume and price dynamics driven by targeted therapies, immuno‑oncology advances, and evolving reimbursement frameworks.
Oncology Drugs Market
Why this matters for 2026 planning
- Timing matters: 2026 is the inflection year for several systemic changes—regulatory approvals, new launch modalities, and the first full-year impact of negotiated pricing rules in key markets. Companies need decision frameworks that convert headline growth into defensible unit economics.
- Investment prioritization: A sustained double‑digit CAGR demands disciplined portfolio choices. Firms must decide whether to accelerate late‑stage development, double down on commercial scale-up for existing launches, or deploy capital into adjacencies (diagnostics, combination regimens, supportive care).
- Access and pricing strategy: Aggregate growth masks tightening payer scrutiny in major markets. Pricing negotiations, new reimbursement paradigms and value‑based contracting are shifting the capture rate for novel modalities.
Market trajectory in numbers (selective, high level)
Our consolidated model shows a clear, steady expansion from the 2020 historical base through the 2025 benchmark and into the forecast window. The trajectory implied by a 10.5% CAGR translates into substantial aggregate growth through 2032—growth driven by a mix of new indications, formulation innovations, and the continued migration from cytotoxic agents toward targeted and immunomodulatory approaches. PW Consulting’s full forecast includes multiple scenarios (base, upside, downside) and sensitivity analyses around pricing pressure and launch success rates to help quantify upside and downside for corporate planning.
Oncology Drugs Market
What the PW Consulting report delivers (practical, transaction-ready outputs)
- Integrated market model (Excel + interactive dashboard): top‑down and bottom‑up forecasting engines with scenario toggles for approval timing, price erosion, and penetration curves. Note: detailed indication‑ and region‑level tables are included in the full deliverable and intentionally not reproduced here.
- Pipeline valuation and launch heatmaps: probabilistic success rates, peak sales estimates, and launch sequencing recommendations to inform portfolio prioritization and capital allocation decisions.
- Access and reimbursement playbooks: payer segmentation, likely negotiation levers by country grouping, and mitigation strategies for price compression scenarios.
- Commercial readiness templates: sales force sizing tools, channel selection matrices, and patient‑support program blueprints calibrated to different launch types (IV, SC, oral, combination).
- M&A and partnership screening: target scoring framework for tuck‑ins, bolt‑ons, and strategic alliances, with guidance on valuation multipliers under varying regulatory and pricing regimes.
- Regulatory and HTA tracker: rolling updates for approval milestones, label expansions, and HTA decisions with impact flags mapped to revenue risk buckets.
- Risk register and contingency plans: manufacturing constraints, supply chain disruptions, and litigation/competition scenarios with actionable mitigation steps.
Competitive landscape — what to watch in 2026
The oncology market is commercially concentrated: the top three players account for a majority share, with the top five increasingly dominant. That concentration creates both defensive moats and strategic openings for challengers that can combine differentiated clinical benefit with access-savvy launch plans.
Oncology Drugs Market
- Merck & Co., Inc. (Rahway, NJ) — Merck’s immuno‑oncology franchise has been a category definer. For incumbents and newcomers alike, Merck’s commercial scale and broad label footprint mean that combination strategies and niche positioning will be necessary to compete effectively.
- AstraZeneca PLC (Cambridge, UK) — Strength in lung and targeted therapy segments positions AstraZeneca to capitalize on biomarker‑driven indications. Its execution on sequencing and label expansions will be a bellwether for the class.
- Bayer AG (Leverkusen, Germany) — With a mix of radiopharmaceuticals and targeted TKIs in its portfolio, Bayer’s trajectory highlights the commercial potential of emerging modalities when backed by clear diagnostic strategies.
- Eli Lilly and Company (Indianapolis, IN) — Lilly’s expansion in targeted therapies and endocrine niches underscores the strategic value of focused therapeutic differentiation supported by robust outcomes data.
- Gilead Sciences, Inc. (Foster City, CA) — Gilead’s emphasis on hematologic combinations and cell therapy adjacencies shows a playbook oriented to partnerships and regimen innovation rather than standalone small‑molecule dominance.
- Amgen Inc. (Thousand Oaks, CA) — Amgen balances biologics and small‑molecule offerings; its commercial advantage lies in integrated patient support and an ability to scale specialty distribution rapidly.
- Sanofi (Paris, France) — Sanofi’s portfolio strategy emphasizes supportive therapies and line extensions, a route that can deliver durable revenue with modest commercial risk.
- Novartis AG (Basel, Switzerland) — Novartis continues to invest in targeted kinases and supportive care agents, leaning on precision medicine to sustain premium pricing where evidence supports it.
- F. Hoffmann‑La Roche AG (Basel, Switzerland) — Roche’s broad oncology footprint and diagnostics capability remain a structural advantage for combination strategies and companion diagnostic rollouts.
- Bristol‑Myers Squibb Company (New York, NY) — BMS’s immuno‑oncology assets and combination regimen experience make it a default comparator in many strategic analyses; watch for partnership plays that extend reach into new tumor types.
- AbbVie Inc. (North Chicago, IL) — AbbVie’s focus on hematologic malignancies and oral agents highlights niches where reimbursement dynamics differ materially from solid tumors.
Regulatory and access dynamics shaping 2026
- Policy shifts on pricing and negotiation will materially affect net realized prices. The implementation of negotiated pricing mechanisms for selected oncology agents and executive directives on pricing targets are already altering go‑to‑market assumptions for launches scheduled in 2026 and beyond.
- FDA activity remains brisk: the recent cluster of approvals, label expansions and new formulations underscores both opportunity and complexity. Accelerated approvals and breakthrough designations continue to compress time‑to‑market for high‑need indications, but also increase the importance of confirmatory evidence and real‑world evidence (RWE) strategies.
- Administration and payer action on pricing transparency and most‑favored‑nation style frameworks raise the bar for global pricing strategies. Companies must design launch price points with likely downstream negotiation outcomes in mind.
Implications for corporate strategy (operational priorities for 2026)
- Recalibrate launch playbooks: align evidence generation with payer requirements in the first 24 months post‑approval; the most successful launches will combine strong clinical differentiation with a payer‑oriented evidence plan.
- Prioritize combination and biomarker strategies: differential clinical benefit tied to a diagnostic pathway is the clearest path to premium access in an increasingly cost‑conscious environment.
- Optimize capital allocation: use the report’s scenario outputs to stress‑test R&D portfolios, weigh in‑licensing versus internal development, and set realistic thresholds for M&A targets.
- Build flexible commercialization models: hybrid distribution, hub services and digital patient engagement will be key enablers for preserving uptake under access pressure.
- Invest in RWE infrastructure: robust real‑world evidence programs mitigate approval risk, accelerate HTA acceptance, and smooth negotiations on value‑based arrangements.
How to use this briefing
This briefing is a strategic primer designed to orient executive teams, corporate development committees and commercial planners ahead of 2026. PW Consulting’s full Oncology Drugs Market report contains the granular datasets, regional and indication forecasts, competitive share tables and downloadable models you will need to convert these insights into decisions. In keeping with the “trailer” principle here, specific region‑by‑indication tables and the full numeric splits are available only in the report package and online portal.
Next steps
- Request the interactive model to run custom scenarios for portfolio stress‑testing and near-term cash flow projections.
- Engage our deal‑strategy team for a rapid target scan using the report’s M&A scoring engine.
- Commission a payer readiness review to align planned launches with the most likely 2026 reimbursement pathways in your target markets.
PW Consulting’s Oncology Drugs Market study is built to be immediately operational: it pairs a defensible macro forecast with tactical templates that accelerate board‑level and field‑level decision‑making in 2026. For full access to the underlying datasets, indication‑level forecasts, and the downloadable scenario model, visit the PW Consulting report page or contact your client partner.
For detailed analysis of this topic, please visit the official page: Oncology Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


