



PW Consulting: E-waste recycling market from USD 80.8B (2025) to USD 195.46B by 2032 at 13.5% CAGR

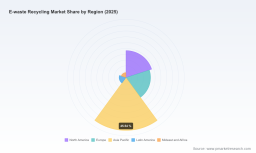
E-waste Recycling Market: Strategic Imperatives for 2026
Executive summary
By 2025 the global e-waste recycling market has evolved from a niche compliance activity into a strategic battleground for material security, circular product design, and corporate sustainability delivery. Our base-year calibration (2025) shows a market that expanded rapidly over the past half-decade — rising from roughly USD 31 Billion in 2020 to an estimated USD 80.8 Billion in 2025 — and is projected to continue that trajectory through the current forecasting window (2026–2032) at a compound annual growth rate of approximately 13.5%. By 2032, the market size is modeled to approach the upper hundreds of billions under the central case, driven by accelerating electronics lifecycles, battery recycling demand, and policy-driven collection targets.
E-waste Recycling Market
This briefing, prepared by PW Consulting’s Strategy & Industry Analysis practice, outlines why our 2026 report is immediately actionable for executives who must translate macro momentum into defensible strategic moves. It also follows a deliberate ‘trailer’ approach: we surface the analytical framework, the decision-useful outputs, and the competitive contours, while preserving the full segmentation tables and scenario matrices for subscribers who access the complete report.
E-waste Recycling Market
Why this market matters for 2026 decision-making
- Material security and input-cost arbitrage: Electronics and battery supply chains are increasingly exposed to volatile critical material prices and sourcing constraints. Recycled streams create a hedge and can alter procurement and inventory strategies across OEMs and Tier-1 suppliers.
- Regulatory inflection points: New producer-responsibility regimes, collection mandates, and export restrictions are becoming mainstream in major economies, transforming compliance spend into strategic capex and partnership choices.
- Value migration from services to upstream inputs: Service providers that combine IT asset disposition (ITAD), secure data removal, and industrial-scale metallurgy can capture margins previously concentrated in primary smelting and mineral markets.
- Scale opportunity for investors: The underlying CAGR-driven growth creates multiple pockets for M&A, roll-ups, and platform investments — particularly where operational scale unlocks improved recovery yields and ESG credentials.
Market trajectory and practical implications
Historical growth between 2020 and 2025 demonstrates both structural and cyclical drivers: rising electronics consumption, shortened product replacement cycles, and intensified regulatory pressure. The 2026–2032 forecast window embeds three scenarios — conservative, central, and accelerated — each reflecting different assumptions about collection rates, material prices, and technological adoption in downstream metallurgy and battery recycling. Across scenarios, the central projection supports a sustained double-digit expansion, making 2026 a pivot year for corporates to decide between incremental scaling versus platform plays.
E-waste Recycling Market
For corporate strategists, this implies a decision taxonomy for 2026 that distinguishes between:
- Defensive moves (securing recycling capacity and compliance coverage in core markets),
- Offensive plays (vertical integration into material processing, or premium service bundles combining refurbishment + resale), and
- Portfolio choices for investors (roll-up strategies, minority stakes in technology providers, or long-term offtake contracts tied to recovered commodities).
Key market dynamics shaping 2026 strategy
- Technological diffusions: Emerging metallurgical processes and battery-specific treatments are shifting recoverable value upwards. Early industrialization partnerships between recyclers and advanced materials firms are accelerating the viability of closed-loop feedstocks for new electronics and EV batteries.
- Service convergence: The line between ITAD, refurbishment services, and raw-material recycling is blurring. Integrated service providers that can offer data security, resale channels, and high-yield material recovery win both sustainability KPI budgets and aftermarket revenue.
- Market fragmentation: Despite global growth, the competitive landscape remains fragmented — concentrated incumbents exist but a large fraction of capacity is held by regional and specialist players. This dynamic creates significant arbitrage for consolidation and strategic partnerships.
- Commodities and price sensitivity: Recovered metal and material prices materially affect recycler economics. Short-term revenue variability from metals pricing necessitates hedging, diversified revenue models, or long-term contracts to stabilize returns.
Competitive landscape — what to watch in 2026
Our competitive mapping focuses on firms that exemplify strategic pathways across scale, specialization, and certification. Three profiles illustrate the range of winning models:
- Umicore (Hoboken, Belgium)
Positioning: Advanced materials and precious-metal refining depth; industrial-scale recovery of complex e-scrap. Strategic moves: strengthening downstream industrial partnerships to supply recycled precursors for battery anodes and other advanced materials. Recent signal: solid near-term revenue growth in recycling operations and an announced partnership to industrialize silicon-anode material pathways — indicating a vertical play into EV battery supply chains.
- Sims Limited / Sims Lifecycle Services (Melbourne, Australia)
Positioning: ITAD and large-volume electronics processing with global refurbishment and material-recovery channels. Strategic moves: differentiation via recognized sustainability credentials and scale in flows that feed both reuse and recycling markets. Recent signal: third-party recognition for electronics sustainability, which reinforces trust with large OEMs and corporate customers seeking audited circular solutions.
- AER Worldwide (Fremont, California, USA)
Positioning: Certified e-waste recycler focused on secure disposition and R2/RIOS compliance; niche strength in regulated supply chains and sensitive ITAD requirements. Strategic moves: leveraging certifications to win enterprise contracts where regulatory and data-security risk premiums are material.
Implication: 2026 competition is a three-dimensional game — scale, technology, and trust. Winning platforms will combine at least two of these attributes and demonstrate credible pathways from feedstock procurement to high-value recovered outputs.
What the PW Consulting report delivers (practical content you can operationalize)
Our full report goes beyond descriptive market sizing to provide executable tools for decision-makers. Highlights include:
- Decision frameworks for go/no-go capital allocation across greenfield recycling facilities, modular retrofit options, and long-term offtake agreements.
- Playbooks for OEMs to design reverse-logistics pilots, align product design incentives with recyclability, and structure extended producer responsibility (EPR) engagements.
- Due-diligence checklists and valuation multipliers tailored to e-waste recyclers, ITAD specialists, and metallurgical processors — capturing margin drivers, regulatory exposures, and recovery-rate sensitivities.
- Technology adoption roadmaps and an assessment matrix that ranks hydrometallurgy, pyro-metallurgy, mechanical separation, and emerging battery-specific chemistries by maturity, CAPEX intensity, and recovery profiles.
- Supply-chain heatmaps identifying node-level risk (collection bottlenecks, export constraints, and logistics limitations) and recommended mitigations.
- Scenario-based P&L models and stress tests that quantify the profit impacts of commodity-price swings, incremental collection rate improvements, and new regulatory scenarios across the 2026–2032 forecast horizon.
Actionable strategic recommendations for 2026
- For OEMs and Tier-1 suppliers: Prioritize pilot investments in closed-loop feedstocks for strategic components (batteries, PCB precious metals). Negotiate long-term offtake terms with recyclers to stabilize input costs and secure ESG claims.
- For recyclers and ITAD providers: Invest selectively in technology partnerships that raise recovery yields for high-value streams and obtain recognized certifications to capture enterprise contracts with higher ASPs.
- For private equity and corporate M&A teams: Target bolt-on acquisitions that deliver immediate scale in collection channels or materially improve recovery economics — and price-in the cost of rapid compliance roll-outs across priority markets.
- For policy and sustainability leaders: Align corporate lobbying and voluntary stewardship programs to influence practical EPR metrics and to secure transitional carve-outs for advanced recycling technologies.
How to use the intelligence in Q1–Q2 2026
Use our market sizing and scenario outputs to refine budgets, prioritize capex, and stress-test supply agreements. Specifically:
- Embed the forecast models into procurement annual planning to quantify the value of recycled vs. primary inputs under multiple price paths.
- Run a rolling 12–18 month pilot portfolio (collection → sorting → recycling) with clear KPIs for recovery yield, time-to-market for recovered materials, and net carbon improvements.
- Commit to one strategic partnership (technology provider, recycler, or advanced-materials firm) to signal market intent and accelerate internal alignment around circular-design targets.
Call to action — what you’ll gain from the full report
The complete PW Consulting E-waste Recycling Market report contains the full segmentation, granular regional and application-level analyses, proprietary recovery-yield assumptions, and downloadable financial models that we intentionally omit here to preserve the value of the primary research. Subscribers gain access to:
- Detailed regional and application splits and their implications for logistics and capex planning,
- Company-level benchmarking with scorecards across technology, certification, and scale, and
- Full scenario P&L files that you can drop into your investment committees for immediate use.
Closing perspective
2026 is a pivotal execution year: the market size, trajectory, and underlying structural drivers create both the urgency and the optionality to convert sustainability commitments into defensible commercial advantage. Whether your mandate is procurement, corporate strategy, or investment origination, the strategic choices you make now — around partnerships, technology exposures, and scale plays — will determine whether you capture disproportionate share of the value created by a market that is forecast to grow rapidly over the next decade.
PW Consulting’s full report provides the granular evidence base and the practical tools to translate that growth into repeatable, measurable outcomes. Contact our Strategy & Industry Analysis team to arrange a briefing and receive the subscriber deck and models.
For detailed analysis of this topic, please visit the official page: E-waste Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


