



PW Consulting: Optocouplers Market to Grow at 9.1% CAGR Through 2032

Optocouplers Market: Strategic Imperatives for 2026
Executive preview
As companies set strategy for 2026, understanding the optocouplers market is no longer a niche engineering concern — it is a board-level question touching product roadmaps, supply-chain resilience, and regulatory compliance. PW Consulting’s latest market study (base year 2025) shows a clearly accelerating market: the optocouplers industry grew from an identifiable base in 2020, progressed steadily through 2025, and the forecast through 2032 projects continued expansion at a compound annual growth rate of 9.1%. By 2032 the market is expected to nearly double relative to the 2020 starting point, underscoring a multi-year opportunity window for component suppliers, systems integrators and OEMs that move early on capability and sourcing strategies.
Optocouplers Market
Market trajectory and why it matters
-
Growth profile. The structural drivers are well established — electrification of systems, higher-voltage power conversion, pervasive digital isolation requirements, and renewed demand for robust galvanic isolation across industrial, automotive and defense segments. The result is an aggregate market that has expanded year-on-year and which our forecast indicates will sustain mid-to-high single-digit CAGR through the late 2020s.
Optocouplers Market -
Concentration dynamics. Market concentration is meaningful: the top three suppliers account for a majority share, and the top five strengthen that position further. This concentration creates both risks and opportunities — from supplier power over lead times and pricing to targeted acquisition targets for firms seeking fast access to IP and manufacturing capacity.
Optocouplers Market -
Operational context. Semiconductor input costs and logistics continue to evolve. Import prices for semiconductor manufacturing fell modestly over the 2021–2024 period, while component lead times in optocouplers currently range broadly, creating a premium tier for short-lead or guaranteed-delivery product lines. At the macro level, semiconductor exports from major supplying countries demonstrate continued global demand for upstream capacity — a context that will shape sourcing and localization choices in 2026.
Key demand and regulatory drivers
-
Functional safety and standards. Regulatory frameworks such as ISO 26262 and standards specific to isolation devices are now explicit decision criteria in automotive and industrial procurement. Compliance is not optional for suppliers that want to win high-value system contracts; early-stage design verification and qualification projects must be budgeted into 2026 product plans.
-
Performance thresholds. Applications increasingly require high common-mode rejection, faster logic throughput and proven high-voltage isolation techniques. These performance attributes are defining product roadmaps for established suppliers and influencing purchasing specifications for system integrators.
-
Segment acceleration. Multiple application vectors — from power electronics in renewable energy to ADAS and in-cabin electronics — are expanding the addressable market and changing the relative importance of speed, isolation voltage and packaging density in supplier selection.
Competitive landscape: what to watch
The competitive environment is characterized by technically differentiated incumbents and a handful of specialists that serve high-reliability niches. The report’s supplier profiles analyze strategy, product strengths, route-to-market and recent moves; a few illustrative strategic positions are summarized below.
-
Broadcom Inc. (San Jose) — Focuses on industrial-grade, high-reliability optocouplers with exceptional common-mode rejection, targeting power and data isolation in demanding systems. Their product emphasis raises the bar for performance-sensitive applications.
-
Vishay Intertechnology (Malvern) — Concentrates on high-isolation-voltage parts across wide temperature ranges, appealing to both industrial and consumer electronics customers that demand durability and flexible output configurations.
-
onsemi (Scottsdale) — Emphasizes high-speed logic-gate optocouplers and innovative packaging that supports noise-immune isolated communications, especially for heavy-industrial environments.
-
Renesas Electronics (Tokyo) — Differentiates through space- and radiation-qualified devices, a critical credential for aerospace and defense systems where qualification cycles and supply security are strategic priorities.
-
Lite-On, Everlight, TI and Teledyne Micropac — Each plays distinct roles: Lite-On and Everlight provide breadth across logic-output and phototransistor portfolios; TI pursues hybrid isolation approaches that blend opto and digital isolation benefits; Teledyne Micropac specializes in MIL-grade, high-isolation phototransistor devices.
-
Recent supplier actions also underscore momentum: a notable example is a late-2025 high-voltage phototransistor launch by a specialist supplier, and the same supplier’s distribution partnership to expand availability in channel networks — moves that accelerate access to high-reliability devices for systems integrators.
Strategic implications for 2026 decision-makers
Our analysis translates market movement into seven pragmatic imperatives for executives crafting corporate, product and sourcing strategies in 2026.
-
Prioritize functional-safety readiness. Allocate engineering and certification resources early. Component qualification cycles for ISO 26262 and related isolation standards will materially affect time-to-market for safety-critical systems.
-
Differentiate through system-level value. Optocouplers are no longer just isolation parts — they are safety and EMI-management enablers. Product teams should bundle isolation strategy with system diagnostics, fault reporting and modular replacement pathways to capture higher-tier BOM value.
-
Lock in supply through layered sourcing. Given lead-time variance and supplier concentration, create a three-tier sourcing model: primary long-term contracts with performance KPIs; certified secondary suppliers for cross-qualification; and a qualified short-lead pool for ramp events.
-
Consider bolt-on M&A for capability gaps. With top players controlling a significant portion of the market, targeted acquisitions or partnerships can rapidly fill gaps in high-voltage, radiation-qualified or high-speed logic portfolios — and can be more time- and cost-effective than internal development.
-
Price for predictability. Introduce contract structures that reflect lead-time premiums and scarcity pricing — while offering volume-linked incentives for partners willing to commit to longer-term schedules.
-
Localize where mission-critical. For aerospace, defense and certain automotive programs, near-shore or on-shore manufacturing and inventory buffers reduce geopolitical and logistic risks, and in some procurements, are now procurement prerequisites.
-
Invest in test, qualification and field monitoring. Suppliers and OEMs that can demonstrate robust ATE processes, accelerated stress testing and field telemetry for isolation integrity will win higher-trust contracts and reduce lifecycle support costs.
What PW Consulting’s report delivers (practical edition)
The full study is structured to move beyond high-level narratives into actionable tools for decision-makers. Deliverables include:
-
Proprietary historical market sizing (2020–2025) and scenario-based forecasts (2026–2032) with a transparent methodology and sensitivity testing around macroeconomic and semiconductor-cycle assumptions.
-
Supplier scorecards that evaluate technology differentiation, qualification depth, manufacturing footprint, channel strategy and financial strength.
-
Supply-chain and logistics analysis that quantifies lead-time risk, import-price trends and options for inventory and contractual hedging.
-
Regulatory and standards matrix mapping optocoupler types to compliance requirements (useful for procurement, quality and engineering teams).
-
Commercial playbooks: recommended contracting language, pricing levers and product roadmaps aligned to high-value applications.
-
Scenario frameworks for M&A and partnership evaluation, including quantified return-on-investment models under alternative uptake and pricing scenarios.
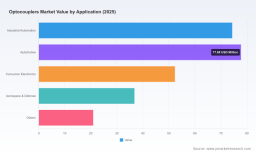
Note: This article purposefully omits granular regional and application split figures to preserve the research’s role as a strategic asset. The full report contains the detailed subsegment tables, regional breakouts and application-level forecasts necessary for procurement and M&A diligence.
How to convert insight into action: a 90/180/360 day roadmap
-
0–90 days: Conduct an internal audit of all designs that reference isolation components; identify programs at risk from lead-time or qualification gaps. Begin cross-qualification testing with at least one certified secondary supplier for each critical SKU.
-
90–180 days: Align procurement with engineering to negotiate long-term agreements with clearly defined SLAs and failure remediation clauses. Initiate targeted supplier audits and qualify localized buffer manufacturing where justifiable by program margin or risk.
-
180–360 days: Execute product differentiation plans — add diagnostics, telemetry or integrated safety features. Evaluate strategic acquisitions or partnerships to accelerate entry into high-reliability or high-speed segments, using the report’s M&A models to prioritize targets.
Closing perspective
For 2026, the optocouplers market represents both a tactical supply-chain challenge and a strategic product opportunity. Companies that respond through integrated product, sourcing and compliance strategies will secure not only continuity of supply but greater share of system value. PW Consulting’s full Optocouplers Market report packages the quantitative forecasts, supplier intelligence, and playbooks necessary to move from reactive procurement to proactive, value-driven strategy.
Next steps
-
To access the full dataset — including granular subsegment and regional breakdowns, supplier financials and downloadable scenario models — request the complete report or schedule a briefing with PW Consulting’s industry practice.
-
For immediate questions about how the findings affect your product lines or procurement strategy in 2026, contact our advisory desk to set up a tailored workshop.
For detailed analysis of this topic, please visit the official page: Optocouplers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


