



PW Consulting: Surgical Navigation Market Poised for 6.98% CAGR Through 2032

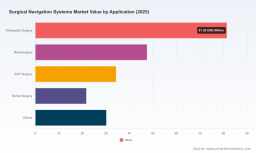
Surgical Navigation Systems Market — Strategic Preview for 2026 Decision‑Makers
This briefing is crafted as the executive “trailer” for PW Consulting’s full Surgical Navigation Systems Market study (base year 2025, forecast 2026–2032). It presents the high‑level, data‑driven arc of the market, the regulatory and commercial vectors that will matter most to corporate strategy in 2026, and a disciplined view of competitive dynamics — while intentionally withholding detailed segment tables and granular market share figures to preserve the value of the full report.
Surgical Navigation Systems Market
Executive summary — the market in a sentence
After steady expansion through the early 2020s (from roughly USD 163 million in 2020 to USD 215 million in 2025), the surgical navigation systems market is set to accelerate under sustained clinical adoption and technology convergence, growing at a compound annual growth rate (CAGR) of 6.98% in our forecast period and reaching an anticipated USD 345 million by 2032. For 2026 corporate planning cycles, this growth profile translates into predictable top‑line expansion and a wide window for strategic moves — from commercialization and service models to M&A and platform investments.
Surgical Navigation Systems Market
Why this matters for 2026 decisions
-
Timing: 2026 is the hinge year between early‑adopter diffusion and mainstream procurement. Recent waves of regulatory clearances and product launches are unlocking the US market for new entrants and new modalities; organizations that act in 2026 can capture early share in fresh use cases.
Surgical Navigation Systems Market -
Capital allocation: With mature players investing in platform integration and a number of specialized entrants scaling commercialization, boards must decide whether to invest in internal R&D, buy capabilities, or pursue partnerships. The report’s quantitative scenarios make these tradeoffs explicit across price, adoption, and service margin assumptions.
-
Go‑to‑market design: Hospital purchasing behavior is shifting toward bundled OR technology purchases and clinical outcomes‑driven procurement; 2026 planning should prioritize bundled clinical evidence, flexible financing, and service & uptime guarantees.
Market trajectory & what the numbers imply
Between 2020 and 2025, the market expanded materially: historical sizing shows a clear recovery and re‑acceleration after 2020–2021 market disruption. Using 2025 as the base year, our model projects growth from USD 215 million in 2025 to roughly USD 231 million in 2026 and onward to USD 345 million by 2032 under a 6.98% CAGR. Those headline figures mask important structural shifts: the market is moving from single‑modality navigation toward hybrid workflows that combine imaging, augmented reality (AR), artificial intelligence (AI) assistance, and instrument tracking. The net effect is higher system ASPs for premium platforms, new recurring revenue opportunities from software and services, and a widening TAM that spans orthopedics, neurosurgery, ENT, thoracic and breast lesion localization.
Competitive landscape — themes and player implications
The competitive field ranges from global medtech giants to focused specialists and deep‑tech startups. Key trends we highlight in the full study are outlined below with representative examples:
-
Platform incumbents extending capability sets: Established OEMs are integrating navigation into broader imaging and OR orchestration platforms. Expect continued investment from major health systems and platform players that can bundle navigation with imaging and intraoperative analytics.
-
Specialists driving modality innovation: Smaller, focused firms are bringing highly differentiated solutions to specific procedures — AR in joint replacement, AI‑powered neuronavigation, and in‑body spatial intelligence for lesion localization. These companies often move faster on regulatory clearance cycles and create pressure on legacy providers to adapt or partner.
-
Recent regulatory momentum: Several entrants secured significant US clearances in late 2025 and 2026, catalyzing market access. These events materially change competitive dynamics by enabling expanded clinical adoption in the US and accelerating sales cycles for cleared systems.
Representative company vignettes (high‑level):
-
Brainlab AG — Munich: Known for optical and electromagnetic platforms and expanding mixed‑reality guidance for spine procedures; recent FDA clearance and US launch activity signal aggressive commercialization in the world’s largest market.
-
Stryker, Medtronic, Zimmer Biomet — Global OEMs: Leverage scale and installed bases to bundle navigation into orthopedic, spine, and cranial ecosystems; strategic responses will include price‑performance repositioning and service contracts.
-
Synaptive Medical, Zeta Surgical, Pixee Medical, Elucent Medical — Specialists: Deliver focused, high‑value tools (e.g., neurosurgical imaging/navigation, AR for TKA, lesion localization). Their FDA clearances in 2025–2026 materially change product mix opportunities for hospitals.
-
Fiagon, KARL STORZ, B. Braun — Niche and procedural specialists: Compete on procedure‑specific workflows and OR integration, often winning on ergonomics and clinician adoption.
Regulation, reimbursement and infrastructure — strategic levers
-
Regulatory pathway: Surgical navigation systems are primarily regulated as Class II stereotaxic instruments and typically follow 510(k) pathways in the US. This raises the bar for demonstration of substantial equivalence but enables relatively efficient market entry when clinical claims are aligned.
-
Reimbursement dynamics: Select CPT codes now recognize computer‑assisted surgical navigation for musculoskeletal procedures, improving procedural economics for hospitals and accelerating procurement decisions. However, reimbursement is procedure‑specific and varies by payer; the full report maps payer coverage and coding levers by application.
-
Capital & operational infrastructure: Advanced navigation platforms remain capital‑intensive; hospital capital budgets and financing structures (including device as a service) will determine adoption pace. Our synthesis uses market‑validated capital ranges and service cost models to stress‑test purchase vs subscription scenarios.
-
Safety & quality: Class II device recalls linked to assembly or tracker issues are a persistent operational risk; lifecycle support, field service response times, and spare‑parts supply chains are now core competitive differentiators.
What the PW Consulting report delivers (practical, actionable outputs)
-
Top‑down market sizing and bottom‑up forecast model (base year 2025; forecast 2026–2032) with scenario toggles for adoption, pricing erosion, and service revenue composition.
-
Commercial playbooks — go‑to‑market options for OEMs, fast followers, and startups including distributor vs direct sales economics, hospital procurement playbooks, and value communication frameworks for clinical buyers.
-
Regulatory and reimbursement roadmaps — actionable checklists for US 510(k) strategy, clinical evidence generation, and payer coding pathways.
-
Competitor profiles and capability matrices — comparative analysis across product architecture, integration, regulatory status, and installed base behavior (high‑level, not disclosing proprietary segment tables in this preview).
-
M&A & partnership targets — prioritized lists with rationale and valuation benchmarks under multiple scenarios; integration risk frameworks for acquirers.
-
Implementation tools — downloadable model templates and decision trees to quantify ROI of different commercialization and pricing choices over 3–7 year horizons.
Strategic recommendations for 2026 (prioritized)
-
For global OEMs: Accelerate platform convergence by bundling navigation with intraoperative imaging and analytics. Prioritize service margin expansion through extended warranties and SaaS modules for analytics and instrument tracking.
-
For focused innovators: Use the 2025–2026 FDA clearances as a springboard for concentrated clinical studies that prove improved operative efficiency or outcomes; negotiate pilot programs with high‑volume centers to secure reference cases and reimbursement traction.
-
For hospitals and health systems: Evaluate navigation purchases under total cost of ownership frameworks that include capital, consumables, and case throughput impacts. Consider capital leasing or device‑as‑a‑service models to preserve budget flexibility.
-
For investors and PE: Target companies with proprietary software ecosystems and high recurring revenue potential. Avoid models that rely exclusively on hardware ASP arbitrage without an attached service or software monetization strategy.
How to use the underlying data in 2026 planning
The full dataset and scenario models enable three immediate uses for 2026 planning cycles:
-
Portfolio prioritization — quantify return on investment for new navigation modules, software upgrades, or acquisition targets using sensitivity bands for adoption and pricing.
-
Commercial pilots — size addressable opportunity at an account‑level and build a 12–24 month pilot roadmap that ties clinical endpoints to procurement triggers.
-
Regulatory and payer sequencing — align product rollout with reimbursement milestones and US regulatory windows to maximize launch ROI and minimize rollout friction.
Closing note — the value of the full study
This preview surfaces the strategic inflection points that will define winners and followers in surgical navigation through the coming decade: platform integration, service‑driven revenue models, regulatory momentum, and targeted clinical evidence. For decision‑makers planning 2026 CAPEX, M&A, or go‑to‑market strategies, the full PW Consulting study provides the quantitative forecasts, competitor matrices, and executable playbooks required to translate market growth into defensible market share — with practical tools to stress test scenarios against your organization’s risk tolerance and capital constraints.
To access the complete market models, competitive breakdowns, and bespoke scenario templates referenced in this preview, consult the full report and dataset on PW Consulting’s source page.
For detailed analysis of this topic, please visit the official page: Surgical Navigation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


