



PW Consulting: Flying Probe Testers Market to Grow at 3.2% CAGR to USD 209.77M by 2032

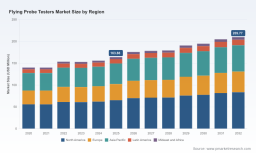
Flying Probe Testers Market — Strategic Briefing for 2026 Decision-Makers
Between the aftermath of supply-chain shocks and the accelerating complexity of PCB assemblies, flying probe testers have moved from a niche diagnostic tool to a strategic capability for many electronics manufacturers. Our latest market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — quantifies this shift and converts it into pragmatic guidance for executives preparing 2026 investment decisions. In short: the market is growing, innovation is concentrated among a handful of suppliers, and the right timing and deployment model can materially improve time-to-market and cost-per-test for high-mix, low-to-medium volume production.
Flying Probe Testers Market
Market at a Glance (Strategic Macro Facts)
- Base year and historical window: 2025 and 2020–2025 respectively, with a forecast period through 2032.
- Compound annual growth rate: 3.2% across the forecast window, reflecting steady expansion driven by higher board density and the need for flexible, no-fixture testing.
- Macro scale: The global market grew from early-decade levels and reached a substantive total in 2025; projections show continued expansion through 2032 aligned with moderately rising adoption across PCB manufacturers and EMS providers.
- Market concentration: The sector exhibits moderate concentration (CR3 ~51%, CR5 ~62%), indicating a balance between incumbent strength and opportunities for niche challengers.
Why this Study Matters for 2026 Strategic Choices
2026 will be a pivotal year for capital allocation in test and quality functions. Decisions taken then — whether to retrofit, replace, or scale testing capability — will ripple through 2027–2030 cost-performance and product quality outcomes. Our study decodes that horizon into operational levers:
Flying Probe Testers Market
- Investment timing: Align CapEx with the product lifecycle of high-density boards to capture cost-per-test improvements that accrue from newer probe architectures and parallel multi-domain systems.
- Supplier selection: Use a vendor scorecard that weights probing accuracy, dual-sided throughput, software integration (ODB++ compatibility), and roadmap transparency — criteria that our vendor benchmarking rigorously scores.
- Risk mitigation: Quantify supplier concentration and raw-material lead times to build a resilient procurement plan covering high-precision probe alloys and long-lead components.
Key Market Dynamics — What’s Driving Value
The marketplace is shaped by a handful of structural and technical forces that intersect differently by end-user profile (bare-board manufacturers vs. EMS providers) and by product complexity.
Flying Probe Testers Market
- Technical innovation. Vendors are pushing simultaneous double-sided probing, micro-current detection to picoamp ranges, and multi-head parallel architectures. These features reduce cycle time for high-density boards and extend the applicability of flying-probe systems into assemblies previously reserved for bed-of-nails ICT.
- Demand patterns. Growth stems from two complementary needs: reducing fixture costs for low-volume high-mix work, and enabling fast NPI cycles where quick test program turn-up matters more than per-unit throughput at scale.
- Supply-side frictions. High-precision probes and probe fixtures depend on specialty copper alloys and precision machining with lead times that can exceed those for traditional ICT components. That affects procurement cadence and safety-stock policies for 2026–2027.
- Regulatory and data-format requirements. Effective deployment increasingly mandates ODB++ readiness and timely firmware updates to handle complex CAD-to-test translations; non-compliance creates program delays and engineering rework.
Competitive Landscape — Who Matters and Why
The sector’s competitive map is characterized by specialized equipment makers with differentiated technology approaches. Our analysis highlights several suppliers whose product strategies are shaping procurement conversations:
- Takaya Corporation (Japan) — A leader in ultra-high-speed, high-precision dual-sided probing. Recent product introductions emphasize simultaneous double-sided inspection and higher probing accuracy, positioning them for customers focused on throughput and high-density mounted board testing.
- Hioki E.E. Corporation (Japan) — Differentiates through high-sensitivity micro-current detection and optimization for bare-board inspection. Their trajectory suggests appeal to quality-driven bare-board suppliers and labs requiring fine-grain electrical characterization.
- Acculogic Inc. (United States) — Offers flexible, no-fixture systems supporting a mix of in-circuit, functional and optical testing. Their platforms are attractive to complex-board EMS providers seeking test flexibility rather than high-speed mass throughput.
- SPEA S.p.A. (Italy) — Focuses on parallel multi-domain architectures that scale throughput via concurrency rather than single-head speed. Their approach suits high-variation production where parallelization improves annual board capacity.
- Seica S.p.A. (Italy) — Emphasizes capacity for large boards and deep component profiles, catering to industries producing physically large or tall-component assemblies.
- Digitaltest GmbH (Germany) — Known for modular multi-head systems with optional features for loaded-board in-circuit testing and a focus on automation integration.
Recent vendor developments in late 2025—new product launches and trade-show presentations—underscore a competitive phase where vendors are racing to lock in design wins with advanced probing capabilities. For acquirers and procurement teams, this means negotiating not just on price but on roadmap commitments, service SLAs, and integration support for engineering change cycles.
What the Report Provides — Operational Deliverables
This study is deliberately designed as a practical playbook for 2026 execution. Key deliverables include:
- Scenario-based forecasts (2026–2032) with sensitivity to probe-technology adoption rates and EMS demand swings.
- Vendor benchmarking and an evidence-based scorecard you can apply to procurement shortlists (performance, integration readiness, TCO, spare-part exposure).
- CapEx vs. retrofit decision models that quantify payback windows under NPI ramp and high-mix production patterns.
- Supply-risk heatmaps focused on probe metallurgy, fixture lead times, and firmware compliance with modern CAD-to-test frameworks.
- Implementation playbooks: pilot design, test program creation, sample management, and a phased rollout template for scaling from prototype to volume production.
- Governance checklist for cross-functional adoption ensuring the test group, manufacturing engineering, and procurement align on data formats (e.g., ODB++) and lifecycle update processes.
How Executives Should Use These Insights in 2026
Translate the study into action through three near-term moves:
- Prioritize pilot projects for boards where fixture cost or NPI speed is the primary constraint. Use those pilots to validate vendor claims on throughput, micro-current sensitivity, and CAD-file compatibility.
- Negotiate multi-year service and firmware-update clauses with preferred suppliers to guarantee ODB++ compliance and to secure roadmap visibility for probe-head upgrades. This reduces engineering downtime during new product introductions.
- Implement supply-chain safeguards for probe alloys and precision fixtures — including dual sourcing where feasible and contracted lead-time windows — to avoid shipment delays that cascade into test-line bottlenecks.
Signals to Monitor (Near-Term Triggers)
- Acceleration in product launches that push dual-sided simultaneous probing or higher head parallelism — an inflection here signals a shift in cost-per-board dynamics.
- Movement in supplier concentration (M&A or partnerships) that would change CR3/CR5 profiles and reshape bargaining power.
- Changes in firmware or CAD-file standards — a near-term change could force rework of test program pipelines across the industry.
- Supply tightness in precision alloy machining and fixture lead times — a leading indicator of potential deployment delays.
Final Note — Where this Brief Fits in Your Decision Toolkit
This briefing synthesizes the strategic implications of a market that continues to grow at a measured pace (3.2% CAGR through our forecast) and where technical differentiation, supply resilience, and integration readiness determine winners. For procurement, engineering, and corporate development teams, the full report delivers the granular data, scenario models, and vendor scorecards required to convert these strategic takeaways into procurement contracts, pilot scopes, and CapEx decisions.
For executives ready to translate insight into action: our comprehensive report and downloadable model include the granular segmentations, regional and application-level breakouts, and vendor datasets that underpin the recommendations above. Access to the full dataset is the fastest path to quantify ROI for your specific product portfolios and to construct a defensible 2026 test-equipment roadmap.
For detailed analysis of this topic, please visit the official page: Flying Probe Testers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


