



PW Consulting: Laryngoscope Market Set to Expand at 7.41% CAGR

Laryngoscope Market 2026: Strategic Imperatives for Manufacturers, Providers and Investors
The global laryngoscope market has entered a decisive phase. Our PW Consulting baseline analysis (base year 2025) shows the market expanding from roughly USD 416.6 Million in 2020 to about USD 595.5 Million in 2025, with a projected trajectory that reaches just under USD 1.0 Billion by 2032. This represents a compound annual growth rate of 7.41% through the 2026–2032 forecast window. These headline figures mask a complex interplay of technology migration, regulatory realignment, clinical workflow pressures and shifting procurement economics — all of which make 2026 a year of strategic choice for vendors, health systems and capital providers.
Laryngoscope Market
Why 2026 Is a Pivotal Year
-
Technology convergence: Video-based imaging, single-use disposables and modular, serviceable platforms are converging. Vendors who can combine high-quality optics with compelling total-cost-of-ownership (TCO) propositions will capture disproportionate share of the growth opportunity.
Laryngoscope Market -
Regulatory modernization: International standards and regulatory recognition have tightened expectations for imaging performance, durability and patient safety. ISO updates specific to laryngoscope performance and video-imaging requirements, alongside agency-recognized consensus standards, mean product roadmaps must now bake compliance into early-stage designs rather than treat it as a late-stage checkbox.
Laryngoscope Market -
Procurement and operational economics: Infection control imperatives and sterilization burdens are accelerating adoption of disposable elements in the airway market. Eliminating sterilization cycles can materially free up operating-room time and staff capacity — an operational benefit hospitals explicitly quantify when comparing options.
-
Commercial dynamics: Market concentration is meaningful but not prohibitive. The top three suppliers account for a majority of revenue, and the top five for a substantially larger share — creating both stability at the top and attractive whitespace for challengers with differentiated models (e.g., single-use platforms, pay-per-use servicing, or superior imaging performance).
What PW Consulting’s Laryngoscope Market Report Delivers (Operationally)
This study is built as a decision-ready toolkit for 2026 planning cycles. Rather than a passive overview, the report provides layered, actionable output that supports strategic plays across R&D, commercial and clinical operations:
-
Robust market-sizing and transparent forecast methodology covering 2020–2025 history and a detailed 2026–2032 projection framework with scenario-analysis (base / upside / downside).
-
Adoption-curve models for camera-based scopes, direct vs indirect technologies and single-use consumables, enabling demand-by-adoption-stage estimates useful for capacity planning and inventory management.
-
Total cost of ownership (TCO) models comparing reusable platforms plus sterilization overhead versus disposable and hybrid approaches — calibrated to labor, sterilization and device lifecycle inputs.
-
Regulatory and standards playbook that maps ISO and agency-recognized requirements to product development checkpoints, clinical validation protocols and post-market surveillance obligations.
-
Procurement decision frameworks for health systems: build vs buy analyses, strategic sourcing templates, and service-level agreements (SLA) geared to OR throughput, infection-control targets and capital budgets.
-
Competitive landscaping with qualitative scorecards (technology leadership, channel reach, service model, pricing posture) and a short-list of potential M&A and partnership targets drawn from observed product launches and capability gaps.
-
Go-to-market playbooks for entrants and incumbents — covering channel segmentation (OEM, distributor, direct hospital sales), pricing experimentation, and consumable-led recurring revenue strategies.
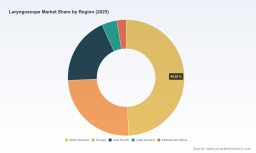
To preserve commercial value for our clients, this article intentionally omits the granular regional, application and type-level tables that underpin the report. Those disaggregated splits, unit economics and supplier-level revenue breakdowns are available in the full study.
Competitive Landscape — Strategic Takeaways
The competitive field combines broad incumbents with niche specialists. Recent product activity through 2025 underscores how firms are positioning along two axes: imaging quality and infection-control economics.
-
Medtronic — Leveraging a cross-care setting footprint, its McGRATH MAC family targets OR, ICU and pre-hospital airway needs; strategy centers on clinical integration and ecosystem lock-in via training and service.
-
Karl Storz — Maintains a reputation for optical excellence; recent blade enhancements emphasize visualization in complex airway scenarios, defending a premium imaging segment.
-
Ambu — A clear leader in disposable, single-use devices; the aScope series and iterations demonstrate a playbook built on infection control, simplified workflows and recurring consumable revenue.
-
Verathon — Focused on GlideScope platforms, now pursuing hybrid economics with reusable primaries and single-use covers to balance cost and safety; pediatric portfolio expansions indicate targeted segment growth.
-
Teleflex and other global OEMs — Compete with integrated handle systems and infection-control features, seeking procurement wins via bundled supply and hospital-standard compatibility.
-
Imaging specialists and consumables players — Olympus, Smiths Medical, Vyaire, Penlon, Flexicare and Truphatek fill niches across premium imaging, disposable blades and procurement-focused consumables, creating a layered ecosystem where partnerships frequently trump head-on price competition.
Recent product launches during 2025 — from ClearFit cover-based approaches to next-generation disposable scopes and enhanced optics — illustrate two concurrent strategic threads: improving clinical visualization, and reducing cross-contamination risk while improving OR throughput.
Critical Strategic Choices for 2026
-
For manufacturers: Prioritize modular platforms that permit both reusable and disposable elements. Design for regulatory compliance to new ISO imaging and durability standards early. Build a consumables revenue engine and a service layer that shifts buyer focus from upfront device cost to lifetime TCO.
-
For health systems: Re-evaluate procurement cycles with OR throughput and infection-control targets as primary KPIs. Centralize device purchasing to negotiate bundled service and consumable contracts, and use pilot programs to validate disposable vs. reusable TCO in local workflows.
-
For investors and M&A teams: Target assets that strengthen recurring revenue (consumables, covers, software services) or that close capability gaps in imaging and pediatric solutions. Look for targets where integration can shift market share by improving hospital economics.
-
For regulators and payers: Expect standardization activity to reshape product claims and post-market obligations. Stakeholders should collaborate to align reimbursement mechanisms with clinical outcomes and device lifecycle impacts to de-risk transitions to single-use technologies.
Signals to Monitor Through 2026
-
Adoption velocity of disposable and hybrid video laryngoscopes in high-volume ORs and emergency settings;
-
Regulatory guidance and formal recognition of updated ISO standards that govern video imaging and device durability;
-
Procurement tenders reflecting a shift from capex-led purchases toward bundled device-plus-consumable agreements;
-
Innovations in sterilization technology (including accelerated HLD methods and UV-C LED options) that could alter the reusable vs. disposable calculus;
-
Competitive moves — targeted product launches, pediatric portfolio expansions and cover-based hybrid models — that reveal which commercial playbooks are gaining traction.
Conclusion — How This Report Supports 2026 Decision-Making
Transitioning from insight to action in 2026 requires a clear map of clinical, regulatory and commercial inflection points. PW Consulting’s Laryngoscope Market report synthesizes market growth trajectories (base year 2025; 2026–2032 forecast with a 7.41% CAGR), regulatory shifts, supplier positioning and operational levers into an actionable intelligence package. This article provides the strategic trailer: it reveals the forces shaping the market and the high-level responses that will matter. For the granular segmentation tables, supplier revenue breakdowns, unit economics models and configurable TCO calculators that operational teams need to execute, please consult the full report and supporting datasets available on our publication page.
For detailed analysis of this topic, please visit the official page: Laryngoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


